- SGD bonds generally saw volatile mark-to-market movements on prices this year and issuances dropped to a low as compared to the past two years.
- We continue to favour short-tenor Singapore Government Securities and expect yields for the 6-months and 1-year Treasury Bills to remain elevated and rangebound.
- We expect to see more issuances in 2024, with bank bonds continuing to be an attractive area for investors.
2023 in review
2023 had been another challenging year for fixed income markets and SGD bonds generally suffered from the volatile mark-to-market movements on the bond prices. The impact of higher interest rates also weighed on SGD bond issuance in 2023 as the elevated cost of capital backdrop made it hard for Singapore corporates to issue SGD debt. Most companies preferred to refinance with shorter-term floating-rate borrowings through bank loans, rather than locking in fixed rates on medium-term notes.
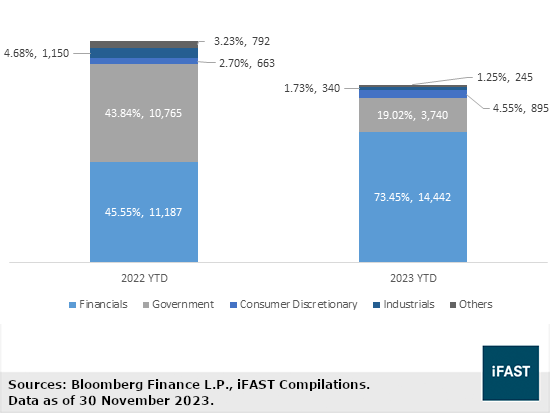
As such, 2023 saw a significant drop in SGD bond issuances as compared to the past several years (Chart 2), falling to a low of SGD 19.66b. Issuances across all sectors generally fell across the board, with the Financials sector being a clear exception. Instead, the latter accounted for a large majority of SGD issuances in 2023 – increasing from SGD 11,187m (45.55% of total issuances) in 2022 YTD to SGD 14,442m (73.45% of total issuances) in 2023 YTD.
Chart 1
Yields
on the Singapore Government Securities for 2023 (%)
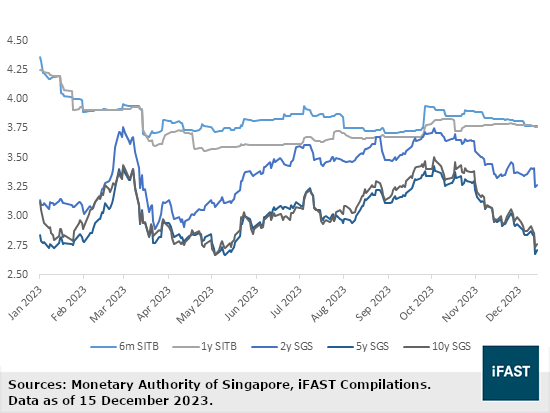
Chart 2
Volume
of bond issuances (by bookrunners) for year-to-date period until 30 Nov (in SGD
m)
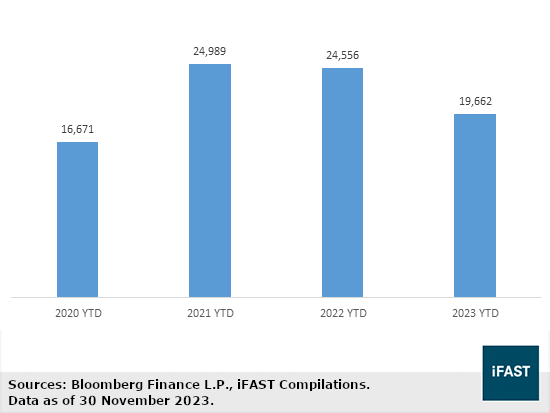
Chart 3
Bond
issuances from various sectors across 2022 and 2023 (in SGD m)
Our view on the Singapore Government Securities in 2024
In the latest Federal Open Meeting Committee meeting in December, the Federal Reserve left the rates unchanged for the third time. Both the meeting statement and updated projections for 2024 suggest that further rate hikes seem unlikely given the current economic data. However, the Fed emphasized that decisions will still depend on ongoing economic data.
In our global fixed income markets outlook, we outlined our expectation for interest rates to remain higher-for-even-longer with rates around the peak. We hold the opinion that inflation is likely to remain elevated as we see upside risk from variables like energy prices while US labor market data remain resilient, bolstering wage growth. As such, we believe the market expectations of Fed rate cuts in 2024 might seem premature and the likelihood of a prolong rate pause is higher.
As we enter 2024, we believe yields on the medium to longer-tenor Singapore Government Securities (“SGS”) may gradually fall if the Fed perpetuates the current trend of rate pause. This should also result in significantly less volatility across yields as well.
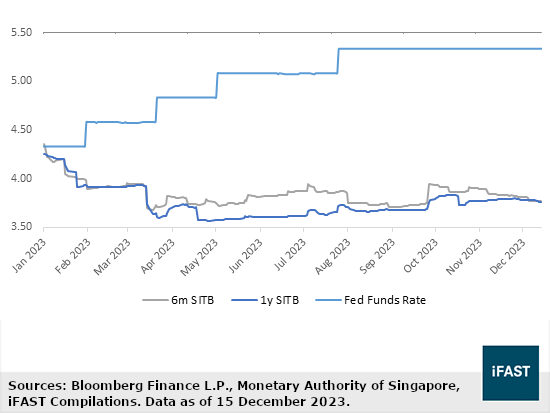
At the shorter end of the curve, we expect yields for the 6-months and 1-year Singapore Treasury Bills to remain within the range of 3.70% to 3.90%. This will be similar to the movement in yields on the T-bills across 2023 (Chart 6), which have remained mostly within this range despite further rate hikes in the year. At the same time, US short-term treasury yields staying higher for longer should allow Singapore short-term treasury yields to hold within this range at least for the first half of 2024.
Between the SGS of various tenors, we prefer the shorter-tenors i.e. 6-months and 1-year Singapore T-bills. We feel that yields on the longer-duration sovereigns remain insufficient in compensating investors for the duration risk. Absent a Fed rate cut in 2024, we also see little catalyst for longer-term yields to fall which limits the capital upside. As such, the shorter-tenor T-bills continue to look highly attractive over the longer-tenor counterparts.
Chart 4
Fed
Reserve rate pause from 2006 to 2007 (%)
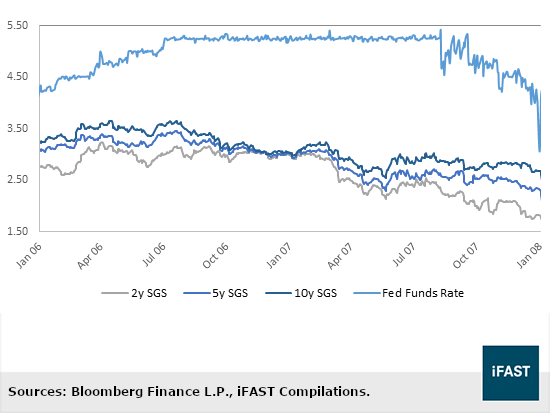
Chart 5
Fed
Reserve rate pause from 2018 to 2019 (%)
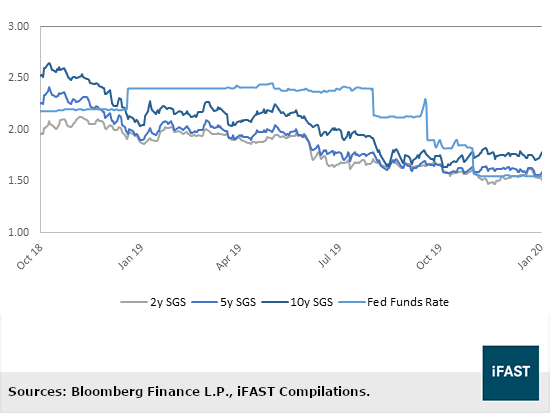
Chart 6
Fed
Funds Rate against yields on the SITBs (%)
Our view on SGD Corporates in 2024
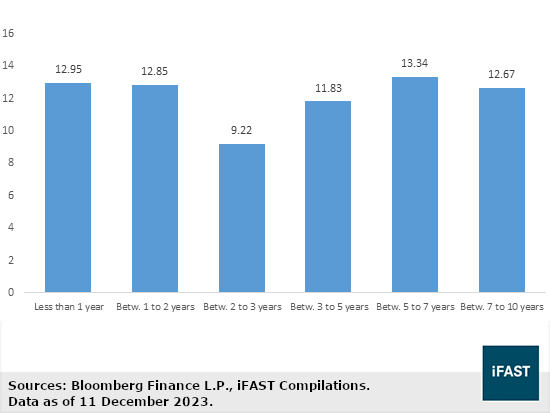
A total of approximately SGD 12.95b worth of bond issuances are set to mature in less than 1 years’ time (Chart 7). Assuming yields remain stable in the coming year, conditions should become more favourable for corporates to consider debt issuance and investors should have more options. Two reasons anchor our view.
Firstly, since the start of the rate hike cycle in 2022, most corporates opted to refinance their debt with short-term floating rate bank borrowings. We believe issuing medium-term notes next year instead of seeking bank financing will help in improving its debt maturity profile and overall credit profile. Secondly, strong demand has been observed in the SGD bond market given the lack of issuances in 2023. The pent-up demand from investors may allow corporates to potentially price their issuances cheaper, reducing the cost of capital. In the back half of 2023, we have already observed several corporates pricing their new bond issuances below expectations and we believe it is likely attributed to overly strong demand.
Entering 2024, we continue to advocate investors to go for quality issuers in the SGD corporate bond space. For corporates under our coverage, we generally observed a deterioration of credit profiles across the board, given the increase in cost of capital as a result of higher interest rates. That said, issuers with a robust credit profile were able to withstand the impact of higher interest rates better and saw milder impact on their financial health. If our view of higher-for-even-longer rates play out, we expect credit profile of the weaker issuers will face greater pressure and spreads may widen further in 2024. This could result in result in mark-to-market price losses for riskier issuers.
Chart 7
Debt maturity schedule for the
upcoming years (in SGD b)
1. Non-call risk remains high for perpetual securities in 2024
Non-call risk on SGD perpetual securities (“perps”) should remain a priority for investors given the higher-for-longer rates outlook. With greater stress on credit profiles as rate rises, spreads on many SGD perps are at a similar or higher level than what they are on the respective reset rates. This means that refinancing perps will be costlier and highly uneconomical for these issuers, especially considering the current high interest rate environment.
As such, we believe investors hunting for higher yield (to call) should be aware of the non-call risk and closely examine the likelihood and ability of the issuer to refinance perps. In Table 1, we listed the perpetuals that have a first call date in 2024.
Table 1
SGD
Perpetuals with first call date in 2024
|
Issues |
First Call Date |
Reset Date and Rate |
|
SINTEC 5.000% Perpetual Corp (SGD) |
17 Jan 24 |
Reset Date: 17 Jan 2029 & every 10
years thereafter |
FPLSP 4.980% Perpetual Corp (SGD) |
11 Apr 24
|
Reset Date: 11 April 2024 and every 5 years thereafter Reset Rate: Prevailing SGD 5Y SOR plus the Initial Spread (3.040%) and the Step-Up Margin (100 bps) |
|
SOCGEN 6.125% Perpetual Corp (SGD) |
16 Apr 24 |
Reset Date: 16 Apr 2024 and every 5 Years
thereafter |
|
WINGTA 4.480% Perpetual Corp (SGD) |
24 May 24 |
Reset Date: 24 May 2024 and every 5 years
thereafter |
|
MAPLSP 3.700% Perpetual Corp (SGD) |
12 Aug 24 |
Fixed-for-life, no rate reset |
|
SPHRSP 4.100% Perpetual Corp (SGD) |
30 Aug 24 |
Reset Rate: 30 Aug 2024 and every 5 years
thereafter |
|
ARTSP 3.880% Perpetual Corp (SGD) |
4 Sep 24 |
Reset Date: 04 Sep 2024 and every 5 years
thereafter |
|
UBS 4.850% Perpetual Corp (SGD) |
4 Sep 24 |
Reset Date: 04 Sep 2024 and every 5 years
thereafter |
|
KEPSP 2.900% Perpetual Corp (SGD) |
16 Sep 24 |
Reset Date: 16 Sep 2026 and every 5 years
thereafter |
|
STANLN 5.375% Perpetual Corp (SGD) |
3 Oct 24 |
Reset Date: 03 Oct 2024 and every 5 years
thereafter |
|
CAPLSP 3.650% Perpetual Corp (SGD) |
17 Oct 24 |
Reset Date: 17 Oct 2024 and every 5 years
thereafter |
|
HPLSP 4.400% Perpetual Corp (SGD) |
22 Oct 24 |
Reset Date: 22 Oct 2024 & every 5 years
thereafter |
|
Sources: Bondsupermart, iFAST Compilations. |
||
2. Bank bonds – the rose among the thorns
Across the various sectors, we continue to favour bank bonds. The senior and Tier 2 subordinated papers, which are mostly investment-grade, have been a popular choice for investors this year as the steep rate hikes have greatly benefitted banks’ profitability. Looking ahead, we continue to foresee expect profit tailwinds for banks, supported by high policy rates and helped by a recovery in loan growth. While most banks are expecting their net interest margins to peak and gradually normalise, earnings are likely to remain higher in the current rates backdrop. At the same time, credit profile for banks is expected to remain stable across 2024, largely due to strong profits recorded in FY23, allowing for improved capital ratios and buffers.
Bank bonds are likely to remain attractive in 2024 given the general profitability and credit profile of the banks, although the risk will vary in accordance to the issuances’ seniority level. We lean towards senior unsecured papers given our preference for quality as it has the highest seniority across bank bonds.
That said, we believe Tier 2 subordinated issuances can offer relatively good yield pick-up for the additional risk. While Tier 2 subordinated papers typically has longer maturities, most issuers are expected to exercise the call option on the Tier 2 papers given the issuer’s incentive to redeem and refinance its Tier 2 capital. For more information about our view on bank bonds, refer to our article here - Idea of the Week: Reasons to continue liking bank bonds.
In the table below, we highlight some of the recommended issuers and their respective SGD bank bonds we have featured on our platform.
Table 2
SGD
bank bonds and issuers featured on our platform in 2023
|
Issuances |
Issuer |
Seniority |
Bond Credit Rating (S&P/Fitch) |
|
Senior papers |
|||
|
Australia & New Zealand Banking Group Ltd |
Senior unsecured |
AA-/ N.R |
|
|
BNP Paribas SA |
Senior non-preferred |
A-/ A+ |
|
|
Deutsche Bank |
Senior non-preferred |
BBB-/ BBB+ |
|
|
HSBC Holdings PLC |
Senior unsecured |
A-/ A+ |
|
|
Macquarie Group Limited |
Senior unsecured |
BBB+/ A |
|
|
Tier 2 Subordinated |
|||
|
Credit Agricole SA |
BBB+/ A- |
||
|
Australia & New Zealand Banking Group Ltd |
BBB+/ A- |
||
|
Barclays PLC |
N.R/ BBB+ |
||
|
BNP Paribas SA |
BBB+/ A- |
||
|
Commerzbank Aktiengesellschaft |
BB+/ Baa3 |
||
|
Commerzbank Aktiengesellschaft |
BB+/ Baa3 |
||
|
HSBC Holdings PLC |
BBB/ A- |
||
|
HSBC Holdings PLC |
BBB/ A- |
||
|
HSBC Holdings PLC |
BBB/ A- |
||
|
Lloyds Banking Group PLC |
N.R/ BBB+ |
||
|
Westpac Banking Corp |
BBB+/ N.R |
||
|
Sources: Bondsupermart, iFAST Compilations. Data as of 11 November 2023. |
|||
Fixed Income Focus 2024
For more dynamic insights, join us on our live webinar on 17 January 2024 at 7 pm. During this session, we will extend our analysis beyond the SGD bond outlook – encompassing discussions on the USD and MYR bond landscapes – alongside a brief overview of the global fixed income markets. Don't miss this opportunity to gain a better understanding of the evolving fixed income environment — register now to secure your spot: https://bit.ly/2024-bond-outlook-webinar
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in ARTSP 3.070% Perpetual Corp (SGD), SINTEC 4.200% Perpetual Corp (SGD), KEPSP 2.900% Perpetual Corp (SGD), ANZ 4.500% 02Dec2032 Corp (SGD), CMZB 5.700% 03May2033 Corp (SGD), CMZB 6.500% 24Apr2034 Corp (SGD), HSBC 5.300% 14Mar2033 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!