Highlights:
- CSI Properties mainly engages in property development and investment. Its features are the sale of luxury apartments and the purchase, sale and investment of commercial real estate. The company’s operating performance was fair. Many of the company's projects entered the pre-sale or sale stages, which would provide strong support to its liquidity and debt repayment.
- The company would adopt a conservative approach to maintain sufficient liquidity. The leverage level is decent, with a simple debt structure. Its cash and short-term investments are sufficient to repay the bond. The bond has a good margin of safety.
- The company’s 2025 USD bond has a yield to maturity of 12.9%, which is worth investors' attention.
CSI Properties is a Hong Kong developer. Its main businesses are property development and property investment. Its features are the sale of luxury apartments and the purchase, sale and investment of commercial real estate. The company generally buys commercial properties, renovates them and/or changes their land use after the acquisition, with an aim to recycle capital and realize capital appreciation within a short period of time.
The company is listed on HKEX (Stock Code: 497.HK), with a market capitalisation of around HKD 1.24 billion.
Far Operating Performance with A Number of Projects in Pre-sales or Sales Stages
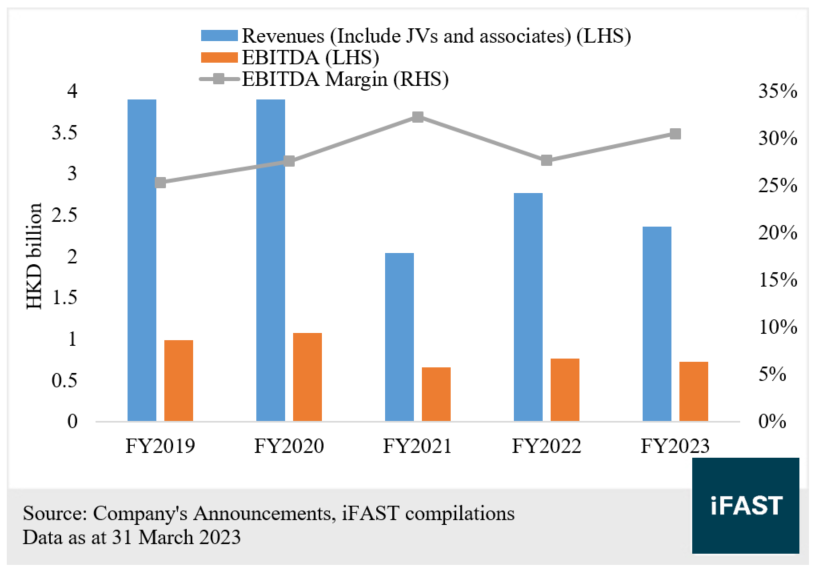
In FY 2023 (April 2022 to March 2023), the company’s sales revenues (including JVs and associates) were HKD 2.0 billion, which decreased by 18% YoY. The rental revenues (including JVs and associates) increased 7% YoY to HKD 360 million. The overall gross margin reached 50%. The EBITDA slightly decreased 6% YoY to HKD 720 million. The operating performance was fair.
Chart 1: CSI Properties’ Revenues, EBITDA and
EBITDA Margin
Many of the company's projects entered the pre-sale or sale stages, mainly high-end residential projects, including the "Dukes Place" and "Cadenza" projects in Hong Kong (see Table 1), with estimated saleable resources of HKD 15 billion or more (based on a gross profit margin of 40% and an attributable book value of properties). The cash flow from sales of these projects would provide strong support to the company's liquidity and debt repayment.
Table 1: A List of Saleable Projects
|
Project Name |
Progress |
Company’s Attributable Interest |
Attributable Book Value of Properties (HKD million) |
|
LL Tower, Central |
Pre-sales |
51% |
1,870 |
|
No. 38 Wai Yip Street |
Pre-sales, with 2 units sold |
30% |
580 |
|
No. 92-96 Wellington |
Pre-sales |
50% |
430 |
|
45 Barker Road Redevelopment |
Planning of Pre-sales |
100% |
660 |
|
Dukes Place |
Pre-sales, with 1 unit sold |
60% |
650 |
|
Cadenza |
Planning of Pre-sales |
92% |
650 |
|
Infinity |
Pre-sales, with 2 units sold |
65% |
720 |
|
Knightsbridge |
Pre-sales, with 12 units sold |
65% |
880 |
|
No. 23 Po Shan Road |
Planning of Pre-sales |
30% |
830 |
|
Yau Tong Ventilation Building Redevelpment |
Pre-sales |
20% |
640 |
|
MTR Wong Chuk Hang Station Property Development Site |
Pre-sales |
15% |
1,620 |
|
Total |
9,530 |
||
|
Sources: Company’s Announcements, iFAST Compilations Data as of 31 March 2023 |
|||
Focus on Tailor-made Luxury Apartments, which might be Priced More Aggressively
The company focuses on tailor-made luxury apartments which are unique in the high-end market. Its brand philosophy is “Full of Wonders”. With a brand premium and high construction quality, it allows the company to be more aggressive when acquiring high-quality land banks, and then the cost is transferred to luxury property buyers, who are more willing to pay more for quality products. We think that this business model could build a differentiation advantage in the niche market.
It is highlighted that Hong Kong's luxury apartments outperformed the market in recent years. According to Knight Frank’s Prime Global Cities Index, the luxury apartments only dropped by 1.3% YoY at the end of the first quarter, much lower than the overall performance reflected by the Centa-City Leading Index of around -6.2% during the same period. This may be due to the scarcity of prime locations (e.g. Jardine's Lookout, Peak Road, etc.) and the limited supply of luxury properties for sale at a discount, while the rich are less affected by COVID-19. Thus, luxury apartments are more resilient in terms of prices.
The policies implemented by Hong Kong Government, such as Northern Metropolis and the Lantau Tomorrow Vision, focus on increasing the supply of private apartments but lack measures to raise the supply of luxury apartments. We believe the luxury apartment prices will continue to be resilient, allowing the company to price luxury apartments more aggressively and achieve a higher profit margin.
Conservative Approach to Maintain Sufficient Liquidity; Good Margin of Safety for the Bond
Against the backdrop of the interest rate hike cycle and the crisis in the Chinese real estate sector, the company indicated that it would adopt a conservative approach in land purchases and new investments, and not make any new acquisitions in the foreseeable future in order to maintain sufficient liquidity.
As shown in Table 2, as of the end of March 2023, the company’s total debt was HKD 11.2 billion, with a net gearing ratio of 55%. Adjusting for unrealised revaluation surplus, the adjusted net gearing ratio was further down to 39%. The leverage level was decent.
The debt structure is quite simple, with 79% of bank loans and 21% of its USD bonds due in 2025. The bank loans are secured so refinancing them is not difficult. The company had cash and short-term investments of HKD 3.7 billion, sufficient to repay about USD 2.96 million (equivalent to HKD 2.3 billion) of the bond. The bond has a good margin of safety.
Table 2: CSI Properties’ Credit Indicators
|
March 2022 |
March 2023 |
|
|
Total Debt (HKD billion) |
11.3 |
11.2 |
|
Cash and Short-term Investments |
4.1 |
3.7 |
|
Asset to Liability Ratio (%) |
45% |
48% |
|
Net Gearing Ratio (%) |
49% |
52% |
|
Adjusted Net Gearing Ratio (Include Unrealised Revaluation Surplus in Total Equity) (%) |
34% |
39% |
|
Net Debt / EBITDA (times) |
9.4x |
10.4x |
|
Interest Coverage Ratio (times) |
2.4x |
1.4x |
|
Cash To Short-term Debt (times) |
1.8x |
1.8x |
|
Sources: Company’s Announcements, iFAST Compilations Data as of 31 March 2023 |
||
Therefore, the 2025 USD bond, “CSIPRO 5.450% 21Jul2025 Corp (USD)”, has a yield to maturity of 12.9% (see Table 3), which is worth investors' attention.
Despite the scale of CSI Properties not being comparable to that of other developers, given the company's stable outlook and sufficient liquidity to repay the bond, we believe that its higher yield can compensate for the lack of scale and the slightly higher risk.
Table 3: CSI Properties’ USD Bond
|
Bond Name |
Years to Maturity |
Ask Price (Investors Buy) |
YTM |
| CSIPRO 5.450% 21Jul2025 Corp (USD) | 2.0 |
87.45 |
12.9% |
|
Source: Bondsupermart Data as of 4 August 2023 |
|||
Related Risks
The concentration of the company’s property pipeline is high. If there are lower-than-expected property sales or pricing issues or delays for a single project, the company’s liquidity might be affected.
Although the company has fewer projects in Mainland China, its sales plans could still be affected by the downturn in Chinese property sales. For the rich who relied on real estate to get rich, there might be a bigger drop in their wealth due to the Chinese real estate crisis. The demand for luxury apartments in Hong Kong or the Mainland could be affected. This impacts the sell-through rate of the company's projects.
Conclusion
CSI Properties mainly engage in property development and investment. Its features are the sale of luxury apartments and the purchase, sale and investment of commercial real estate. The company’s operating performance was fair. Many of the company's projects entered the pre-sale or sale stages, which would provide strong support to its liquidity and debt repayment.
The company would adopt a conservative approach to maintain sufficient liquidity. The leverage level is decent, with a simple debt structure. Its cash and short-term investments are sufficient to repay the bond. The bond has a good margin of safety.
The company’s 2025 USD bond
has a yield to maturity of 12.9%, which is worth investors' attention.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on
the fixed income space. Listen to our latest episode below and follow us!