Highlights:
- NWS Holdings mainly engages in roads, construction, insurance and logistics. The tender offers from CTFE should have a limited impact on NWS. Bond investors need not be concerned about this corporate action. The Group’s overall operating performance is decent. The cash flows and earnings have a higher visibility. NWS is a “company that lays golden eggs”.
- The Group’s credit metrics are decent, with sufficient liquidity and a good leverage level. Combined with the high visibility of the business cash flows, we believe that the Group’s default risk is low.
- Investors could consider the 2029 bond and perpetual bond. Both of them have a certain attractiveness. Amongst these, the 2029 bond has a yield to maturity of 8.5%.
NWS Holdings ("NWS") mainly engages in roads, construction, insurance and logistics. It was established in 2002. The company is currently listed on HKEX (Stock Code: 659.HK) with a market capitalisation of around HKD 36.2 billion.
Tender offers should have Limited Impact on NWS Holdings
New World Development (NWD) currently holds around 61% NWS shares. If the NWS tender offers by Chow Tai Fook Enterprises (CTFE) is approved by the minority shareholders of New World Development, CTFE will become a substantial shareholder of NWS. NWS will become a sister company of NWD (see Chart 1).
Chart 1: Simplified Group Chart after Completion of the NWS Tender Offers
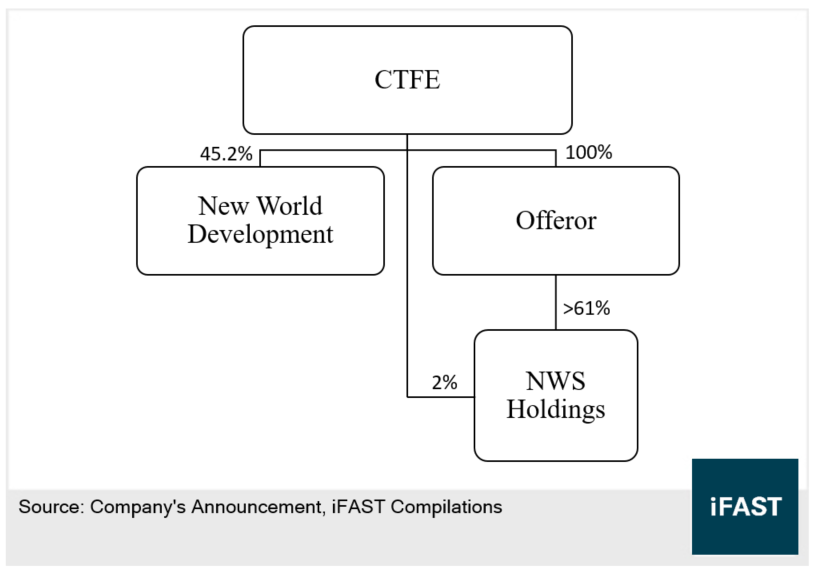
This may alleviate the market's concerns about NWS Holdings’s corporate governance and connected transactions. NWS purchased the office assets from NWD on several occasions, which might cause a small number of investors to suspect a "transfer of benefit" (while we believe the prices were reasonable). With this change in the shareholding structure, we expect the risk of connected transactions between NWS and NWD to be reduced.
At the same time, CTFE intends to maintain NWS Holdings’s listing on the HKEX after the close of the Offers. It means that NWS will not be privatized by CTFE as a result of the Offers and the mandatory takeover notice. In the event that the public float of NWS shares falls below 25% after the completion of the Offers, CTFE would take necessary action to ensure that it complies with the listing requirements. The potential options include a share placement or sales of part of the shares to a third party.
From the document of the offers, CTFE intends to request NWS Holdings to increase its dividend payout ratio and optimise its business and asset portfolio as much as possible. Despite an increase in dividend payout that might affect the company’s cash level, the shareholders generally welcome such a move. Coupled with a clear development direction, these are expected to boost the company’s market capitalization and indirectly enhance its equity financing ability. The optimization of its asset portfolio might imply some asset disposals, which could also be beneficial to its credit profile.
Overall, the offers are expected to have a limited impact on NWS Holdings. The company is still a listed company and is obliged to disclose financial information and earnings results on a regular basis. Its business and fundamentals have not changed. The impact of the change in the Group structure on NWS is slightly positive. Therefore, bond investors need not be concerned about this corporate action.
With Decent Operating Performance, NWS is “the company that Lays Golden Eggs”
As shown in Chart 2, the profit of NWS Holdings mainly comes from road, construction, insurance and logistics segments. The attributable operating profit increased 9.5% YoY to HKD 4.1 billion in fiscal year 2023 (July 2022 to June 2023), which is driven by the growth in the insurance and logistics segments. The operating performance is decent.
Chart 2: NWS Holdings’s Attributable Operating Profit in Each Segment
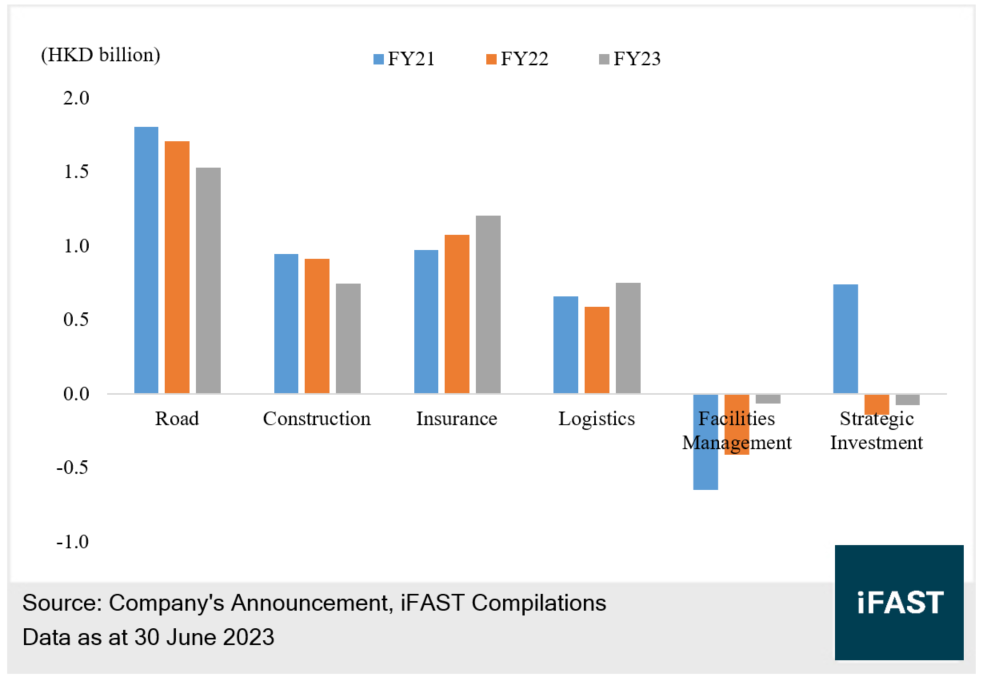
For the road segment, due to the RMB depreciation against USD and a 10% reduction in toll fees for trucks on highways newly implemented by the mainland government, NWS Holdings’s attributable operating profit for FY2023 decreased by 10% YoY, or a slight decrease of 4% YoY if excluding the impact of RMB depreciation. Overall, the performance was fair in this segment.
We expect the profit of this segment to recover, given that the relaxation of COVID-19 containment measures were fully relaxed but most of the time in the first half of FY2023 (July to December 2022) still contained the measures. Besides, the logistics industry in China is still growing, which is a positive factor in supporting the traffic flow.
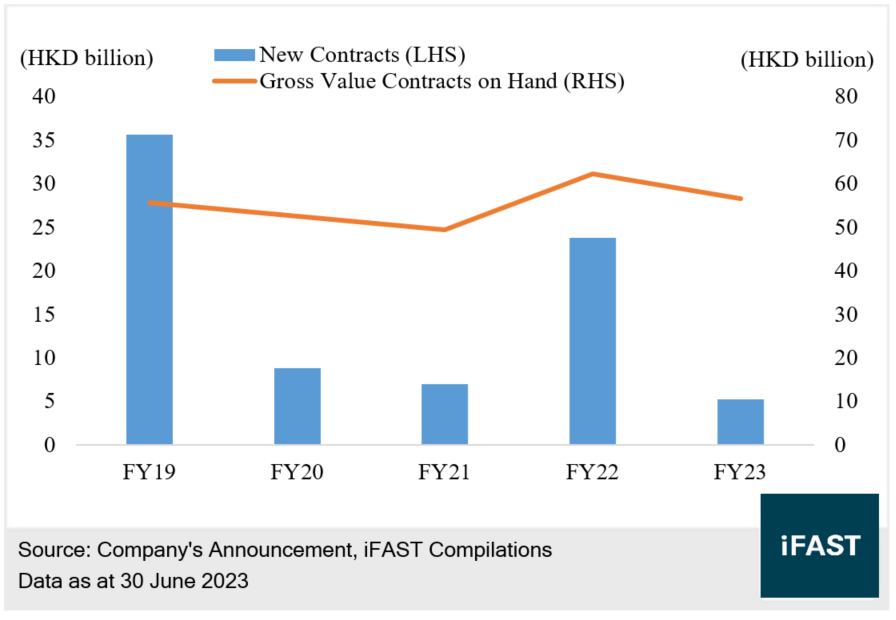
In the construction segment, the major construction company under NWS Holdings is Hip Hing Group ("Hip Hing"). It specializes in construction projects in Hong Kong. As shown in Chart 3, in FY2023, the new contracts awarded to Hip Hing dropped to HKD 5.2 billion, due to the lack of reduction in project supply in the private sector and enhanced competition in the public sector. The Hip Hing’s gross value contracts on hand in FY2023 slightly decreased by 9% to HKD 56.5 billion, which is expected to be booked in profits in the next few years. It is likely that Hip Hing will continue to benefit from the Hong Kong government's policy about increasing housing supply, such as the projects in the northern metropolitan area. The outlook remains optimistic.
In the same period, the attributable operating profit fell to HKD 750 million, mainly due to the lower profit margins of the projects to be recognized. As other contracts in hand will be booked into profits gradually, we believe that the profit margins will return to their previous levels and boost the profit of this segment.
Chart 3: Hip Hing Group’s New Contracts and Gross Value Contracts on Hand
On the insurance front, NWS Holdings engages in the insurance segment through its subsidiary, FTLife Insurance. It delivered a strong performance (see Table 1), with some growth in attributable operating profit, gross written premium and Value of New Business margin, driven by mainland tourists purchasing insurance in Hong Kong after the Hong Kong and mainland China border reopening.
Table 1: FTLife Insurance’s Operating Indicators
|
(HKD billion) |
2020 |
2021 |
2022 |
2023 |
|
Attributable Operating Profit |
0.75 |
0.97 |
1.07 |
1.20 |
|
Gross Written Premium |
1.88 |
1.96 |
1.75 |
2.57 |
|
Value of New Business |
0.48 |
0.49 |
0.52 |
0.90 |
|
Value of New Business Margin |
26% |
25% |
30% |
35% |
|
Investment Portfolio Return |
/ |
4.3% |
3.6% |
3.8% |
|
Source: Company's Announcement, iFAST Compilations Data as at 30 June 2023 |
||||
The logistics segments can be broadly categorized into three sub-divisions: Hong Kong (ATL), logistics properties in Mainland China and other logistics-related investments (including CUIRC etc.).
ATL currently has a leasable area of around 5.9 million square feet, with an occupancy rate of over 99% over the years, close to full occupancy. ALT recorded a low single-digit YoY growth in the average rentals. The overall performance is quite stable. This segment contributes over 70% profit of the entire logistics division.
The logistics properties in Mainland China contributed around 10% of segment profits. Now NWS holdings holds seven logistics properties, with a fair occupancy of over 90% if we exclude the newly established property located in Chengdu.
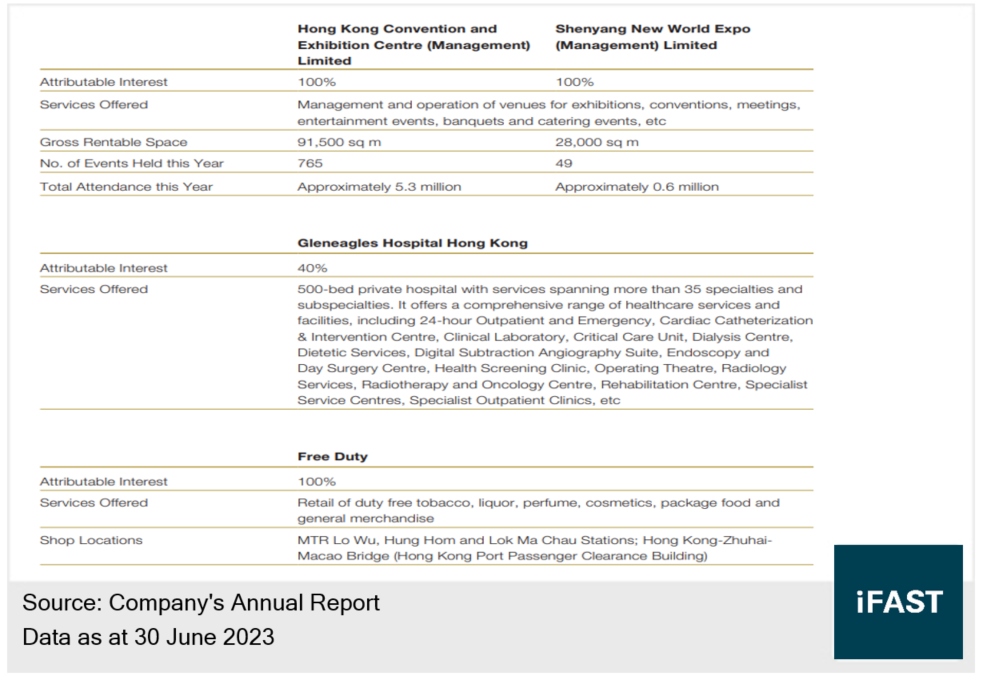
Regarding facilities management, NWS Holdings engage in the facility management of Hong Kong Convention and Exhibition Centre, Expo in Shenyang, Gleneagles Hospital Hong Kong and Free Duty (see Chart 4). Due to the relaxation of COVID-19 containment policies in Hong Kong and mainland China border reopening, the facility management of Hong Kong Convention and Free Duty already turned losses into profits, resulting in significant lower operating losses. We expect this segment will turn losses into profits in the next year.
Chart 4: NWS Holdings’s Facilities Management Introduction
In terms of strategic views, NWS Holdings keeps optimizing its asset portfolios over the past few years, including the sale of transportation and environment businesses, which were in poor operating performances, the disposal of the aircraft leasing business without the size advantage and the acquisition of roads, logistics and FTLife etc. This shows that NWS focuses on businesses with sustainable cash flow and enhances the earnings quality, in order to support its sustainable and progressive dividend policy. Thus, the Group’s cash flow and earnings have better visibility. We believe that NWS is “the company that lays golden eggs” under the Group of New World.
Decent Credit Metrics Sufficient Liquidity
As shown in Table 2, NWS Holdings’s credit metrics were decent. The net gearing ratio is low at 37.4%. The net debt to adjusted EBTIDA dropped to 2.3 times. The leverage level was good. Under the pressure from the rate hike cycle, its interest coverage ratio was still high at 5.3 times. The interest payment ability was outstanding.
The Group had an undrawn credit facility of HKD 11.4 billion. Combined with the cash position, it can cover around 90% of total debts. The overall liquidity was sufficient, with a low default risk.
Table 2: NWS Holdings’s Credit Metrics
|
June 2022 |
June 2023 |
|
|
Total Cash (HKD billion) |
13.45 |
19.26 |
|
Total Debt* (HKD billion) |
34.12 |
34.15 |
|
Adjusted EBITDA (HKD billion) |
6.79 |
6.57 |
|
Net Gearing Ratio* (%) |
47.7% |
37.4% |
|
Net Debt* / Adjusted EBITDA (times) |
3.0x |
2.3x |
|
Interest Coverage Ratio* (times) |
6.7x |
5.3x |
|
*Total debt includes perpetual debt, and interest expense includes the distribution to perps Source: Company's Announcement, iFAST Compilations Data as at 30 June 2023 |
||
In fiscal year 2023, NWS Holdings repurchased bonds at a discount through a tender offer, with the total repurchased principal amount of around USD 120 million. It helps to reduce the repayment costs. Going forward, the Group might continue to repurchase bonds in different ways, which could support the bond performance.
Investors Could Consider the 2029 Bond or Perpetual Bond
NWS Holdings does not have an issuer credit rating. Given the high visibility in the business cash flows, good leverage level and sufficient liquidity, we believe that the Group’s default risk is low.
About the perpetual bond, the Group has a high chance to redeem the bond, “NWSZF 5.750% Perpetual Corp (USD)”, on the next reset date (31 January 2024), since the coupon will be reset to over 13%, based on the current 5-year treasury yield. Even if the Group unexpectedly does not redeem the bond, the current yield after the reset will be higher than 13%, which shows a higher attractiveness.
Therefore, investors could consider the 2029 bond or perpetual bond (see Table 3). Both of them have a high attractiveness. The 2029 bond has a yield to maturity of 8.5%. If the Group redeems the perpetual bond in January 2024, investors could gain around $2.6 (including a capital gain of $1.0 and coupon of $1.6), which could be an option for short-term investment.
Table 3: NWS Holdings’s 2029 Bond and Perpetual Bond
|
Bond Name |
Tenor |
Coupon Rate |
Ask Price (Investors Buy) |
Yield To Maturity |
| NWSZF 4.250% 27Jun2029 Corp (USD) | 5.7 years |
4.25% |
81.7 |
8.5% |
| NWSZF 5.750% Perpetual Corp (USD) | Perpetual (Next coupon reset rate is 31 January 2024. On or after 31 January 2024, the Group could early redeem the bond) |
5.75% (Reset Rate = 5 year treasury |
99.0 |
6.0% (Current Yield) |
|
Source: Bondsupermart Data as at 27 October 2023 |
||||
The perpetual bond is also a senior unsecured bond. In the event of an unexpected default, the perpetual bond will have the same level of seniority on the repayment claims as the fixed-tenor bonds.
It is worth noting that we do not expect the tender offers to trigger a change of control of NWS Holdings. We mentioned that if CTFE acquires all or substantially all of NWS shares (defined as 75% or more), it is possible that the change of control could be triggered. However, given that CTFE states that CTFE would like to maintain the listing status of NWS on HKEX, indirectly shows that CTFE would not acquire substantially all of NWS shares. Therefore, the condition for triggering a change of control is not met.
Related Risks
Investors should note that the terms of the perpetual bonds are more complicated. Even if NWS Holdings suspends the coupon of the perpetual bond, it does not constitute a default on the bonds, which is riskier than the fixed-tenor bonds.
With the downward pressure on the economy of Mainland China and Hong Kong, this might affect the business performance of NWS Holdings, resulting in a weaker solvency.
NWS intends to increase its dividend payout ratio in the future. Paying more dividends might affect the Group's liquidity and be unfavorable to the credit profile.
NWS may continue to purchase assets from other companies under New World Group at a premium than the fair value, which might expose them to the risks related to connected transactions.
Conclusion
NWS Holdings mainly engages in roads, construction, insurance and logistics. The tender offers from CTFE should have a limited impact on NWS. Bond investors need not be concerned about this corporate action. The Group’s overall operating performance is decent. The cash flows and earnings have a higher visibility. NWS is a “company that lays golden eggs”.
The Group’s credit metrics are decent, with sufficient liquidity and good leverage level. Combined with the high visibility of the business cash flows, we believe that the Group’s default risk is low.
Investors could consider the 2029 bond and perpetual bond. Both of them have a certain attractiveness. Amongst these, the 2029 bond has a yield to maturity of 8.5%.
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!