AIMS APAC REIT (“AAREIT”) announced on 23 August 2021 that the company is launching unsecured and subordinated perpetual notes at an initial price guidance (“IPG”) of 5.50% under its SGD 750m Multicurrency Debt Issuance Programme dated 30 November 2018.
About the Perpetual Notes
The new AAREIT NC5 5.50% IPG perpetual notes will be issued under the issuer’s SGD 750m Multicurrency Debt Issuance Programme (“MTN programme”). The 5.50% perpetual notes will be non-callable for 5 years. If not called on its first call date, the first reset date would be in September 2026 and would reset every 5 years thereafter based on the prevailing SGD 5Y Singapore Overnight Rate Average Overnight Indexed Swap rate (“SORA-OIS”) plus the initial spread.
As per the MTN programme, the notes will be redeemed by the issuer in an event where AA REIT is or is to be terminated in accordance with the provisions of the AA REIT Trust Deed. They will not be redeemed in an event where AA REIT units are delisted from the SGX-ST.
The use of proceeds of the notes will be used for general corporate purposes such as financing general working capital, capital expenditure and investments to the group. Additionally, the notes will be used for the partial or full refinancing of existing borrowings of the group.
About AA REIT
AA REIT is an industrial real estate investment trust (“REIT”) with properties in Singapore and Australia. As of 30 June 2021, AAREIT has 28 properties in its portfolio, 26 in Singapore and 2 in Australia. AIMS Financial Group (“AIMS”) is the sole sponsor of AA REIT and is a diversified financial service and investment group headquartered in Sydney, Australia.
AA REIT is one of the smaller names in the industrial REIT space with a market capitalisation of SGD 1.06b and its property portfolio is made up of logistics and warehouse, business parks, general industrial, light industrial and hi-tech space properties.
Figure 1: Portfolio Highlights
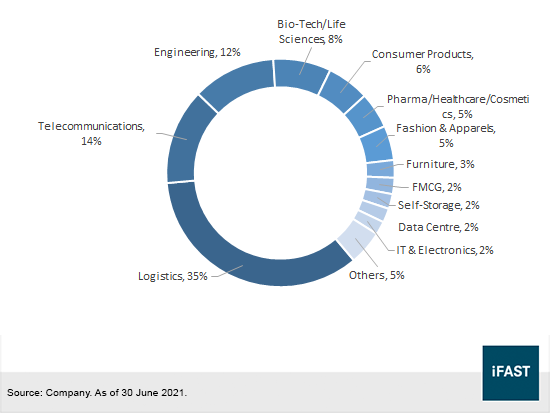
AA REIT has a well-diversified tenant base with Logistics, Telecommunications and Engineering making up more than 10% of its tenant portfolio. In 1Q22, AA REIT executed 38 new and renewal leases. Being in the industrial REIT space, demand for logistics and warehouse facilities are underpinned by of e-commerce which makes AA REIT’s properties more desirable due to the growing demand for e-commerce.
AA REIT recently completed 2 acquisitions – 7 Bulim Street and 315 Alexandra Road. 7 Bulim Street is a logistics and warehouse property and is master leased to Kintetsu World Express Pte Ltd (“KWE”), a wholly-owned subsidiary of a major Japanese freight forwarding and logistics group. The property is close to the future Tuas Mega Port and the master lease has about 3 years left, expiring on 1 January 2024 with a 5-year extension option.
AA REIT announced the proposed acquisition of 315 Alexandra Road on 27 January 2021. The property is a light industrial property situated in a city fringe location. The property is anchored for 10 years by Sime Darby Property Singapore Limited, the provider of real estate and facility services to Performance Motors Limited (“PML”), the exclusive distributor of BMW cars and motorcycles in Singapore. The property has a weighted average lease expiry (“WALE”) of 7.8 years.
Following the acquisitions, AA REIT would have a total of 28 properties in their portfolio. Portfolio occupancy rate for all the properties is 95.7% and the portfolio WALE is 3.98 years as at 30 June 2021. One key consideration for AA REIT is its high occupancy rate and long WALE. When compared to the JTC 2Q 2021 Industrial Average of 90.1%, AA REIT has a much higher portfolio occupancy rate as compared to its peers. With its higher-than-average portfolio occupancy and long WALE, we expect AA REIT to be resilient in the near future in terms of its tenant base.
1QFY22 Financial Highlights
AA REIT reported 1QFY22 (first quarter ended 30 June 2021) results on 28 July 2021 and gross revenues for 1Q22 amounted to SGD 31.8 m for the period ending 30 June 2021. Gross revenues increased 16.8% year-over-year (“Y-o-Y”). Net Property Income increased by 23.9% Y-o-Y to SGD 23.1m in 1QFY22 as compared to SGD 18.6m in 1QFY21. The increase in gross revenue was due to contributions by 7 Bulim Street and higher rental reversion from 20 Gul Way and 8 & 10 Pandan Crescent properties.
Credit Profile of AIMS REIT
As of 30 June 2021, AA REIT has cash balances of SGD 11.0m and undrawn committed facilities of SGD 126.3m. AA REIT tapped into commitments of SGD 220.0m and AUD 100.0m to refinance its secured debt facilities of SGD 245.0m and AUD 15.0m, which mature in 2021 and 2022 respectively.
Figure 2: Pro-forma debt maturity profile of AA REIT
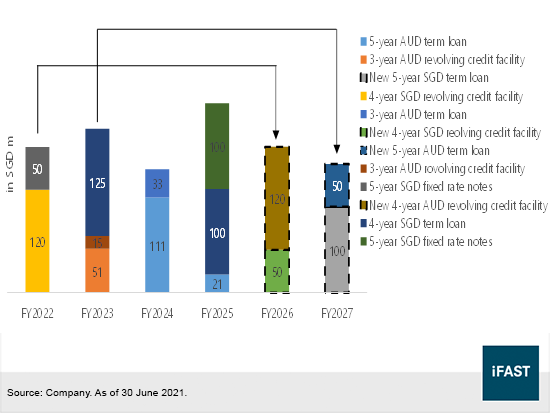
From Figure 2, the SGD 120 m 4-year revolving credit facility maturing in FY2022 is expected to be refinanced to FY2026 while the SGD 125 m 4-year SGD term loan maturing in FY2023 and the SGD 15m 3-year AUD revolving credit facility may be refinanced to FY2027. By refinancing the secured debt facilities, AA REIT will have sufficient undrawn committed facilities to repay the fixed rate notes of SGD 50m due in March 2022.
One key risks that investors have to consider is that AA REIT relies heavily on bank financing and credit revolving facilities for its financing as it has only SGD 11.0m in cash. That said, leverage for the company is relatively sound with aggregate leverage ratio of 34.3%, within the aggregate leverage limit of 50% set by MAS.
Additionally, AA REIT’s interest coverage ratio (calculated by dividing the trailing 12 months earnings before interest, tax, depreciation and amortisation - excluding effects of any fair value changes of derivatives and investment properties, and foreign exchange translation by the trailing 12 months interest expense and borrowing-related fees) was 4.3x, above the MAS minimum requirement of 2.5x. The management has said they will remain disciplined and prudent in capital management and has shown this through its early intention to refinance its fixed rate notes due in March 2022.
Relative Valuation
Figure 3: Relative valuation among SGD perpetual notes of REIT issuers
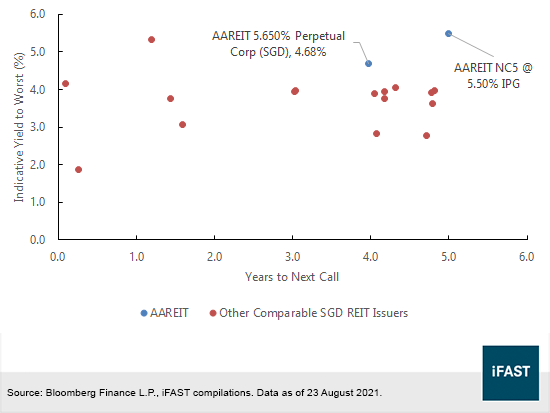
We think that the AAREIT NC5 perpetual notes is fairly priced at 5.50% IPG. It has one of the highest yield among perpetual notes issued by REIT peers. Additionally, the notes has a credit spread of 479 basis points above the prevailing 5Y SORA-OIS. We feel that the pricing is fair compared to the AAREIT 5.650% Perpetual Corp (SGD), which is trading at an indicative yield-to-worst of 4.68%. The AAREIT 5.65% perps are callable in August 2025 and the yield pickup of 82 basis points adequately compensates for the 1-year tenor difference.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!