- Strong
economic activity in the US led to the repricing (higher) of longer-end yields
on the USTs, causing mark-to-market losses for bonds across the month.
- Expectations of rate cuts
have fallen off significantly since the start of the year, to 1 or 2 rate cuts
for 2024.
- We hold our preference for quality issuers with a short-duration tilt.
In April, news of strong economic activity continues to support higher yields, weighing on fixed income markets. Across the month, Global Investment-Grade (“IG”) bonds (measured by Bloomberg Barclays Global Aggregate Index) and Asian IG bonds (measured by Bloomberg Asia USD IG Bond Index) fell by -2.5% and -1.6% respectively. Locally, we see the Singapore bonds market (measured by iBoxx SGD Bond Index) falling by -2.2% for April (returns are in local currency).
US headline inflation continue to record an upward trend, with the figure rising from 3.1% year-on-year (“YoY”) in Jan, to 3.2% in Feb, and further jumping to 3.5% in Mar (though it did soften slightly to the recent 3.4% figure in Apr). Similarly, core inflation proved to be sticky over the same period – hovering at 3.8% YoY in Feb and March – and still far from the 2% target of the Federal Reserve. Prices in the US have stayed high owing to contributions coming from oil and gas, as well as shelter inflation.
US CPI was merely one of the numerous indicators that reflected an economy much more resilient than expected. Besides inflation, the US labour market remains relatively tight, with the unemployment rate staying low. As a result, the market yet again adjusted its expectations of rate cuts throughout 2024 – to only 1 to 2 rate cuts (Chart 1).
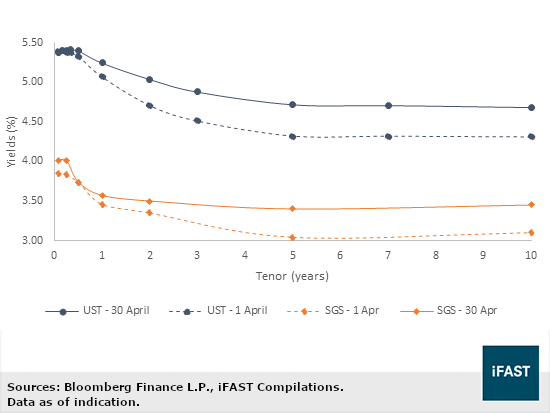
Effects arising from the calibration of rate cut expectations inevitably impacted US Treasury yields, leading to major repricing (higher) in April itself. The yields on longer tenor treasuries saw larger movements, with 5-year and 10-year USTs rising by close to 40 basis points (Chart 2). Closer to home, we see the impact extending to the Singapore Government Securities (“SGS”), with the longer-ends similarly seeing greater increments.
The upward shift in the treasury yields had been a key reason for the poor performances of the fixed income markets as mark-to-market adjustment in bond prices led to negative returns. This was particularly evident in IG bonds due to the slightly longer duration observed in the benchmark indices. Higher coupons were also insufficient for the High Yield (“HY”) bonds segments to offset negative returns as both Global HY (measured by Bloomberg Barclays Global High Yield Index) and Asian HY (measured by Bloomberg Barclays Asia USD High Yield Bond Index) fell by -0.8% and -0.6% respectively.
Chart 1
Market expectations of rate cuts
(based on Fed Funds Rate futures)
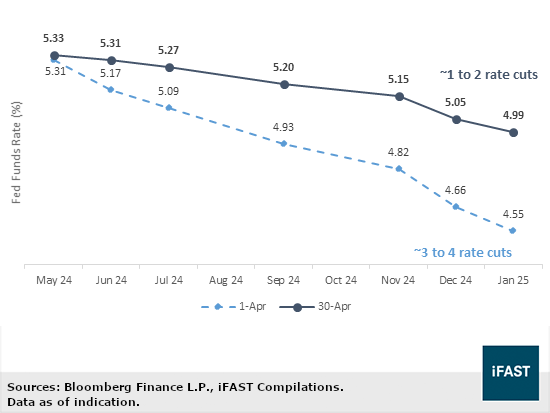
Chart 2
Yields on the UST and SGS across
the month of April
The higher-for-longer interest rates environment continues to underscore a need for quality issuers which are less vulnerable to financial stress, exerted from a prolonged environment of higher cost of capital. We favour IG over HY issuers, particularly those with a shorter duration exposure.
Since the beginning of 2024, we have seen how longer-end yields have adjusted upwards repeatedly – illustrating the need to consider duration risk associated with longer tenor options. Looking ahead, we see room for longer-end yields to further increase if economic growth improves and/or inflationary pressure strengthens. Meanwhile, we also expect shorter-end yields to remain well-supported by the higher-for-longer rates environment.
On Bond Express, we saw two new additions to the platform, with the OCBC 2030 Tier 2 paper being one of the rare attractive offerings from this strong Singapore bank. Top traded bonds in the previous month had mostly been SGD papers, in which we saw quite some interest in ESRCAY’s various offerings.
Table 1
New Additions to Bond Express
|
Bond |
Issuer |
Article |
|
Oversea-Chinese Banking Corporation Limited |
Idea of the Week – Why you should consider this OCBC USD bond yielding around 6% |
|
|
Olam International Limited |
Idea of the Week: Why we like this 2026 bond with over 5% yield |
Table 2
Top traded bonds on Bond Express in April
|
Issue |
Issuer |
Ask Price |
Yield to Call/Maturity |
Years to Call/Maturity |
|
ESR Group Limited |
100.45 |
- / 4.54% |
- / 0.78 |
|
|
ESR Group Limited |
99.25 |
6.08% / - |
1.80 / - |
|
|
Olam Group Ltd |
98.35 |
- / 4.98% |
- / 1.78 |
|
|
Thomson Medical Group Limited |
101.25 |
-* / 5.15% |
0.04 / 4.04 |
|
|
AIMS APAC REIT |
100.00 |
- / 5.36% |
2.30 / - |
|
|
Sources: Bloomberg Finance L.P., Bondsupermart, iFAST Compilations. Data as of 16 May 2024. *We believe the TMGSP 2028 paper is priced to maturity, i.e. very unlikely for them to exercise the call option on the paper and therefore the yield to call will be inaccurately represented. |
||||
AIMS APAC REIT (“AAREIT”)
AAREIT focuses on a diversified portfolio of high-quality income-producing logistics, business parks and industrial real estate across the Asia Pacific region, currently with assets based in Singapore and Australia. As of 31 March 2024, it holds a total of 28 properties with a total portfolio value of SGD 2.16b.
For the fiscal year ended 31 March 2024 (“FY24”), AAREIT saw growth in both gross revenue and net property income by +5.9% and +6.9% YoY respectively. The overall distribution to unitholders has increased by +3.8% YoY as a result, although the distribution per unit has fallen by -5.9% owing to the equity fundraising in June last year. High portfolio occupancy and strong rental reversion have contributed to the performance over the period, with portfolio occupancy at 97.8% and rental reversion at 24.3%. Most importantly in FY23, AAREIT sees master lease renewals with two key tenants – KWE at 7 Bulim Street and Aalst Chocolate at 26 Tuas Avenue 7.
ESR Group Limited (“ESR”)
ESR has seen a shift from its previous three-pronged approach towards its business (investment, development and management of real estate properties) and increasingly focuses on fund management to derive fee income. Fund management EBITDA now accounts for nearly 60% of ESR’s total segmental EBITDA, from 21% since its 2019 IPO. It grew by 8.9% YoY in FY23, with a remarkable CAGR of 57% since 2020.
We see a moderation in ESR’s credit profile, owing to lesser cash and more debt for funding new projects and developments. However, with its planned optimization of the balance sheet (approximately USD 2.1b of net proceeds) and using the majority of the proceeds to pay down debt, its credit profile is expected to rebound from here.
For more information on ESR’s FY23 results, refer to our coverage here - Idea of the Week: More attractive than SG T-bills? Look no further!
Olam Group Limited (“Olam”)
Olam Group Limited (“Olam”) is a leading food and agri-business company providing food, ingredients, feed, and fibre to over 22,000 customers globally. The Group has operations in farming, origination, processing, and distribution spanning over 60 countries. Olam reports revenue in three main operating groups – 1) Olam Agri, 2) ofi and 3) the remaining Olam Group.
For the full year ended 31 December 2023 (“FY23”), Olam reported a 12.1% YoY decline in revenue, although sales volume had risen by 2.9% YoY. EBIT went up by 10.1% YoY, primarily driven by improved earnings from the major operating groups. However, PATMI fell by -55.7% YoY owing to greater interest expense and lower share profit contribution from Olam Agri, after a 35.4% stake sale to Saudi Agriculture and Livestock Investment Company, and also higher exceptional losses which included organization costs. We have expectations for Olam’s earnings outlook to recover gradually, on the backdrop of easing profit headwinds and growth opportunities.
Overall, Olam’s credit profile remains generally decent, despite a deterioration of debt ratios across the year. While, the Group’s coverage ratios also fell as interest expenses rose, we expect interest expense to face minimal upward pressure moving forward as the majority of rate hikes are likely to have passed. We see room for coverage ratios to improve if Olam continues to record earnings growth.
For our full coverage of Olam’s FY23 results, please refer to the article here - Idea of the week: Why we like this 2026 bond with over 5% yield
Thomson Medical Group (“TMG”)
TMG is one of the leading listed healthcare players in the Southeast Asian region, with operations in Singapore and Malaysia, while it recently expanded into Vietnam. The latest acquisition, Far East Medical Vietnam Limited, sees expansion into Vietnam’s growing market and has been one of Southeast Asia’s largest healthcare acquisitions since 2020.
For the six months ended 31 December 2023 (“1H24”), TMG experienced a drop in performance – with revenue and profit after tax falling by -8.6% and -79.7% year-on-year (“YoY”) respectively. The lower revenue was largely due to the slower operations in Singapore, after the completion of short-term service contracts relating to COVID-19. For the profit after tax, the significant decline was a result of lower revenue, higher operating expenses and higher finance costs.
We see growth opportunities in its operations in Malaysia, while the acquisition in Vietnam has yet to reflect the contributions on the financial statements. We believe TMG’s operations overseas will contribute increasingly in the coming years, especially with the continued expansion in bed capacity for its hospital in Malaysia, alongside a planned development in Iskandar, Johor Bahru.
Lastly, the acquisition has resulted in a moderation in TMG’s credit profile, owing to the increase in net debt. However, we expect the increase in future earnings (from recognizing its Vietnam hospital operations) to compensate for the increase in interest expenses, while allowing TMG to accumulate cash for debt repayment.
About Bond Express
Bond Express is an initiative that allows you to trade a selected list of wholesale bonds with firm executable pricing and volumes, but more importantly, in lot sizes from as little as USD 5,000 for USD-denominated wholesale bonds (or SGD 5,000, USD 5,000, MYR 5,000 for their respective denominated bonds). Click here to find out more about Bond Express.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OCBCSP 1.832% 10Sep2030 Corp (USD), OLAMSP 4.000% 24Feb2026 Corp (SGD), ESRCAY 5.100% 26Feb2025 Corp (SGD), ESRCAY 5.650% Perpetual Corp (SGD), OLAMSP 4.000% 24Feb2026 Corp (SGD), TMGSP 5.500% 31May2028 Corp (SGD), AAREIT 5.375% Perpetual Corp (SGD), and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!