- Most fixed income segments saw negative returns in August so far, with the Global IG space declining -1.9% MTD.
- The UST yield curve generally bear-steepened in the first half of Aug. This was a result of multiple factors including the Treasury Department’s announcement that it would offer more-than-expected Treasuries for auction.
- We highlight some of our top-traded bonds on Bond Express, covering issuers like Thomson Medical Group, ESR Group Limited, and Frasers Property Limited. We also take a look at some US T-Bills which were recently added to Bond Express.
While July was generally a positive month for fixed income, the first half of August has not been as encouraging. Most fixed income segments saw negative returns in August so far, with the Global IG bond space (gauged by the Bloomberg Global Aggregate Index) declining -1.9% MTD (as of 14 Aug) (Chart 1).
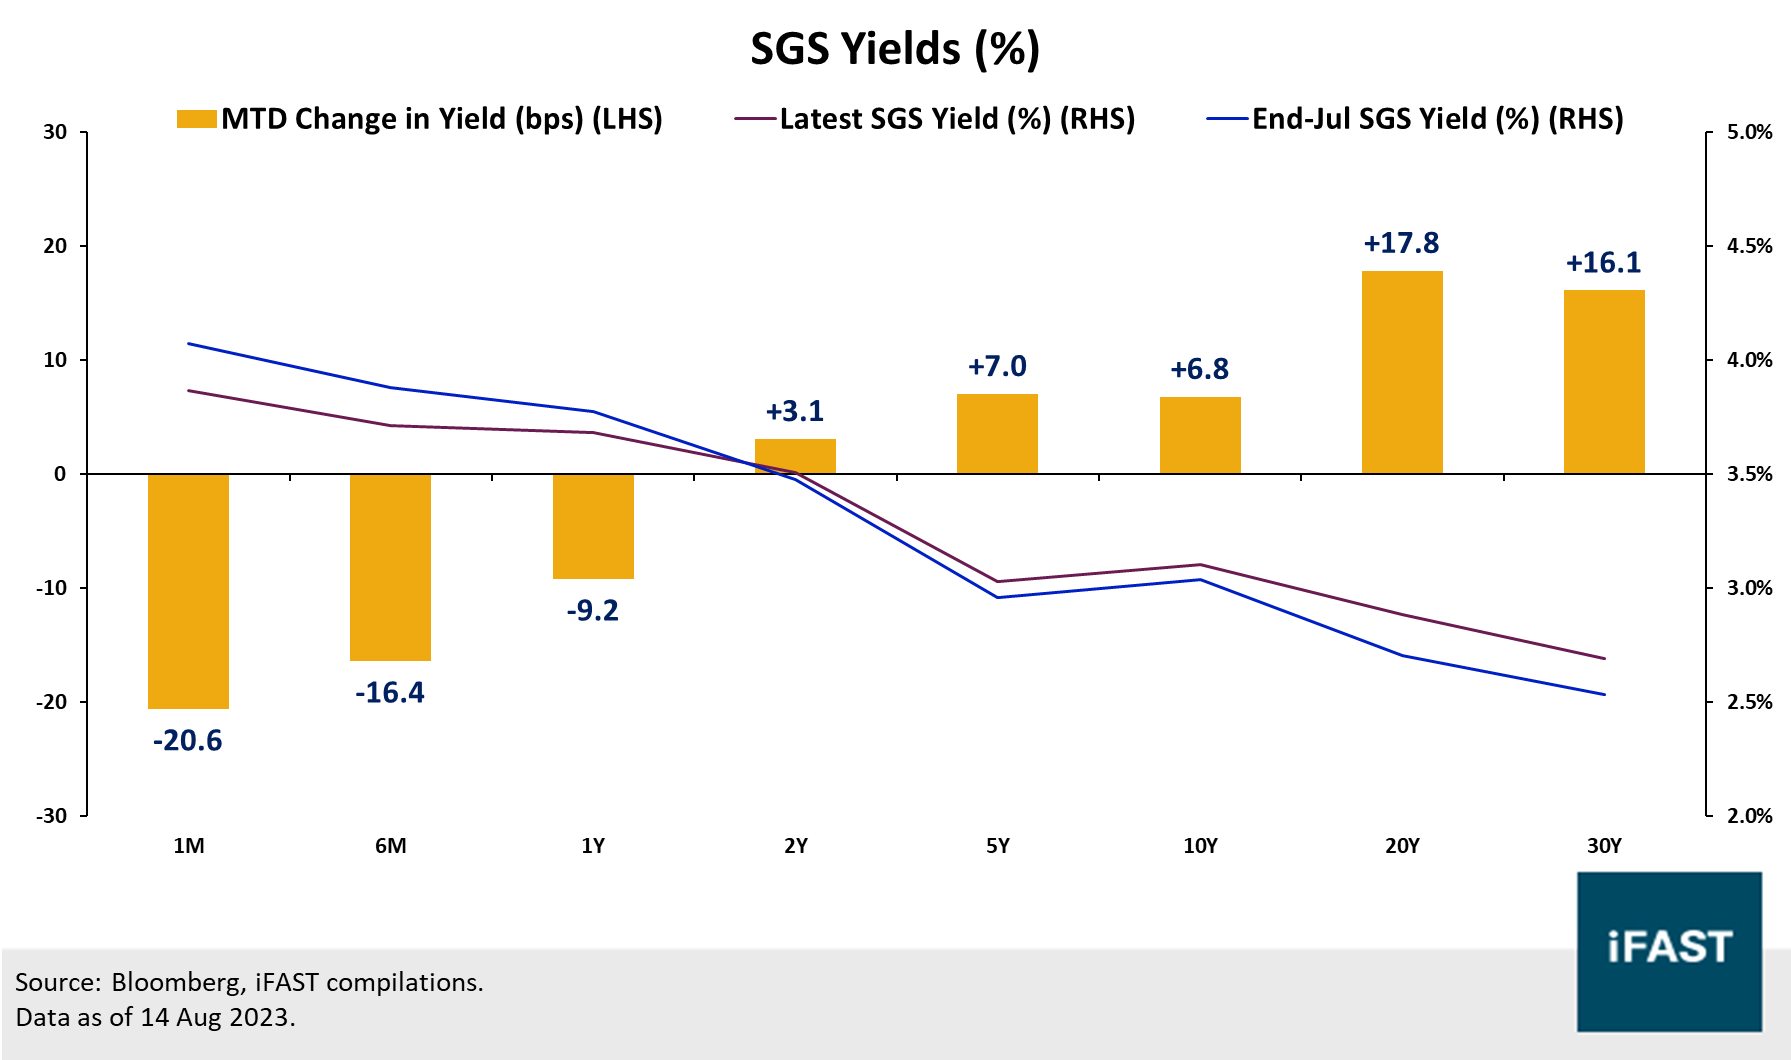
Across the curve, we generally observed a bear steepening particularly on the longer end, for both US as well as SG sovereigns (Charts 2 and 3). The increase in longer-term UST yields was primarily due to the Treasury Department’s latest refunding plan, where it announced the offering of USD 103b worth of Treasuries for auction, higher than consensus expectations. A significant portion of the auction was on longer-dated treasuries. This news coupled with the recent Fitch downgrade helped shine the spotlight on the US’s rising borrowing requirements, ultimately pushing longer-end yields higher.
Chart 1: Most fixed income segments saw negative returns with Global IG delivering -1.9% MTD
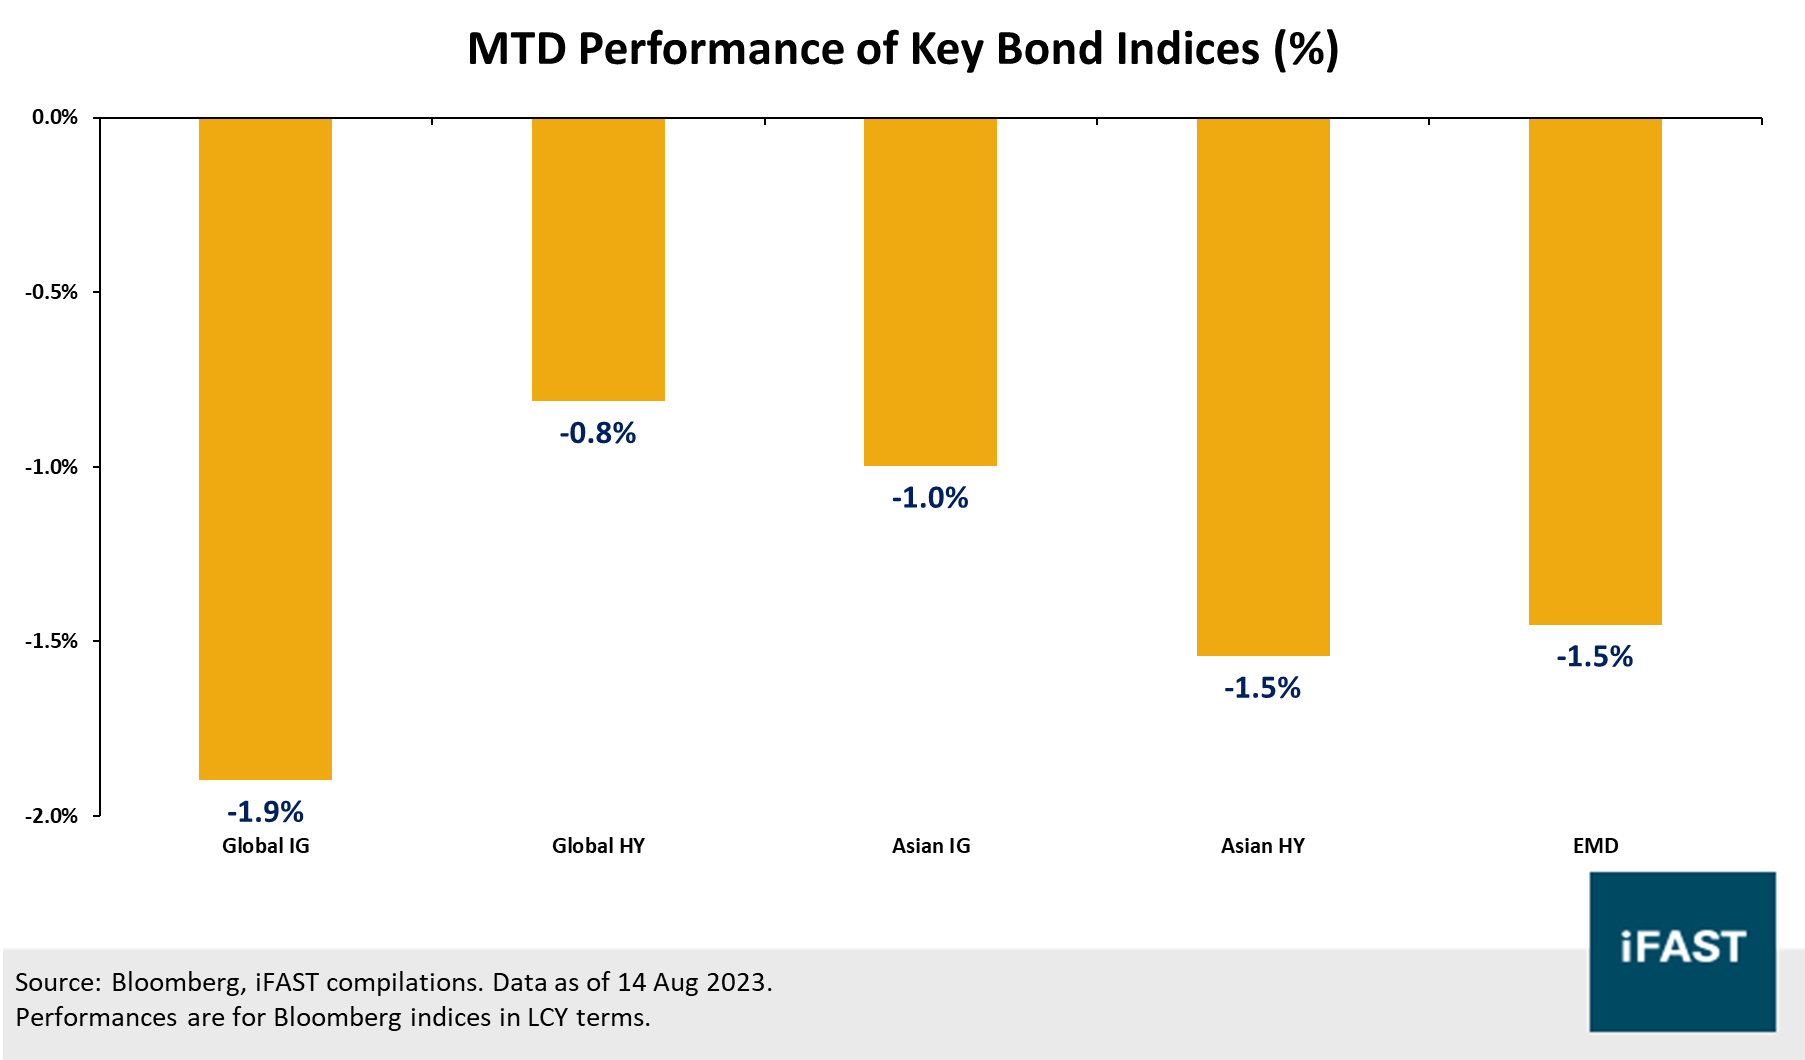
Chart 2: UST yield curve bear-steepened in the first half of Aug
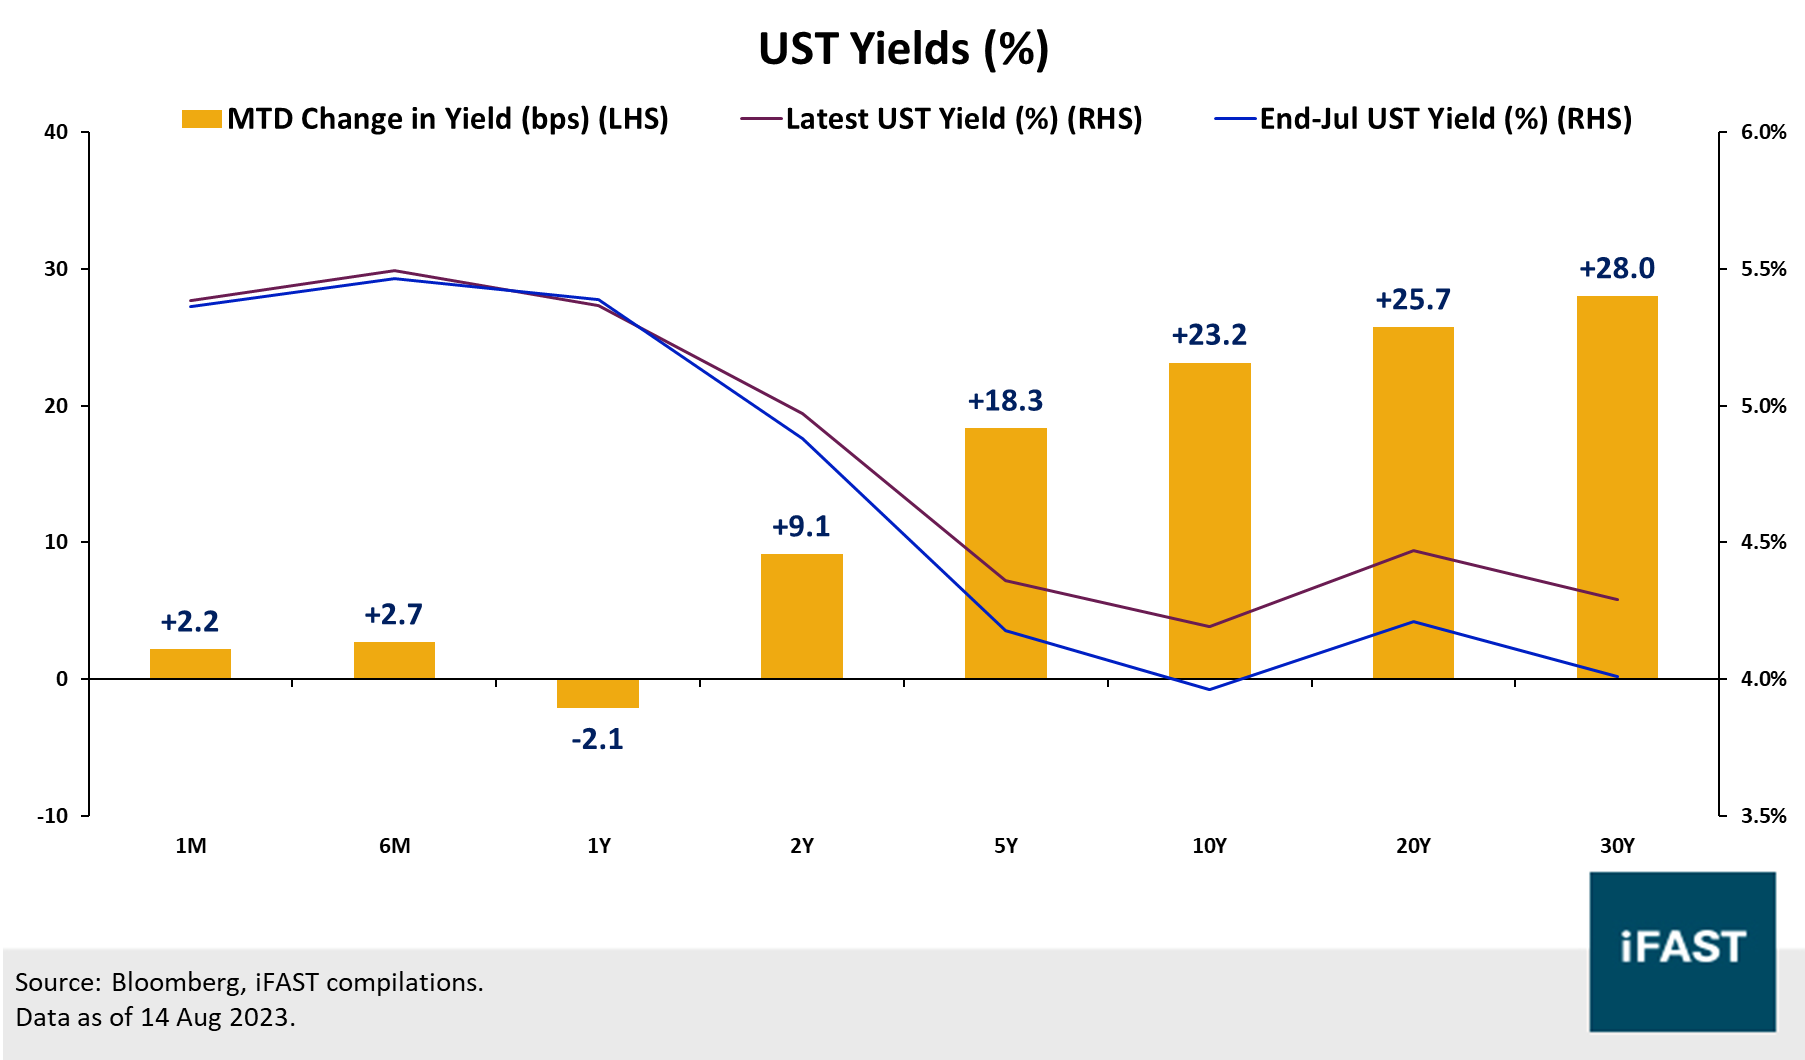
Chart 3: SGS yield curve similarly bear-steepened in first-half of Aug
Economic data in the US was relatively mixed. ISM Manufacturing and Services PMI figures for Jul both came in below consensus expectations, with Manufacturing PMI, in particular, coming in at 46.4, deep within contractionary territory. As for inflation, headline CPI inflation climbed from 3.0% YoY in Jun to 3.2% in Jul, while core CPI inflation decelerated from 4.8% to 4.7% in the same period – these figures remain well above the Fed’s 2% target and highlight the persistence of inflation thus far.
Singapore narrowly avoided a recession with a 0.1% QoQ GDP growth in 2Q23 (1Q23: -0.4%). On a YoY basis, 2Q23 GDP grew 0.5% below consensus expectations of 0.8%, also marking a slowdown from the previous quarter (1Q: 0.7%). MTI also narrowed its FY23 GDP forecast from 0.5% - 2.5% to 0.5% - 1.5% and highlighted several downside risks in the global economy, including more persistent-than-expected inflation in advanced economies, as well as geopolitical tensions.
With economic data continuing to point towards a global growth slowdown, credit spreads generally widened across the board as of 11 Aug. Global IG spreads widened by about +2.8 bps (from about 41 bps to 43 bps [Bloomberg Global Aggregate Index]). Global HY spreads also widened by about +3.1 bps (from about 292 bps to 295 bps [Bloomberg Global High Yield Index]).
In July, we generally saw more trades in SGD bonds compared to USD bonds (Table 1). Thomson Medical Group’s TMGSP 5.500% 31May2028 Corp (SGD) was among the top-traded bonds on Bond Express (“BE”). Another notable issuer was ESR Group, which has two bonds within our top-traded list: ESRCAY 5.100% 26Feb2025 Corp (SGD) and ESRCAY 5.650% Perpetual Corp (SGD). Another top-traded bond was Frasers Property’s FPLSP 4.980% Perpetual Corp (SGD).
BE also saw several new additions in July, all within the UST space (Table 2). These were generally shorter-tenor US Treasury Bills, which may have seen solid demand on the back of decent nominal yields (over 5% at the time of writing).
Table 1: Top-traded bonds on SG Bond Express in July
| Bond Name | Maturity / Next Call Date (Years to Maturity / Next Call) |
Ask Price | Current Yield (%) | Yield to Worst (%) |
| TMGSP 5.500% 31May2028 Corp (SGD) | 31 May 2024 (0.8) |
101.300 | 5.429% | 5.188% |
| ESRCAY 5.100% 26Feb2025 Corp (SGD) |
26 Feb 2025 (1.5) |
100.250 | 5.087% | 4.927% |
| ESRCAY 5.650% Perpetual Corp (SGD) |
02 Mar 2026 (2.5) |
98.050 | 5.762% | 6.481% |
| FPLSP 4.980% Perpetual Corp (SGD) |
11 Apr 2024 (0.7) |
99.580 | 5.001% | 5.621% |
| Source: Bloomberg, Bondsupermart, iFAST compilations. Data as of 14 Aug 2023. | ||||
Table 2: New additions to Bond Express
| Bond Name | Maturity / Next Call Date (Years to Maturity / Next Call) |
Ask Price | Current Yield (%) | Yield to Worst (%) |
| T 2.250% 31Mar2024 Govt (USD) |
31 Mar 2024 (0.6) |
98.130 | 2.293% | 5.351% |
| T 2.500% 31May2024 Govt (USD) |
31 May 2024 (0.8) |
97.806 | 2.556% | 5.380% |
| T 2.875% 31Oct2023 Govt (USD) |
31 Oct 2023 (0.2) |
99.521 | 2.889% | 5.205% |
| Source: Bloomberg, Bondsupermart, iFAST compilations. Data as of 14 Aug 2023. | ||||
Thomson Medical Group
Thomson Medical Group (“TMG”) is an integrated private healthcare provider operating in Singapore and Malaysia. Its TMGSP 5.500% 31May2028 Corp (SGD) bonds were recently issued in May 2023 and have now been within our list of top-traded bonds for 3 months in a row.
TMG saw a solid financial performance for 1H23 (period ended 31 Dec 2022). Group revenue and EBITDA grew by double-digits YoY, attributed to increased patient load, higher intensity of cases, and ongoing public-private projects in Singapore. TMG will report its FY23 results in end-Aug, and investors will want to see if TMG can sustain this positive momentum, especially after seeing record profits previously in FY22.
TMG also recently announced a USD 381.4m acquisition of Vietnam’s FV Hospital in Jul 2023, which would mark the country’s biggest healthcare transaction to date, and Southeast Asia’s largest healthcare acquisition since 2020.
For coverage into TMGSP 5.500% 31May2028 Corp (SGD), check out our article here - Thomson Medical announces SGD 5NC1 senior unsecured bonds at 5.75% IPG.
ESR Group Limited
ESR Group Limited (“ESR”) is a leading real estate manager within Asia Pacific focusing on new economy properties and logistics spaces.
ESR’s revenues grew by 128% to USD 821m in FY22 (period ended 31 Dec 2022) following its recent acquisition of ARA Asset Management, while organic revenues grew by 7% excluding this acquisition. ESR continued to experience strong growth due to continued demand for new economy properties, with e-commerce and third-party logistics making up 76% of new leases signed in FY22.
We think demand for e-commerce continues to outpace supply, especially as supply thus far appears to be insufficient for the growing industry. We think ESR can leverage ongoing trends to continue growing, especially within the new economy segment.
For a credit update on ESR and their ESRCAY 5.100% 26Feb2025 Corp (SGD), check out our article here - Idea of the Week: E-commerce demand will benefit ESR Group.
Frasers Property Limited
Frasers Property Limited (“FPL”) is a leading diversified real estate issuer headquartered in Singapore, with a diverse portfolio of properties primarily in Asia-Pacific and Europe.
FPL delivered a robust set of results in 1H23 (period ended 31 Mar 2023), with first-half revenues, adjusted profit before interest and taxation, as well as attributable profit all growing by double-digits YoY. Looking ahead, we have highlighted three segments that could help FPL remain resilient:
- Industrial & Logistics: We like FPL’s healthy pipeline moving ahead, spanning across many markets including Australia, Vietnam, and Europe. Management has recently highlighted strong leasing activity and robust occupier demand within this segment (from its 3Q23 business update).
- Retail: This segment mainly comprises Singapore retail assets, which we think could remain resilient alongside the broader Singapore economy. FPL has also strengthened its retail portfolio recently with its recent acquisition of a 50% stake in NEX mall.
- Hospitality: We think this segment could be a growth driver as it benefits from a continued easing of border restrictions. Management has recently guided China’s outbound tourism to recover gradually to pre-COVID levels by early 2024.
We believe FPL continues to have a solid credit profile. While net debt levels have increased (partly due to the aforementioned NEX acquisition), we believe it retains enough liquidity (SGD 2.9b in cash as of 1H23) and will be able to repay or refinance its upcoming debt.
For a more in-depth credit update on FPL, check out our article here - Idea of the Week: One of the largest diversified real estate issuers with an attractive retail bond.
US Treasury Bills
US Treasury Bills (“US T-Bills”) continue to see strong demand on SG Bond Express, particularly with nominal yields (in USD terms) looking fairly attractive. For instance, the three new additions of US T-Bills currently trade at yields of between 5.2% to 5.4%, with maturities all below 1 year.
We believe that inflation within the US may remain persistently elevated for some time above the Fed’s 2% target, and this may translate into a higher-for-longer rates environment as well. This has pushed nominal bond yields to their highest levels since 2007, providing investors with an opportunity to capture yields from short-term US Treasuries.
For our views on the USD bond market in 2H23, check out our article here - A quick guide to 2H 2023 USD bond market.
About Bond Express
Bond Express is an initiative that allows you to trade a selected list of wholesale bonds with firm executable pricing and volumes, but more importantly, in lot sizes from as little as USD 5,000 for USD-denominated wholesale bonds (or SGD 5,000, USD 5,000, MYR 5,000 for their respective denominated bonds). Click here to find out more about Bond Express.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in TMGSP 5.500% 31May2028 Corp (SGD), ESRCAY 5.100% 26Feb2025 Corp (SGD), ESRCAY 5.650% Perpetual Corp (SGD), FPLSP 4.980% Perpetual Corp (SGD), T 2.250% 31Mar2024 Govt (USD), T 2.500% 31May2024 Govt (USD), T 2.875% 31Oct2023 Govt (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!