


Important Events
· Last week, the Federal Reserve Board released details on the hypothetical scenarios for the 2021 bank stress tests. Lenders will be tested under a hypothetical recession scenario that begins in the first quarter of 2021 with weakening market conditions in the commercial real estate and corporate debt markets. In the “severely adverse” scenario, the unemployment rate is projected to increase by 4 percentage points to reach a peak of 10.75% in the third quarter of 2022, while equity prices fall by 55 percent. The scenarios are not the central bank’s forecasts but are part of the stress test process to model the financial strength of large US banks.
· Donald Trump was once again acquitted in his second impeachment trial in as many years. The US Senate voted 57-43 in favour of convicting the former president, short of the 67 votes needed to convict the former President on a charge of inciting the mob which stormed the US Capitol on 6 Jan 21. This will allow Trump to campaign for a second term in 2024. However, Senate Republican Leader Mitch McConnell suggested that Trump could still face criminal prosecution for his acts.
Asian High Yield Bond Index
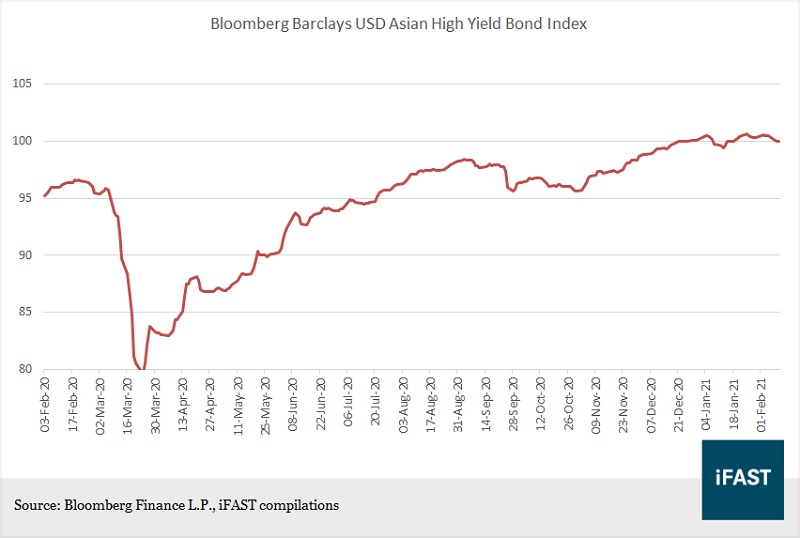
· The performance of the Barclays USD Asia High Yield Bond Index decreased slightly by 0.31% during the week ended 12 Feb 21. Highly leveraged real estate developers like China Fortune Land Development Co. Ltd. and Greenland Global Investment Ltd. saw their bonds prices dropped dramatically.
· Top weekly gainers include bonds from Energy Resources LLC, Vedanta Resources Ltd. and Lippo Karawaci. The LPKRIJ 6.750% 31Oct2026 Corp (USD) gained 2.93% last week.
· Bonds of China Fortune Land Development Co. Ltd. (“CFLD”) continued to drop with their 2025 bonds declining from 44.95 to 31.86 over the week. Other Chinese real estate names that saw huge declines of more than 10% are Caiyun International Investment Ltd., Hejun Shunze Investment Co. Ltd., and Greenland Global Investment Ltd.
Interest Rates and Currencies
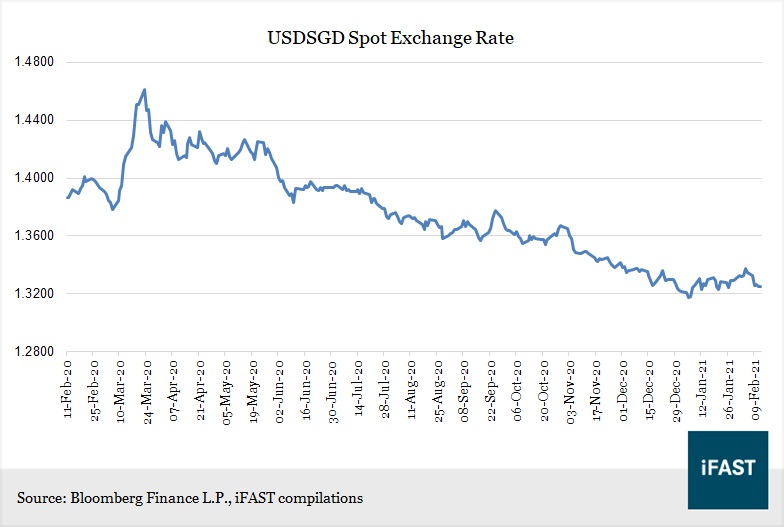
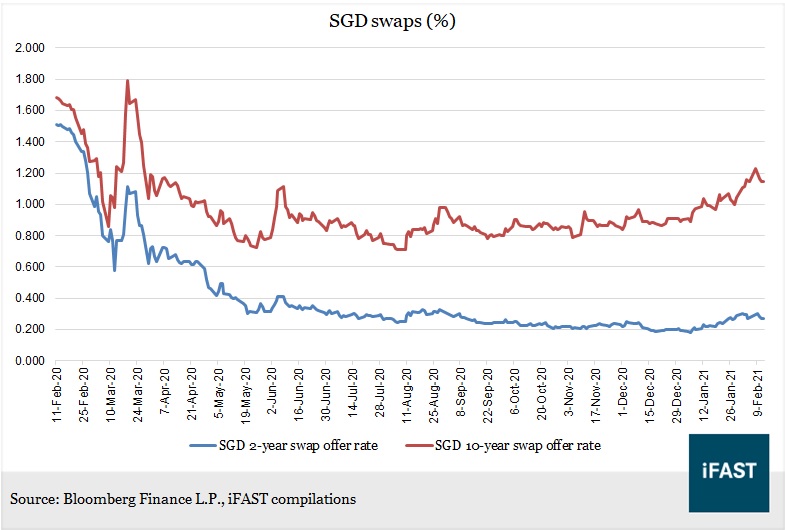
· The US dollar remained weak as the USDSGD depreciated by 0.7% to 1.3251 for the week ended 12 Feb 2021. The two-year SGD Swap Offer Rate (“SOR”) decreased slightly to 0.27% while the ten-year SOR remained at an elevated level of 1.15%.
· The yield of 2-year US Treasuries (“UST”) climbed to 0.11% while the 10-year UST yield gained by 4.5 basis points (“bps”) as inflation fears continued to rise.
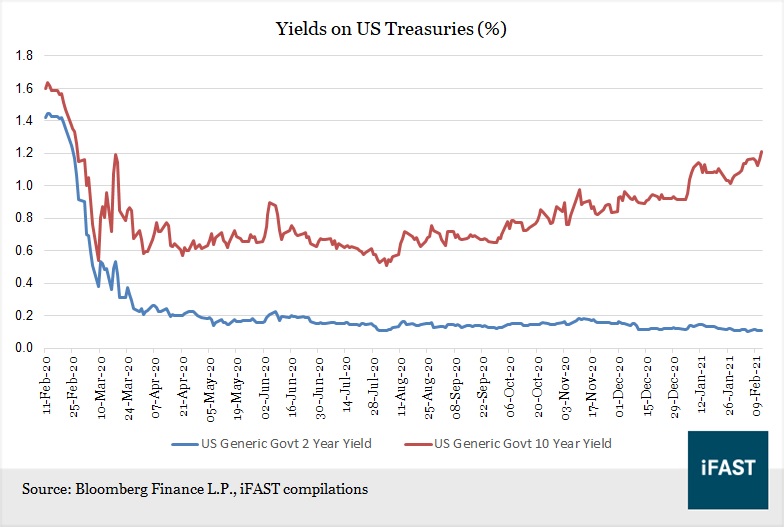
As investors grow increasingly concerned over rising inflation, inflation data in January showed that US CPI ex food and energy rose 1.4% YoY and remain unchanged MoM on a seasonally adjusted basis. Food and beverages rose the most, increasing by 3.7% YoY while prices of services and housing increased by 1.4% and 1.8% YoY respectively.
Corporate Updates and New Issues
· On Tuesday, mm2 Asia Ltd. announced they received an in-principle approval from the Singapore Exchange on 2 Feb 21 for its proposed rights issue. The proposal involves the issuance of one Rights Share for every existing share held, at S$0.047 for each Rights Share. The proposed rights issue is pending approval by shareholders at an extraordinary general meeting, the date of which is yet to be determined.
UOB Kay Hian Private Limited is the manager and underwriter for the rights issue. Up to 1.16 billion rights shares will be issued and the proceeds of about S$54.65m will be used for the repayment of the MMASIA 7.000% 27Apr2021 Corp (SGD) and general working capital, and operations of the group.
· Singapore Airlines Limited (“SIA”) announced on Tuesday that they it has reached agreements with Airbus and Boeing to revise its aircraft delivery schedule. SIA will be able to defer more than S$4 billion of capital expenditure between FY20/21 and FY22/23 to later years.
· Pacific Radiance Ltd. updated on Tuesday that they are terminating the proposed acquisition of the entire issued and paid-up capital of Allianz Marine and Logistics Services Holding Ltd (“AMLS”) from the Vendors. AMLS is an Abu Dhabi-headquartered holding company principally involved in the business of integrated offshore logistics solutions and supply-based operations to the offshore oil and gas and construction sectors.
Separately, the company announced that it had commenced a consent solicitation exercise to amend the conditions of its S$100m 4.3% 2020 notes, so as to provide for the redemption of the notes by issuing new shares and perpetual securities to noteholders. Additionally, the company is seeking the waiver of certain conditions such as the non-payment of the notes and changes to the Trust Deed.
· In an uploaded press release from FCOT Treasury Pte. Ltd, Moody’s affirmed Frasers Commercial Trust’s (FCOT) Baa2 issuer rating on Tuesday. It also affirmed FCOT Treasury Pte. Ltd.’s Baa2 backed senior unsecured debt ratings and the (P)Baa2 rating on its backed senior unsecured medium-term note (MTN) programme. Moody’s has also changed the outlook on all ratings to stable from negative, reflecting an improvement in FCOT’s earnings and Moody’s expectations that its credit metrics will remain appropriately positioned for its investment grade ratings over the next 12-18 months.
FCOT’s leverage, measured by net debt/EBITDA, improved to around 6.4x for FY20 ending 30 Sep 20, from 8.6x for FY19. The reduction in leverage was driven by higher earnings following lease commencement by Google in 2020 and higher contribution from Farnborough Business Park. Moody’s expects FCOT’s leverage to hover around 6.5x-7.0x for the next 12-18 months.
As of 30 Sep 20, FCOT had cash and cash equivalents of S$52m while having S$256m of debt maturing in the next year. However, Moody’s expects refinancing risk to be mitigated by the trust’s track record of access to funding. FCOT also recorded S$284m of undrawn credit facilities as of 30 Sep 20.
· KrisEnergy Ltd. provided an update on its restructuring process on Tuesday. As mentioned in its presentation slide on 21 Aug 20, the company’s restructuring is to be implemented via four inter-conditional processes that require the consent of the requisite majority of each respective group of creditors and shareholders.
KrisEnergy has extended the maturity date of its revolving credit facility by 6 months to 30 Jun 21. The maturity date of the facility will be further extended to 30 Jun 24 upon the successful completion of the restructuring. With respect to unsecured creditors, the company updated that the Scheme of Arrangement was passed by the requisite statutory majority of the single class of Scheme Creditors on 14 Jan 21. The Consent Solicitation Exercise for zero-coupon notes holders was held on 11 Feb 21 and has been passed as an Extraordinary Resolution of the Noteholders without any amendment.
Lastly, the final stage will be the convening of an extraordinary meeting for shareholders to approve the resolutions relating to the issuance of shares for the proposed conversion of debt to equity pursuant to the Scheme of Arrangement and Consent Solicitation Exercise. The details of the EGM have not been announced.
· On Tuesday, Cathay Pacific Airways announced that they will be deferring the payment of the dividends that was payable to holder of preference shares on 16 Feb 21. Pursuant to the terms of the preference shares, the deferred amounts will accumulate and constitute arrears. Accordingly, the airline will not pay dividend to equity holders nor will it buy back any of its shares.
· Last Wednesday, Frasers Property Limited (“FPL”) announced the proposed renounceable rights issue of up to 1 billion new ordinary shares. TCC Assets Limited (“TCCA”) and Thai Beverage Public Company Limited (“ThaiBev” and together, the “Undertaking Shareholders”) had each given an irrevocable undertaking to subscribe and pay in full their subsidary’s pro rata entitlements of Rights Shares, being an aggregate of 940.17m shares.
The issue price of each rights share will be S$1.18 and the estimated net proceeds will be up to about S$1.28m and S$1m after expenses. FPL intends to utilise the net proceeds for (i) the acquisition, investment, capital expenditure and development of industrial, logistics and business park assets, (ii) the establishment of private funds or joint ventures or similar arrangements to invest in property assets (including commercial and ancillary assets), and (iii) general corporate purposes, including transaction costs, strategic investments, acquisitions, fixed commitments, and development or redevelopment of existing assets.
· In relation the FPL rights issue, Thai Beverage Public Company Limited (“ThaiBev”) also announced that it will subscribe in full for its pro rata entitlement of the FPL rights shares, the aggregate consideration payable by ThaiBev, which will be satisfied by an external loan from a financial institution is approximately S$360m.
· Tunghsu Venus Holdings Limited announced on Thursday that Ms Wing Sze Tiffany Wong and Mr Edward Simon Middleton of Alvarez & Marsal Asia Limited, and Mr Wesley Arthur Edwards of CVR Global (B.V.I.) Ltd were appointed as Joint Liquidators of the company. The liquidators would like to engage in a discussion with noteholders of the 7% senior guaranteed bonds due 2020. Noteholders are encouraged to contact them at ProjectDX@alvarezandmarsal.com.
· Oxley Holdings Limited uploaded its results for the first half period ended 31 Dec 20 (“1HFY21”) on Sunday. Group revenue increased 25% from a year ago to S$745m, backed by contributions from its subsidiary in Australia, as well as higher revenue from its projects in Cambodia, Singapore and the UK. Net profit after tax surged 210% YoY to S$40m.
However, the group’s cash position of S$233m was considerably lower than its other financial liabilities of S$926m as at 31 Dec 20. According to the company, it collected S$268m in cash from its developments in the UK and Ireland and the proceeds were used to pay down its borrowings. Net gearing decreased to 2.31x in 1HFY21 from 2.48x in 2HFY20. Excluding lease liabilities, net gearing would have been 2.25x at 1HFY21.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!










