Important Events
Last Friday, the Bank of Japan decided to keep the policy rate for financial institutions at -0.1%. To control the yield at the long end of the curve, the Bank of Japan will purchase an unlimited amount of government bonds so that the 10-year government bond yield will be kept at around zero percent. Furthermore, the central bank will continue to grow the monetary base, by purchasing exchange traded funds, real estate investment trusts and corporate bonds, such that the yearly change in the consumer price index exceeds and remains above 2 percent.
Domestically, Japan’s economy is gradually recovering as export demand is improving while the downside effects from Covid-19 have waned. Corporate profits are increasing and business sentiment is still healthy. Inflation expectations have climbed in part due to rising energy prices and accommodative financial conditions. Policy Board members at the Bank of Japan have maintained their real GDP forecast for fiscal year 2023 around between 1.0% and 1.4%, but raised their CPI forecast to between 1.0% and 1.3%, from 0.9% and 1.2%.
European Central Bank (“ECB”) President Christine Lagarde has dismissed the notion of a faster-than-expected interest rate hike on Monday. The ECB President said that any changes to the monetary policy will be gradual despite record inflation readings in the Euro area. Nonetheless, President Lagarde was notably more hawkish following the latest ECB council meeting, as she refused to rule out the possibility of raising interest rates this year. This will mark the first interest rate hike in more than a decade. Meanwhile, Dutch Central Bank President Klaas Knot said that he expects the first ECB rate hike to be delivered in the fourth quarter this year, followed by another rate hike shortly after in the first quarter of 2023.
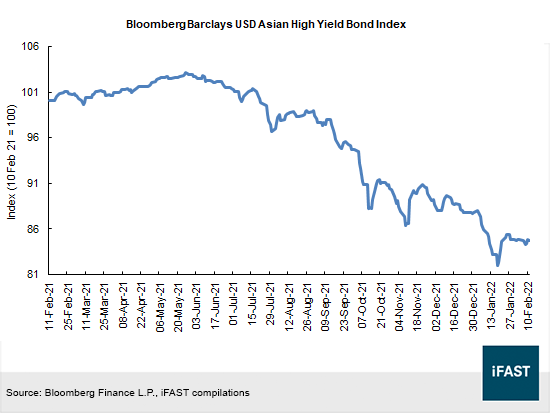
Asian High Yield Bond Index
Asian high yield bonds recorded modest losses last week in spite of a volatile equity market. Overall, the Bloomberg Barclays USD Asian High Yield Index lost just 0.2%.
On Wednesday, Logan Group clarified that the rumour of the company changing its auditor is not true. The company and the auditor have a good relationship and there was no such discussion on the subject. Project developments and operations continue to function normally.
Greentown China reported its monthly contracted sales on Wednesday. In January, the group achieved total contracted sales of RMB 11b, down by 33.7% YoY, and contracted sales area of approximately 520 thousand square meters, with an average selling price of approximately RMB 22,369 per square meter.
On Thursday, China Overseas Limited reported its monthly contracted sales. In January, the group achieved total contracted sales of RMB 14.8b, representing a drop of 45.3% YoY, and contracted sales area of approximately 827,800 square meters, with contracted average selling price of approximately RMB18 thousand per square meter.
Interest Rates and Currencies
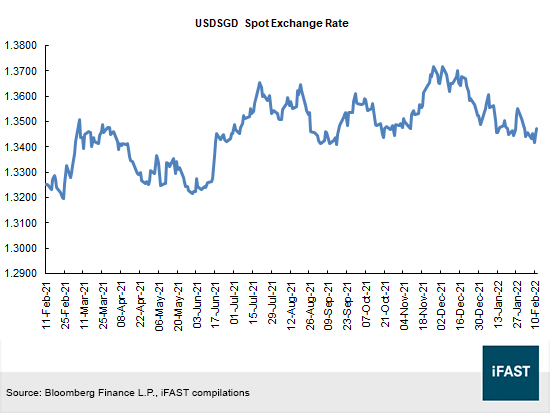
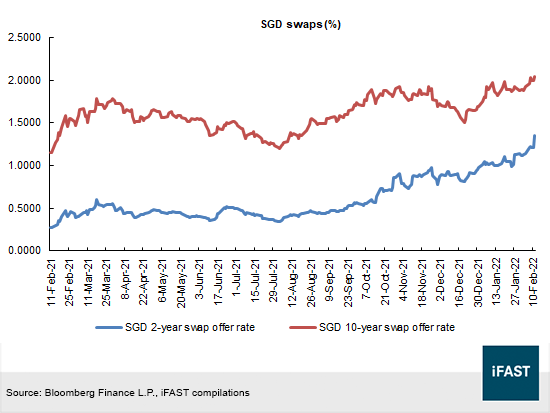
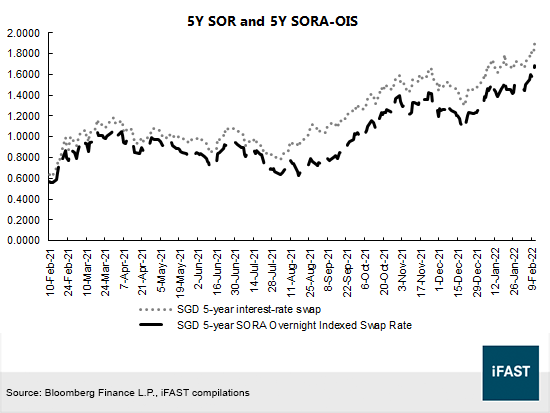
The Singapore dollar was nearly unchanged against the US dollar during the week. The USD/SGD pair finished at 1.3471 on Friday. This week, Singapore’s Finance Minister will deliver the Budget Statement on 18 February 2022. Market observers are expecting the Minister to announce a new GST hike either this year or next year, the implementation of a wealth tax, carbon tax and support for low income households. The 2-year Swap Offer Rate (“SOR”) and the 10-year SOR soared by 21 basis points (“bps”) and 13bps to 1.3500% and 2.0465% respectively. Meanwhile, the 5-year SOR and 5-year SORA-OIS likewise climbed by 18bps and 19bps to 1.900% and 1.6825% respectively.
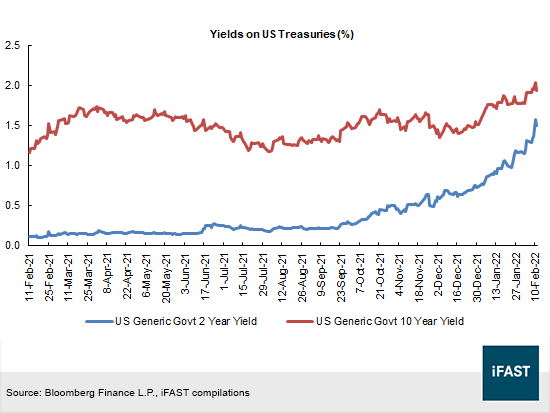
The 10-year US Treasury yield exceeded 2% for the first time since August 2019 after inflation data from the US showed that consumer prices are still setting new record highs. US inflation climbed to a 40-year high in January as service costs jumped the most in 31 years. The 10-year US Treasury yield rose 3bps to 1.9371%, while the 2-year US Treasury yield climbed 19bps to 1.4997%.
Corporate Updates and New Issues
Last Monday, Nagacorp Ltd. announced results for the year ended 31 December 2021. Group revenue dropped from USD 878.7m to USD 225.9m and the company made a net loss of USD 147.0m, a sharp contrast to the USD 102.3m of profit in 2020. Revenue from operations at gaming tables to hotel reservations fell in 2021 compared to 2020.
Nagacorp recorded USD 193.6m of current assets and USD 151.4m of current liabilities but its cash position of USD 102.7m at end 2021 is much lower than the USD 437.7m at end 2020. The group has no current short term borrowings but its USD 550m NAGACL 7.950% 06Jul2024 Corp (USD) is due in 2024. Last year, Nagacorp issued an additional USD 200m of the 2024 bonds at an interest rate of 7.95%.
On Monday, Ezion Holdings Limited announced that it has sold a bareboat charter and eventual disposal of one of its vessels - “Teras Conquest 1” to April Pearl Pte Ltd. Based on the minimum and maximum consideration of the deal, the excess consideration over book value for the vessel is between USD 3.885m and USD 4.035m. Ezion is expected to book a gain of between USD 3,772,850 and USD 3,842,550 for the transaction.
On Wednesday, the company updated that the Singapore Courts have fixed a hearing for the company’s winding up application on 18 February 2022. Creditors may request for a copy of the winding up application after paying the regulated charge.
The managers of Keppel Infrastructure Trust (“KIT”) informed that they will invest USD 250.0m in Aramco Gas Pipelines Company, an entity with cash flows derived from the gas pipelines network of Saudi Arabian Oil Company. KIT, BlackRock Real Assets and Hassana Investment Company will be investing in a special purpose vehicle, which will be given the rights to operate and maintain Aramco’s gas pipeline network in Saudi Arabia for a period of 20 years. Upon completion, KIT’s total asset under management will increase from USD 4.5b to USD 4.6b.
Keppel Corporation Limited announced on Wednesday that its Offshore & Marine subsidiary has been awarded USD 250.0m of contracts for the conversion of a Floating Storage and Regasification Unit, integration of a Floating Production Storage and Offloading vessel, and the jumboisation of 2 Trailing Suction Hopper Dredgers. The contracts however, will not have a material impact on Keppel’s net tangible assets or earnings for the present financial year.
Keppel also notified that it had filed a notice of arbitration with the Singapore International Arbitration Centre to begin arbitration proceedings against Singapore Press Holdings as it does not agree with SPH’s attempt to terminate the Keppel implementation agreement dated 2 August 2021. SPH may have breached certain obligations and will have to compensate Keppel Pegasus, a unit of Keppel Corporation Limited.
Last week, Cathay Pacific Airways updated that its will defer the dividend on its preference shares due on 14 February 2022. As a result, the deferred amount will accumulate and constitute as arrears under the terms of the preference shares. In addition, Cathay Pacific will halt dividend or buy back its shares.
Olam International Limited announced results of the voting outcomes for different bonds on Thursday. The Substitution Resolution for the OLAMSP 4.375% 09Jan2023 Corp (USD) was not passed. Bondholders who voted for both the Waiver and Substitution Extraordinary Resolution will be entitled to receive the consent fee for the Waiver Extraordinary Resolution. However, Olam Group Limited will replace Olam International Limited as the issuer due to the passing of the resolution for the OLAMSP 5.375% Perpetual Corp (SGD). The outstanding amount of the OLAMSP 5.375% Perpetual Corp (SGD) will increase to SGD 604.5m as SGD 54.5m of bondholders for the OLAMSP 5.500% Perpetual Corp (SGD) have voted to exchange their notes. In addition, Olam informed that the Extraordinary Resolutions for the OLAMSP 4.000% 24Feb2026 Corp (SGD) and OLAMSP 6.000% 25Oct2022 Corp (SGD) were passed.
Olam made an announcement on Friday informing that it will divest its remaining interest in ARISE Integrated Industrial Platforms (“ARISE IIP”) and ARISE Infrastructure Services (“ARISE IS”) for USD 189.0m. It will still keep its 32.4% stake in ARISE Ports & Logistics (“ARISE P&L”). If all goes to plan, the divestment is expected to be completed in the second quarter of 2022.
Last Friday, The Straits Trading Company notified that it is investing AUD 150.0m (~SGD 143.9m) in 2 freehold office buildings in Australia, and GBP 60.0m (~SGD 108.6m) in warehouse retail parks in the United Kingdom. In Australia, The Straits Trading Company is acquiring 1010 La Trobe Street, 192 Harbour Esplanade and 163 parking bays in Docklands, Victoria. As for the UK properties, the transaction for the retail parks acquisition was last announced in October 2021. As of December 2021, the company had completed the acquisition of one property in Cardiff, Wales and exchanged contracts on 2 others in England and Scotland.
Changi Airport Group (“CAG”) announced on Friday that it has applied for a re-auction for the concession of Tom Jobim International Airport in Brazil. The current concession was awarded in November 2013 and will last 25-years until 2039. Changi Airports International owns 51% of RIOgaleao, the airport manager of the Tom Jobim International Airport. Its investment was significantly impaired over the last 2 years and the group will conduct an impairment review during the upcoming reporting period ending 31 March 2022.