Central China Real Estate Limited (“CENCHI”), a Chinese real estate developer listed on the Hong Kong Stock Exchange (stock code: 832 HK) is issuing a new USD bond at an initial price guidance (“IPG”) of 8.35%. The bond is expected to be rated ‘BB-‘ by Fitch Ratings, which is the same credit rating as the issuer. Fitch, Moody’s, and S&P have stable outlooks on CENCHI. Moody’s and S&P have assigned a ‘Ba3’ and ‘B+’ rating on the issuer respectively.
According to the company, proceeds of the bond offering will be used to refinance existing short-term borrowings. The notes are guaranteed by some of the group’s offshore subsidiaries, and secured by share pledges from certain subsidiary guarantors.
About Central China Real Estate
The firm has been building and selling real estate for 28 years, and is widely recognized as the market leader in the Henan Province. At the end of December 2019, CENCHI had 214 projects under development with total gross floor area of 38.6m square meters (“sqm”) and land reserves of approximately 47.7m sqm. The group acquired 13m sqm of new land during 2019 at an average cost of RMB 1,744 per sqm, lifting the average land cost for its entire land portfolio to RMB 1,280 per sqm.
In addition, CENCHI operates 7 hotels in Henan with 1,645 guest rooms. These include Le Meridien Zhengzhou, Aloft Zhengzhou Shangjie, Pullman Kaifeng Jianye, Four Points by Sheraton Luohe and Holiday Inn Nanyang. Majority of CENCHI’s property portfolio is made up of residential apartments (70.3%), followed by commercial buildings (8.1%) and hotels (0.1%).
Recent corporate developments
CENCHI is tapping the market yet again after a series of capital raising exercises this year. In January and February, the company issued USD 200m 7.25% notes and USD 300m 6.875% notes due 2024 and 2021 respectively. Earlier this year, it also provided guarantee on a USD 203m 6.875% bond due 2021, which was issued to Ping An Insurance Overseas (Holdings) Limited from Jiayao Global Investments, a 63.5% shareholder of DIT Group Limited. Jiayao is indirectly wholly-owned and controlled by Mr. Wu Po Sum, the chairman and founder of CENCHI.
Figure 1: Contracted sales
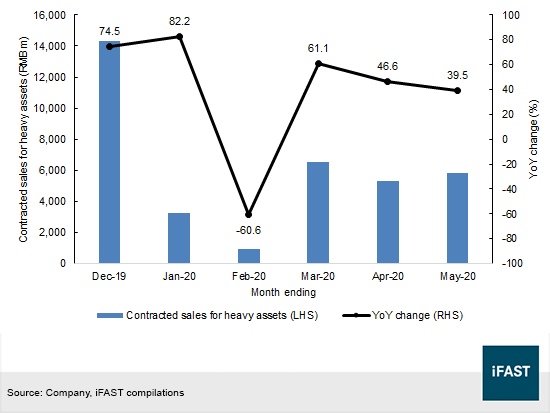
Property sales have been robust in 2020 as the developer managed to deliver double digit year-on-year gains in contracted sales for heavy assets (Figure 1). For instances, CENCHI sold RMB 5.34 billion and RMB 5.86 billion of real estate (heavy assets) in April and May this year, representing 46.6% and 39.5% YoY gains in pre-sales from a year ago. It is evident that transactions dropped 60% in February, but that was due to a nationwide lockdown that affected buying activity in Henan.
Although CENCHI has seen an overall healthy start to the year, the amount of transacted activity is still short of the group’s 2020 target. In the company’s results presentation for 2019, it projected to reach RMB 80 billion of sales this year, but year-to-date May only RMB 22 billion of heavy assets have been sold.
Healthy credit profile
CENCHI has raked up a decent performance during 2019 and we are comfortable with its debt-servicing ability within a twelve-month time frame. Earnings excluding interest, taxes and investment gains on investment properties (“adjusted EBIT”) more than doubled to RMB 5.4 billion during 2019, and adjusted EBIT over interest expense increased from 2.0x in 2018 to 2.4x in 2019.
Gearing was high with a debt-to-total capital ratio of 71% at the end of 2019. Borrowings increased by 58.6% to RMB 31.5 billion due to the issuance of USD 1.1 billion in senior notes and increase in onshore bank loans. Total shareholders’ equity increased by 22.7% to RMB 12.6 billion, resulting in a debt-to-equity ratio of 2.5x.
Nonetheless, the real estate developer has reasonable access to capital to meet payment requirements. Unrestricted cash was RMB 22.7 billion at 31 Dec 19, which is more than sufficient to cover its short-term debt and lease liabilities of RMB 12.6 billion. If need be, the group could tap its available uncommitted RMB 21.4 billion credit facilities, or divest completed properties, properties held for future development, land and a number of other assets to meet financial obligations. For a more detailed analysis of CENCHI’s 2019 performance, kindly refer to our recent report on the issuer – “Central China Real Estate bonds have rebounded strongly. Are they still worth investing in?”.
Bond valuation
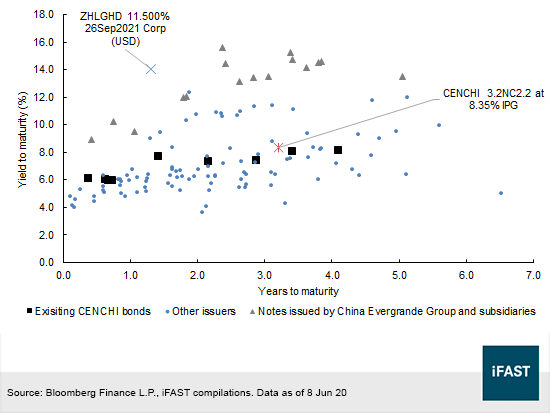
At the IPG of 8.35%, we think that CENCHI’s 3.2NC2.2 USD issue is attractively priced along the CENCHI curve (Figure 1), albeit it does not command the cheapest valuation among other issues of comparable credit ratings ranging from ‘B’ to ‘BB+’. Bonds issued by China Evergrande Group and the ZHLGHD 11.500% 26Sep2021 Corp (USD) of Zhongliang Holdings have noticeably higher yields to maturity.
Figure 2: Relative valuation among credits of similar credit ratings
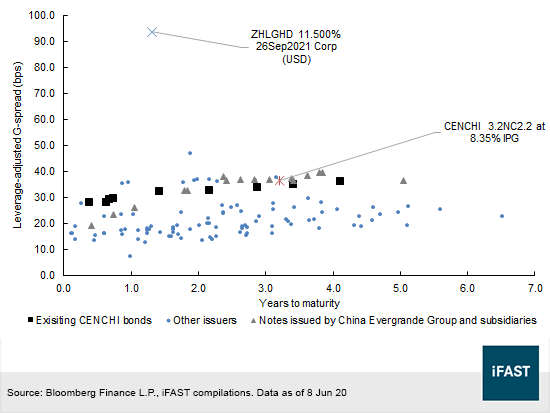
However, if we adjust credit spreads to take into account differences in leverage, we think the new CENCHI 3.2NC2.2 USD notes are more attractive than bonds within the same sector (Figure 3). Our adjustment divides the G-spread (or credit spread over US Treasuries) of the bonds over the issuer’s debt-to-asset ratio.
Higher gearing ratios have shifted the notes of other Chinese real estate issuers downwards, and correspondingly the new CENCHI bond upwards. This is because CENCHI’s lower debt-to-asset ratio resulted in a smaller denominator. After the adjustment, the ZHLGHD 11.5% ‘21s remain as one of the most appealing credits, but the new CENCHI 8.35% (IPG) bond also provides one of the most attractive valuations among notes of the same maturity.
Figure 3: Leverage-adjusted credit spread comparison
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in EVERRE 7.500% 28Jun2023 Corp (USD) and EVERRE 8.250% 23Mar2022 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.