


Central China Real Estate Limited (“CENCHI”) is tapping the US dollar market with a 4.5NC2 issue, with an issue size of up to USD 200m. The issuer is rated Ba3, B+ and BB- by Moody’s, S&P and Fitch respectively with stable outlooks from all three rating agencies. The expected rating for the bond is B1 by Moody’s and BB- by Fitch. As of 11 am today, the new issue’s book size has reached over USD 1 billion.
About Central China Real Estate Limited
The company has been building and selling real estate for 27 years, and is widely recognized as the market leader in the Henan Province. As at 1H19, CENCHI had 127 projects under development with total gross floor area of 26.6m square meters (“sqm”) and land reserves of approximately 47.7m sqm. The current projects will likely be sufficient for another 3 to 5 years of development. The group spent RMB 9.8 billion acquiring 4.5m of new land in the first six months of 2019 at an average cost of RMB 2,176 per sqm, lifting the average land cost for its entire land portfolio to RMB 1,180 per sqm.
In addition, CENCHI operates 7 hotels in Henan with 1,655 guest rooms. These include Le Meridien in Zhengzhou, Aloft Zhengzhou Shangjie, Four Points by Sheraton Luohe and Holiday Inn Nanyang. Collectively, the developments in CENCHI’s portfolio are mostly residential apartments (70.6%), commercial buildings (7.9%) and hotels (0.6%).
Henan is the fifth largest economy in China with an approximate GDP of USD 349 billion, accounting for 5.4% of China’s total GDP in 1H19. According to provincial statistics, Henan had a population of 109m. Disposable income per capita in Henan increased 7.2% YoY to RMB 16,797.
The upside potential for city expansion within the province is high, given that the urbanization rate was 51.7% in 2018 — lower than more developed areas like 88.1% in Shanghai or 86.5% in Beijing. Although there may be concerns about lower city growth rates, management mentioned that property volume growth in lower-tiered cities were strong. For example, contracted sales measured in terms of gross floor area increased 25.7% in Luohe and 23.6% in Zhoukou during the first six months of 2019.
Incorporated in the Cayman Islands in 2007, CENCHI is 74.64% owned by Joy Bright Investments Limited, which is entirely owned by the group’s founder, Mr Wu Po Sum. There are four wholly-owned subsidiaries within the corporate structure, including Sino-Joy, CCRE Investments, CCRE Holdings and Bumper Up Ltd.
Credit highlights
In the six months ended June 2019, CENCHI secured RMB39.6 billion of contracted sales, up 24.1% from the same period last year. The average contracted sales price in June last year was RMB 7,233 per sqm, down slightly from RMB 7,348 per sqm in June 2018. Revenue surged 90.1% YoY to RMB 9.1 billion, resulting in RMB 2.5 billion of gross profit. Meanwhile, EBITDA increased 121% to RMB 3.2 billion in 1H19, and net profit was RMB 768m.
CENCHI’s credit profile strengthened in the one-year period between June 2019 and June 2018. Net gearing, defined as total debt less restricted cash, cash and cash equivalents over total equity, dropped from 47.3% in 1H18 to 18.3% in 1H19. From another perspective, total debt increased from RMB 19.8 billion to RMB 25.8 billion, resulting in a total debt to total capitalization ratio of 66.4% in 1H18 and 70.4% in 1H19. The company’s ability to service interest expenses also improved from 1.8x in 1H18 to 2.8x in 1H19 due to higher operating profit and significant gains in revenue.
The group has a healthy liquidity profile. With RMB 23.8 billion of cash, the cash-to-short-term debt ratio was 340% as at 1H19, up from 255% in 1H18. That aside, the firm may also tap into RMB 24.1 billion of total onshore available unused and uncommitted banking facilities for liquidity. Over the years, the group’s funding cost dropped from 7.9% in 2015 to 6.8% in 2017, but slowly climbed to 7.5% in 1H19.
Bond valuation
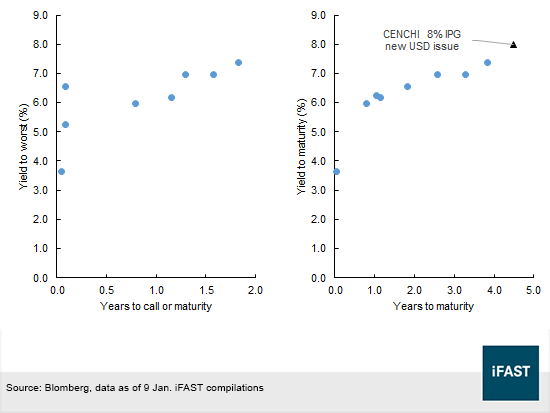
As mentioned in the offering circular, CENCHI intends to use proceeds from the bond offering to refinance existing medium- to long-term indebtedness. The CENCHI curve in Figure 1 showed that the 8% initial price guidance (“IPG”) is fairly priced as it is close to the yields to worst of existing USD-denominated CENCHI bonds. The issue is also fairly priced if we considered the yields to maturity of existing notes. For instance, the 8% IPG note offers a decent pickup of 62 basis points over the CENCHI 7.900% 07Nov2023 Corp (USD) for a tenure difference of slightly more than 6 months.
Figure 1: CENCHI’s existing USD curve
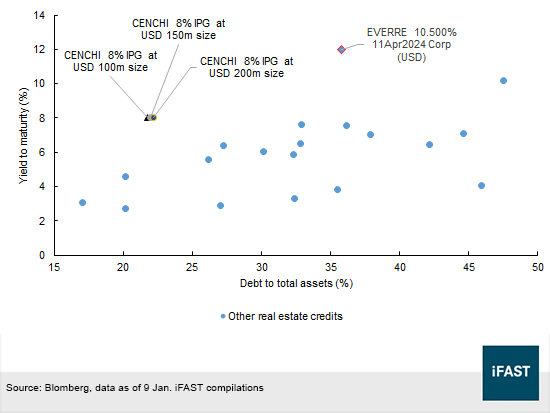
In the context of comparable credits with similar maturities, we think the new CENCHI USD note at its 8% IPG is attractively priced among Chinese property firms (see Figure 2). We would, however, be indifferent between the new CENCHI issue and the EVERRE 10.500% 11Apr2024 Corp (USD).
Among Chinese
developers of comparable financial leverage, CENCHI has one of the lowest debt-to-asset
ratios and offers yields on the high-end of the range. On the other hand, China
Evergrande Group is one of the top three developers in China with a vast land
bank and much bigger operating scale. The higher yield of the EVERRE 10.5% ’24s
is likely reflective of the issuer’s low financial liquidity, but we think that the developer may still raise liquidity by monetizing its land bank
in times of need.
Figure 2: Comparable real estate USD credits
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in EVERRE 7.500% 28Jun2023 Corp (USD) and EVERRE 8.250% 23Mar2022 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.










