China Aoyuan Group Limited (“Aoyuan”; stock ticker: 3883.HK), a leading Chinese property developer with over two decades of operating experience, is seeking to raise capital through a bond sale. The company has launched a 5.5-year USD bond at an initial price guidance (“IPG”) of 6.5%.
The bond is expected to be rated BB- by Fitch Ratings and B2 by Moody’s Investors Service. Aoyuan is rated BB- (positive), B1 (positive), B+ (positive) and BB+ (stable) by Fitch Ratings, Moody’s, S&P and Lianhe Global respectively.
The new issue is callable at 102 at any time on or after 24 Sep 23, and callable at 101 on or after 24 Sep 24. The notes are effectively subordinated to other secured obligations of the group and are guaranteed by the Subsidiary Guarantors and Joint Venture Subsidiary Guarantors on a senior basis, conditional on certain limitations mentioned in the offering memorandum.
About Aoyuan
As a publicly listed firm on the Hong Kong Stock Exchange, the group is currently owned by public investors (45.0%), Ace Rise Profits Limited (51.62%) and Joy Pacific Group Limited (3.38%). Mr Guo Zi Wen, the Chairman of the company, has an approximate 55.0% deemed interest in the firm.
Aoyuan has a 54.6% interest in Aoyuan Healthy Life Group Co., Ltd, a listed subsidiary that completed its initial public offering in 2019. In addition, Aoyuan acquired a 29.9% stake in Kinghand Industrial Investment Group Co., Ltd., a listed entity on the Shenzhen Stock Exchange, in May this year.
Over the years, Aoyuan has been focusing on developments along the Guangdong-Hong Kong-Macao Greater Bay Area (“GBA”), South China, East China, core regions of Central and Western China, as well as in the Bohai Rim. There are 317 projects at various stages of development right now, 112 of which are located in Guangdong. The group also has nine projects in Sydney, Australia and five projects in Vancouver, Canada.
As at 30 Jun 20, the total planned gross floor area (“GFA”) of its land bank is approximately 48.7m square meters (“sqm”). There are 5.13m sqm of completed properties, 24.4m of properties undergoing development and nearly 19.2m of real estate held for future development.
Nearly 80% of its land bank are made up of residential properties, while commercial properties, investment properties, auxiliary facilities account for 15%, 3% and 2% respectively. When classified by city tiers, 54% of the land bank (excluding urban redevelopments) are in Tier-1, Tier-2 and international cities. The remaining 48% of the land bank are in Tier-3 and Tier-4 cities.
Financial highlights
In the six months ended 30 Jun 20 (“1H20”), Aoyuan recorded total revenue of RMB 28.24 billion, up 19.3% from RMB 23.67 billion during the same period a year ago (“1H19”). Gross profit margin was 29.3%, down slightly from 29.8% in 1H19. Net profit was nearly flat at RMB 2.84 billion, but this was largely due to higher income tax expenses of RMB 3.28 billion (1H19: RMB 2.63 billion). Group profit before tax actually improved by 12.6% year-on-year to RMB 6.12 billion.
After the COVID-19 disruptions early in the year, Aoyuan resumed selling activities in late March and early April. Sales gradually picked up and gained momentum in July and August, as contracted sales were higher by 43% YoY and 41% YoY respectively in those two months. Contracted sales added to RMB 71.28 billion in the first eight months of the year, equating to 54% of its 2020 target. According to the developer, there were RMB 180 billion of unbilled sales at the end of June, which would be booked within the following two years.
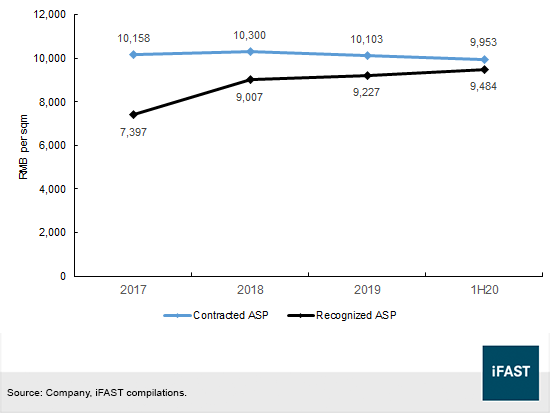
Average selling prices (“ASP”), on the other hand, have been falling (Figure 1). During the first six months of the year, the ASP (exclusive of tax) of delivered properties decreased by 12.1% to RMB 9,484 per sqm from RMB 10,785 per sqm in 1H19. Aoyuan said this was because the properties delivered in the first half of 2020 mainly came from the Ningbo and Nanning regions, while delivered properties in the corresponding period of last year were mostly from Shenzhen and Guangzhou. Even though contracted ASPs fell from 2017 to 1H20, recognized ASPs were mostly on an uptrend. At RMB 9,484 per sqm, the ASP of its delivered properties still indicated a substantial margin over the average land cost of RMB 3,812 per sqm of newly added projects in 1H20.
Figure 1: Contracted and recognized average selling price (“ASP”)
More notably, the group’s net cash used in operating activities widened from -RMB 737m in 1H19 to -RMB 12.28 billion in 1H20. Operating cash flows before movements in working capital improved from RMB 5.12 billion to RMB 6.00 billion but large movements in trade and other receivables, payables and contract liabilities led to a swing in cash from operations from RMB 4.02 billion to negative RMB 5.48 billion.
Aoyuan has a sound liquidity profile. The company registered a total cash balance of RMB 53.0 billion at the end of June (1H19: RMB 58.0 billion), which was sufficient to cover its debt maturing within a year. The firm may also use its RMB 94.30 billion of undrawn credit lines to pay down current financial obligations, comprised of senior notes and bonds (RMB 10.87 billion), bank and other borrowings (RMB 36.64 billion), lease liabilities (RMB 272m) and a financial liability (RMB 27m) tied to the acquisition of Zhejiang Liantianmei Enterprise Management.
As far as debt issuance is concerned, Aoyuan has been fairly active in capital markets this year. In January and April, the firm secured two tranches of three-year loans at HIBOR/LIBOR + 4.3% with nine offshore commercial lenders. It also issued the CAPG 4.800% 18Feb2021 Corp (USD) in February and CAPG 6.350% 08Feb2024 Corp (USD) in July. In February, the developer increased onshore issuances by RMB 2.54 billion through a 2025 5.5% offering. Lastly, in August, RMB 1.8 billion of onshore corporate bonds due 2025 were issued at 5.65%.
Based on Aoyuan’s reported key financial ratios, the gearing profile of the group deteriorated during 1H20. Net debt over total equity increased from 64.2% in 1H19 to 79.8% in 1H20, exceeding levels at the end of the last three years. Net debt as a percentage of total capitalization (i.e. total equity + total debt) climbed to 23.2% (1H19: 20.1%), and revenue over net debt dropped from 1.8x in trailing-twelve-month (“TTM”) 1H19 to 1.6x in TTM 1H20. However, trade receivables of property development, as a percentage of recognized sales, had generally been a downtrend, falling from 1.54% in 2017 to 1.35% in 1H20.
Bond pricing
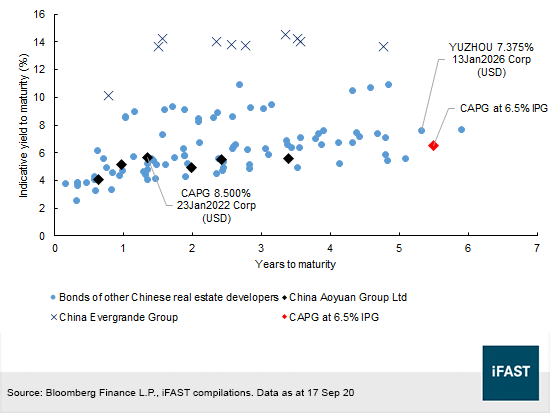
At the initial price guidance (“IPG”) of 6.5%, we think Aoyuan’s new USD bond due 2026 is fairly priced among other single-B names (Figure 2). We are somewhat indifferent between Aoyuan’s new note and the CAPG 8.500% 23Jan2022 Corp (USD), with a yield to maturity of 5.7%, as we think the pickup of 81 basis points is reasonable for a 4.1-year longer tenure.
The closest peer in the sector would arguably be the YUZHOU 7.375% 13Jan2026 Corp (USD), with an indicative yield to maturity of 7.6%. Yuzhou Group Holdings Company Limited is a real estate developer primarily focused in the Yangtze River Delta region and strongly positioned in the West Strait Economic Zone. Between these two firms, we are more positive on Aoyuan’s growth and profitability outlook, given its exposure to the GBA and the long-term growth potential of the area.
Within the higher yielding segment of the sector, we observed from Figure 2 that notes of China Evergrande Group have yields north of 10%. Our buy recommendation on Evergrande’s short-term bonds (see “Evergrande – Entering the Era of Deleveraging”) – those maturing before 2022 – still holds in view of the group’s 1) strong cash collection rate amid the recent pandemic; 2) improved liquidity after recent refinancing; 3) management guidance that the company will deleverage; and 4) bond valuation. Prices of Evergrande’s bonds have rallied alongside the broader Asian bond market, with yields declining from >20% to mid-teens since April.
Figure 2: Relative valuation among single-B and BB- USD notes
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in EVERRE 8.250% 23Mar2022 Corp (USD) and EVERRE 7.500% 28Jun2023 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our new podcast series, Yield Hunters, is now available on Spotify, iTunes Podcasts and Google Podcasts. In this episode, we explore the stability and growth of the Chinese real estate developers as they continue to raise debt.