


Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Note: This is an edited version of an article published earlier on our affiliates on 8 July 2021
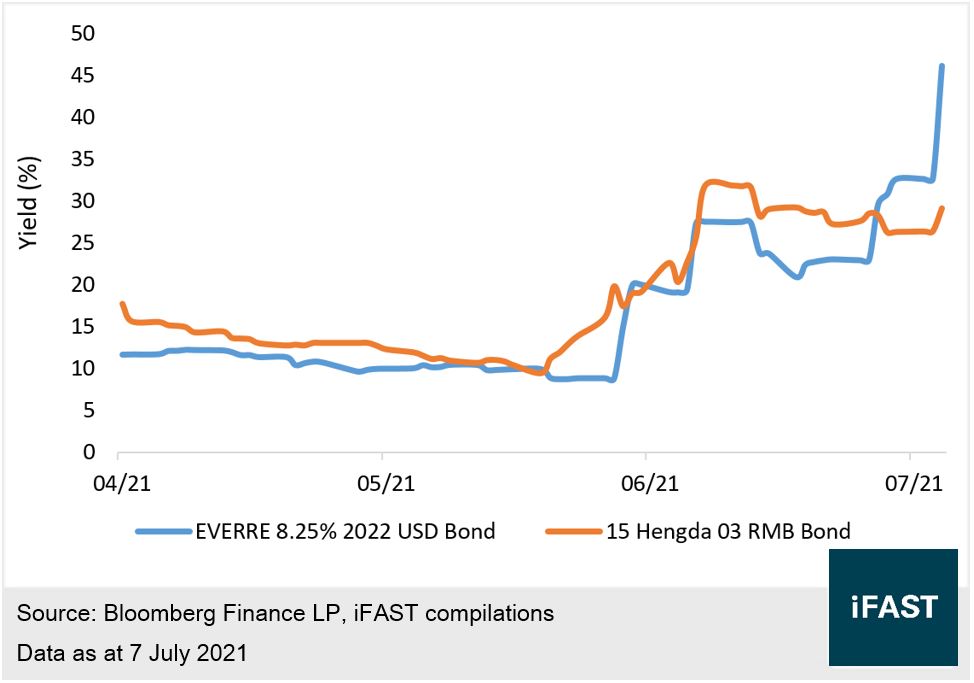
Evergrande bonds faced further selloff again this week, but the onshore RMB bond yields remained resilient and did not spike as much as its USD counterparts.
Evergrande’s sales and cash collection remain strong this year, and the equity financing in recent months could help sustaining its cash flows. The Group’s strengths are not comparable against other distressed or defaulted issuers.
We maintain our view on its short-term bonds, including the one on Bond Express "EVERRE 8.250% 23MAR2022 CORP (USD)”.
Evergrande’s USD bonds further plunged this week, as the price of the bond due in March 2022 dived to the same level as that of last September. This has led to an inversion across Evergrande’s yield curve. Given the continued decline, we are providing another update consolidating the possible reasons leading to the price drop.
(1). The aftermath of previous negative rumours
Please refer to our previous update, “China Evergrande is surrounded by rumours again. What is happening this time?”
(2). Credit downgrade to B and B2 by Fitch and Moody's
We mentioned last year that Evergrande’s current credit status may lead to a possibility of credit downgrade. To be fair, a credit rating of B is more appropriate for Evergrande given its key credit indicators. Thus, we are not surprised by this rating downgrade, and we do not think this will pose further pressure on future bond price.
(3). Broad market selloff of Chinese real estate bonds
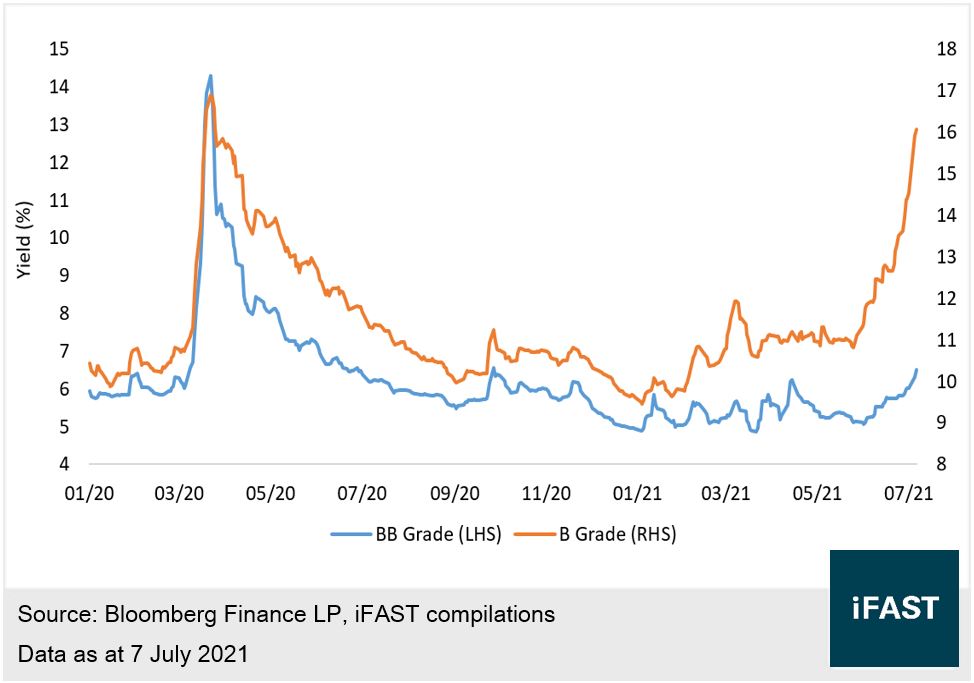
The overall price of Chinese real estate bonds have declined in recent days, causing a spike in average yield (see Chart 1). Investors may be looking for higher risk premium because of the recent heightened political risks, which have led to a series of risk-off actions in both bonds and stocks.
Chart 1: FSM Chinese Real Estate Bond Yield Index
(4). End of promotion sales
There are rumours that Evergrande has ended all its large discount sales events, and that it will even raise the retail prices of unsold units by 15%. The Group later denied the rumours, but some investors may still be concerned about a price hike damaging Evergrande’s cash flows. However, we think this reason is not justified because the previous price discounts were also considered bad news by the market.
Evergrande’s contracted sales in first half of 2021 increased by 2% YoY to 357 billion RMB, with a target completion rate of 48%. Meanwhile, its cash collection for the period has reached 321 billion RMB (cash collection ratio: 90%). In addition, the Group continued to raise capital through equity financing, and we believe those subsidiaries will serve as key assets in sustaining its cash flows (see Table 1).
Table 1: Evergrande’s Equity Financing in Recent Months
Month | Subsidiary | Amount | Remarks |
March | Fangchebao | 16.4 billion HKD | 72% ownership, estimated market cap of 130 billion RMB |
May | Evergrande New Energy Vehicle | 10.6 billion HKD | 65% ownership, market cap about 272.1 billion HKD |
June | HengTen Networks | 4.4 billion HKD | 38% ownership, market cap about 51.4 billion HKD |
June | Calxon Group | 3.0 billion HKD | 28% ownership, market cap about 8.6 billion RMB |
Evergrande Property: 60% ownership, market cap about 98.8 billion HKD Shengjing Bank: 36% ownership, market cap about 60.8 billion HKD Others: Cultural tourism and healthcare division, Evergrande Spring, etc | |||
Source: Company announcements, HKEX, Shenzhen Exchange, Hithink Data as at 7 July 2021 | |||
We have to consider each issuer’s liquidity factors, including sales condition, land bank scale, financing ability, etc. By comparing Evergrande and other similar issuers to recent distressed or defaulted cases, we can observe that Evergrande has a superior performance in terms of land bank lifespan, sales growth and cash collection ratio against names like China Fortune Land and Sichuan Languang (see Table 2).
Table 2: Comparison between Evergrande and Peers
Land Bank to Sales Ratio (by Area) | 2020 Sales Growth | 2021 1H Sales Growth | 2020 Cash Collection Ratio | |
Evergrande | 2.9 | +20% | +2% | 90% |
Fantasia | 5.1 | +36% | +60% | 85%^ |
Sinic | 4.5 | +24% | +35%* | 85% |
Guangzhou R&F | 4.5 | +0% | +18% | 78% |
Risesun | 3.3 | +10% | +24% | 63% |
Languang | 2.2 | +2% | +18%* | 87% |
China Fortune Land | 1.1** | -35% | N/A | 72%** |
* From CRIC Statistics ** From 2020 Interim Report ^ From Fitch Ratings Source: Company Announcements, CRIC Statistics, Fitch Ratings Data as of 31 December 2020 | ||||
Evergrande’s onshore and offshore bonds moved differently this week, as the onshore RMB bond yields did not spike as much compared to USD bonds. This may imply that onshore investors have had a muted reaction to recent news (see Chart 2). We maintain our view on its short-term bonds, including the one on Bond Express “EVERRE 8.250% 23MAR2022 CORP (USD)”.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in EVERRE 7.500% 28Jun2023 Corp (USD), EVERRE 8.250% 23Mar2022 Corp (USD) and FTHDGR 7.950% 05Jul2022 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.









