Important Events
Commerzbank Aktiengesellschaft (“Commerzbank”) has announced a 10.5NC2.5 Tier 2 SGD bond at an initial price guidance (IPG) of 6.625%. The bond is expected to be issued on 24 October 2023, with a reset date of 24 April 2029, and a maturity date of 24 April 2034. If uncalled, the coupon of this bond will reset at a reset rate based on the 5y SORA-OIS plus an initial margin determined upon issuance.
The issuer is rated A2 (Stable) by Moody’s and A- (Stable) by S&P – as we highlighted in our previous article, this is a fairly recent rating upgrade in March 2023 (from BBB+ [S&P]). This new issuance is expected to have an issue rating of Baa3 by Moody’s. The bond will be issued under Commerzbank’s EMTN Programme, which states that the net proceeds will be used for general corporate and financing purposes of the Group.
About Commerzbank
Commerzbank is one of Germany’s leading financial institutions with a history dating back to 1870. Today, it has offices in 40 countries, though its presence is strongest within Germany and (to a smaller extent) the rest of Europe. While it serves a mix of retail, business, and corporate clients, it is most well-known for its strong corporate banking segment.
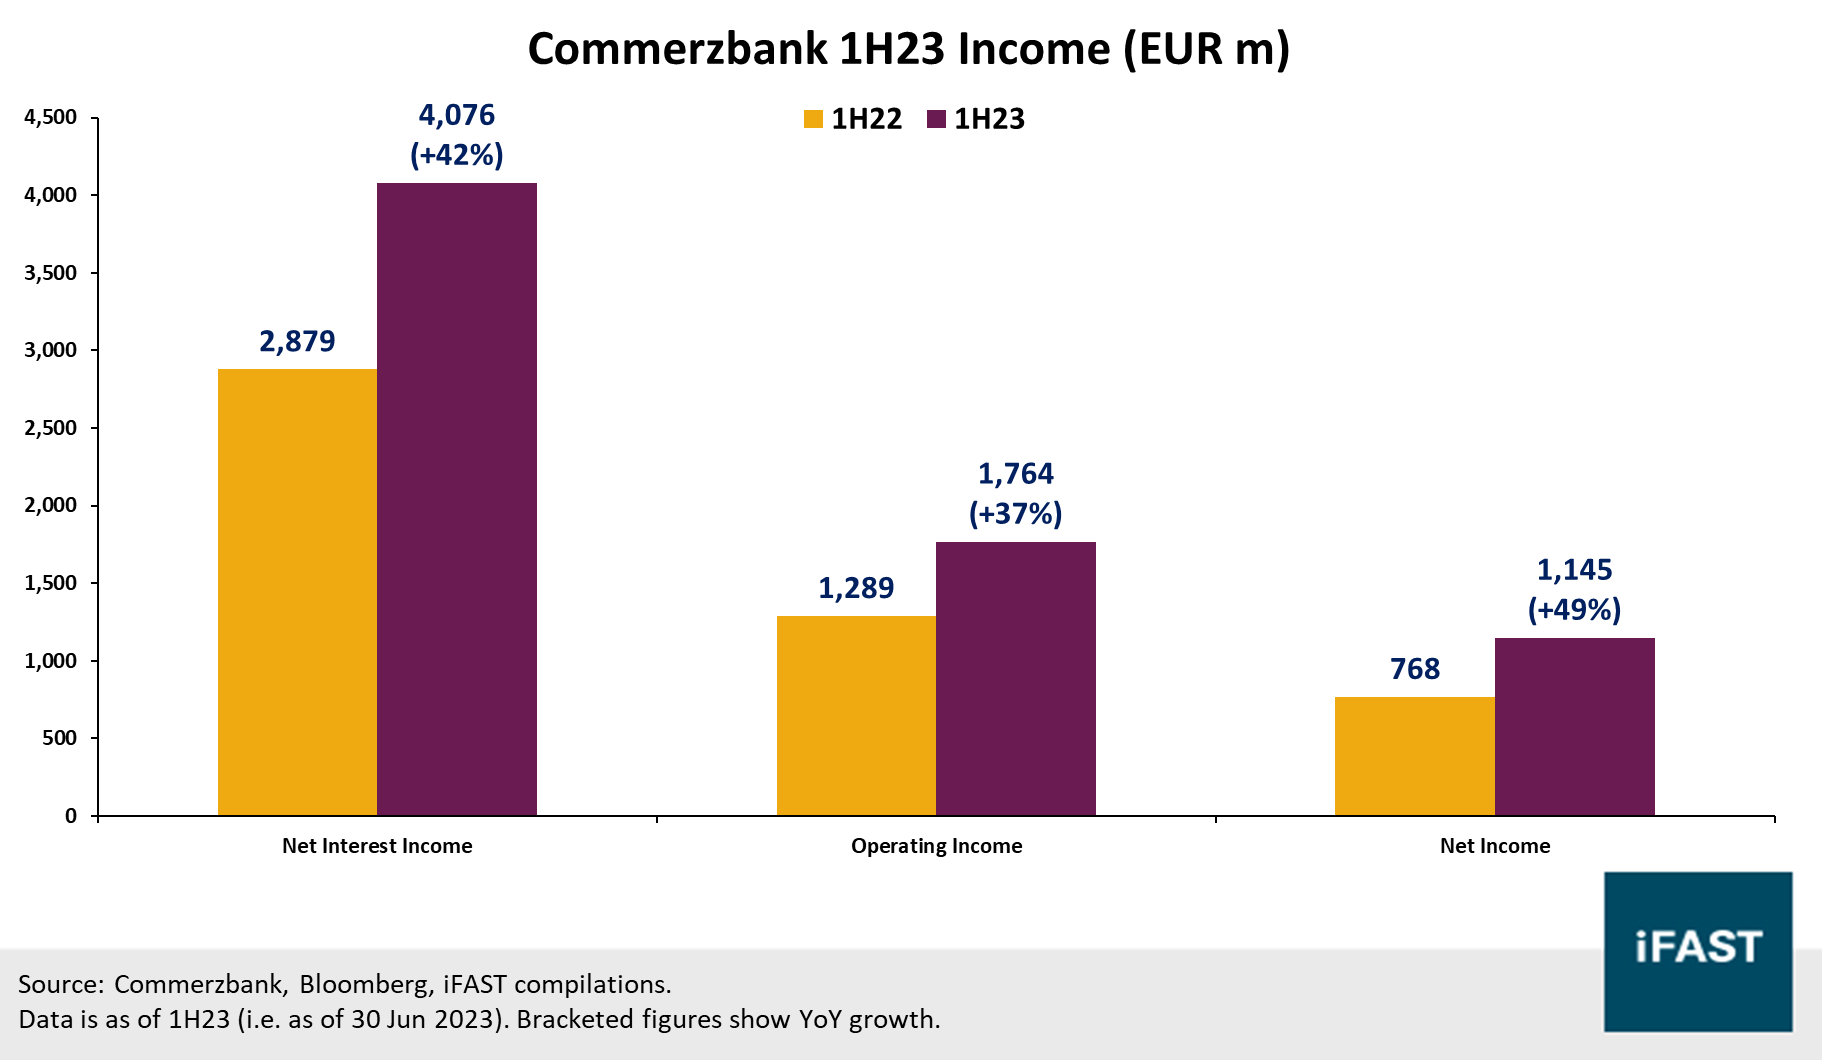
Commerzbank continued to see strong growth in various income metrics in the half year ended 30 June 2023 (1H23) (Chart 1). Net interest income rose by +42% YoY to EUR 4,076m, led by Commerzbank’s deposit business in Germany and at mBank, on the back of improved net interest margins amidst the rising-rates environment. Operating income also climbed by +37% YoY to EUR 1,764m, while Group net income rose by +49% YoY to EUR 1,145m. We find this income growth to be fairly impressive, especially considering it also includes a sizeable provision of EUR 520m in connection with mBank.
Chart 1: Commerzbank’s income figures in 1H23
We also find that Commerzbank’s broader credit and liquidity profiles remain fairly decent. For instance, Commerzbank reported a CET1 ratio of 14.4% in 1H23, marking 5 consecutive halves of improvements (from 13.22% in 2H20) – this also represents a comfortable buffer of 436 bps over the regulatory minimum level (maximum distributable amount or MDA requirement) of 10.08%. Its leverage ratio also remained stable at 4.9% in 1H23 (2H22: 4.9%), while its liquidity coverage ratio fell just slightly to 138.8% (2H22: 141.1%) but nonetheless well above the regulatory minimum of 100%.
Looking ahead, Commerzbank management continues to maintain a fairly optimistic outlook for FY23 results. While a mild recession (within Europe) in 2023 is the assumption, management expects net interest income to hit at least EUR 7.8b (FY22: EUR 6.5b). They also continue to place a large emphasis on cutting costs amidst the ongoing inflationary environment, with a target cost/income ratio of 60% in 2024. Finally, management has revised their CET1 ratio target to “more than 14%”. As a whole, considering the higher-for-longer rates environment, Commerzbank remains well-placed to reach these adjusted targets and remain profitable.
Three things you should note before investing
In totality, we think the broader outlook for Commerzbank remains fairly positive. With that in mind, we wish to highlight three factors that bond investors should note before investing:
- Commerzbank continues to be embroiled in a lawsuit over its subsidiary mBank. While mBank’s core operating performance has continued to improve over time, headline profitability has been adversely affected by the increase in provisions for the lawsuit. As such, if this litigation becomes even more protracted, it could continue to weigh on mBank’s overall profitability (and therefore its profit contribution to Commerzbank).
- Both bonds are Tier 2 subordinated and unsecured, meaning that they inherently have loss-absorption features, where Eurozone / German bank regulators have the option to write down (including to zero) these bonds or convert them into equity in the event the bank fails.
- As the reset date is quite some time away (5.5 years), bond investors are subject to longer-term uncertainty over the prospects for Commerzbank and Europe/Germany as a whole. If these deteriorate over time, we could see an increase in non-call risks for this bond.
With these three factors in mind, we think that this new issuance should primarily be of interest to investors with a higher risk tolerance, but nonetheless wish to remain within the investment-grade space.
About the new 10.5NC5.5 bond
Commerzbank currently has one other SGD issuance still outstanding: CMZB 5.700% 03May2033 Corp (SGD) (Table 1). Both bonds are Tier 2 subordinated and come with loss-absorption features as described above, while they also both have reset dates occurring 5 years before the eventual maturity date. Their issue ratings are also expected to be the same (Baa3 by Moody’s), which is likely given their equivalent seniority.
We think this bond appears to be fairly attractive based on the IPG of 6.625%, especially when compared with the existing CMZB 5.700% 03May2033 Corp (SGD)’s yields – the latter has a yield-to-reset of 5.668% and a yield-to-maturity of 5.948%. In addition, considering the latest 5y SORA of 3.3775% (as of 16 October 2023), this would translate to an initial margin of 3.2475%, higher than the existing bond’s initial margin of 2.856%. Nonetheless, we caveat that these calculations are based on the IPG of 6.625%, and we expect the final price guidance to be lower than this IPG, which would decrease the eventual results for both yields and initial margins.
Table 1: Comparison between CMZB SGD-denominated bonds
| Bond Name | Reset / Maturity Date (Years to Reset / Maturity) |
Ask Price | Current Yield (%) | Yield to Reset / Maturity (%) |
| CMZB 24Apr2034 Corp (SGD) | 24 Apr 2029 / 24 Apr 2034 (5.5 / 10.5) |
100* | 6.625%* | 6.625%* |
| CMZB 5.700% 03May2033 Corp (SGD) |
03 May 2028 / 03 May
2033 (4.5 / 9.5) |
100.100 | 5.744% | 5.668% / 5.948% |
Source: Bloomberg, Bondsupermart, iFAST
compilations. Data as of 16 Oct 2023. *Indicative figure as bond has not yet been issued. |
||||
To summarise, considering the decent outlook for Commerzbank, we think this new CMZB issuance appears to be fairly attractive for investment-grade bond investors looking for a slightly higher-risk alternative to other Tier 2 SGD issuances (by other banks).
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in CMZB 5.700% 03May2033 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!