-Asset quality and capital position remain broadly stable, with the non-performing loan ratio declining to 1.7%. and CET1 ratio of 14%.
- Liquidity Coverage Ratio (LCR) and Net Stable Funding Ratio (NSFR) remain well above the regulatory requirement of 100%.
- Investors should be aware that the key risks are concentration risk and liquidity risk.
- Overall, we maintain a positive stance. Investors may consider its existing issuances (as mentioned below) across different currencies, which yield in the range of 4.5%–6.8%.
Lloyds Banking Group plc (LBG) is a leading UK-based financial services group, headquartered in London with its registered office in Edinburgh. It serves more than 30 million customers through well-known brands including Lloyds Bank, Halifax, Bank of Scotland and Scottish Widows.
The Group provides a wide range of financial services, with a particularly strong position in mortgages and significant market share in credit cards, unsecured lending and commercial banking.
As of 23 March 2026, it is the UK’s second-largest bank, with a market capitalisation of approximately £54.4 billion.
Previous article update: Credit Update: Lloyds Banking Group maintains strong performance amid lower rate
Financial Highlights
In FY25, Lloyds’ total income rose modestly by 8% YoY to £19,422 million. This was largely driven by higher net interest income, despite the UK entering a rate-cutting cycle. The increase was supported by higher average interest-earning assets and an improved net interest margin, underpinned by stronger structural hedge income as eligible balances were reinvested in a higher-rate environment.
Income from other business divisions remained broadly stable. Although trading income declined to £1,485 million from £1,812 million in FY24, this was offset by higher insurance service income and other operating income.
Operating costs increased by 3% YoY to £9,800 million, reflecting ongoing strategic investment (such as higher severance costs and business growth initiatives) as well as inflationary pressures. Nevertheless, the Group’s cost-to-income ratio improved to 58.6% (FY24: 60.4%), as income growth outpaced the rise in costs, supported by disciplined cost management.
Overall, the Group reported a higher statutory profit before tax of £6,661 million. Looking ahead, we believe the bank is well positioned to sustain growth in both net interest income and net interest margin, supported by stronger structural hedge income and the potential rate hikes amid persistently elevated inflation and rising oil prices.
Table 1: Profitability indicators (£ m, unless otherwise stated)
FY2021 | FY2022 | FY2023 | FY2024* | FY2025* | |
Total income | 38,950 | (5,346) | 35,405 | 18,003 | 19,422 |
Profit before tax | 6,902 | 4,782 | 7,503 | 5,971 | 6,661 |
Net interest margin (%) | 2.54% | 2.94% | 3.11% | 2.95% | 3.06% |
Cost: income ratio | 61% | 51.10% | 54.70% | 60.40% | 58.60% |
*There were presentation changes (reclassifications) in total income in FY24 and FY25, while accounting policies remained unchanged.
Source: Company Reports, iFAST compilations. Data as of 31 Dec 2025.
Credit Metrics
1) Asset Quality
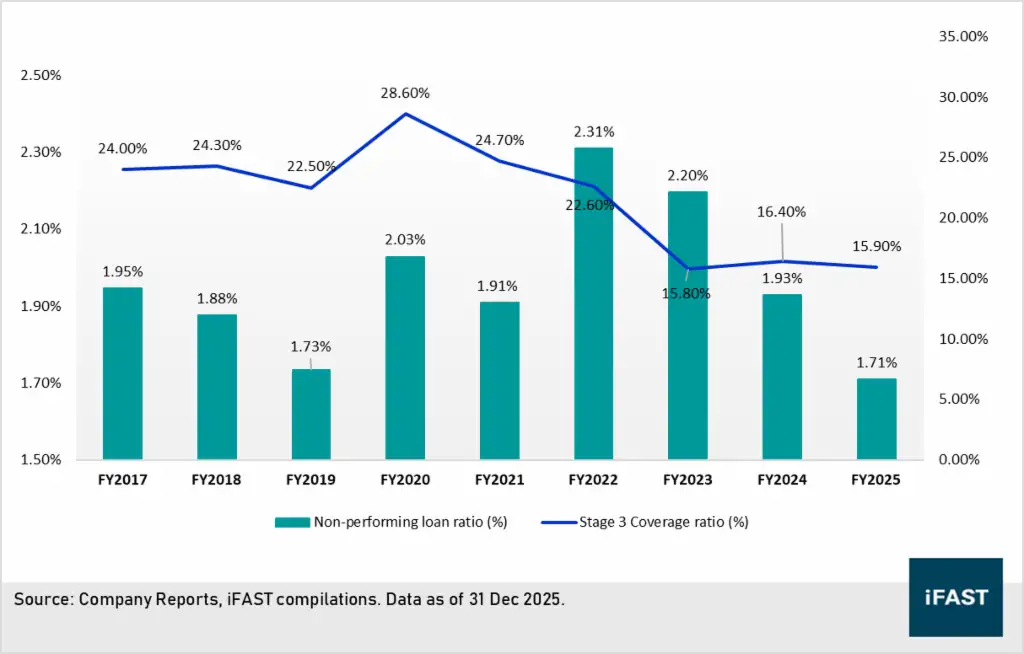
In terms of its loan portfolio, Lloyds has maintained stable and resilient credit performance across its portfolios, with the non-performing loan ratio declining to 1.7%.
In addition, the bank’s Stage 3 coverage ratio fell to 15.9%. We do not view the lower coverage ratio as indicating a weaker buffer. Rather, given that a large proportion of the loans are secured by collateral (such as property), and supported by stable housing prices, the bank is likely to achieve higher recovery values in the event of borrower default. As a result, there is lesser need to set aside additional provisions.
^Stage 3 Coverage ratio = (Provisions for stage 3 / stage 3 loans), is a measure of how much loss provisions a bank has set aside for its non-performing loans
Chart 1: Non-performing ratio and Stage 3 coverage ratio (%)
Lloyds’ asset quality ratio (AQR)* remained sound, despite a slight increase to 0.17% in FY25 from 0.10% in FY24. The rise was mainly driven by higher impairment charges.
We view this as a normalisation rather than a deterioration, as the unusually low AQR in FY24 largely reflected a one-off release of provisions, following an improved economic outlook, stronger economic performance, and rising house prices.
*Asset quality ratio = (underlying impairment charge / average gross loans and advances). The ratio measures the overall quality within a bank’s asset portfolio.
The bank’s expected credit loss (ECL) allowance—often seen as an “emergency buffer”—improved slightly to £3,353 million (FY24: £3,651 million). This was due to a reduction in Stage 3 loans (fewer defaulted loans) and a more resilient economic environment.
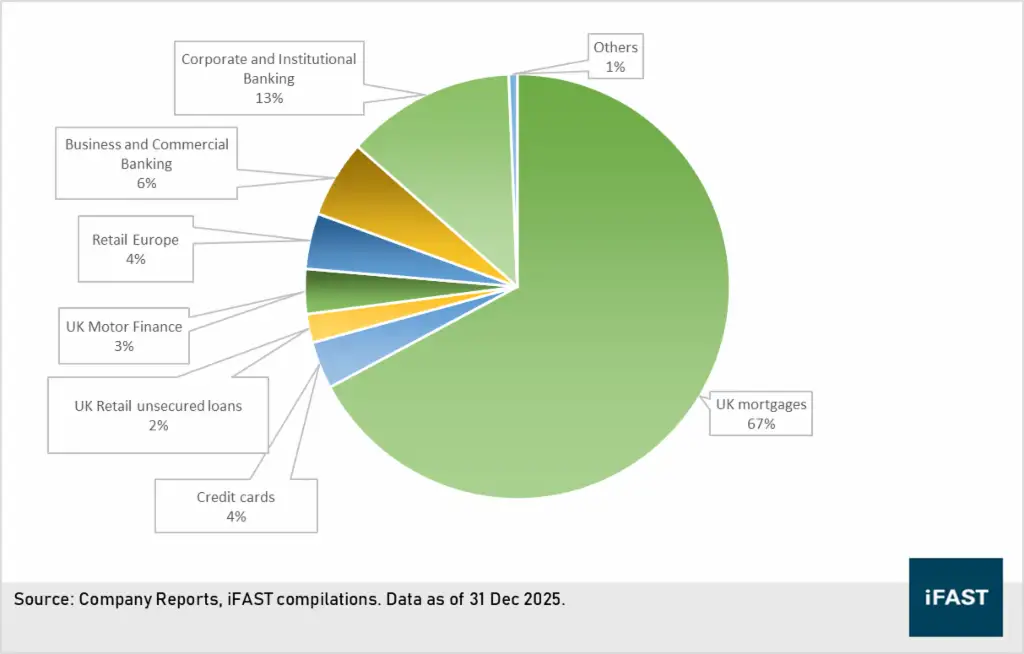
Nevertheless, investors should be aware of the inherent risks in Lloyds’ business. Around 70% of the total loan book consists of mortgages, underscoring the Group’s significant concentration risk in the UK mortgage market.
Chart 2: Loan Portfolio
2) Capital Generation
Despite a slight decline in its CET1 ratio, Lloyds continues to maintain a healthy capital position, reporting a ratio of 14% in FY25 (FY24: 14.2%). The modest reduction reflects management’s deliberate strategy, following significant returns to shareholders through dividend payouts and share buybacks in 2025.
Compared with its peers, other major banks are pursuing similar strategies, reducing CET1 ratios to enhance attractiveness by boosting return on tangible equity (RoTE). We believe Lloyds will continue its share buyback programme, targeting a CET1 ratio of around 13%—still comfortably above the regulatory minimum of 12%—to return additional capital to shareholders via dividends.
Overall, we consider the bank’s capital buffer to remain solid despite the lower CET1 ratio, leaving it well-positioned to withstand potential adverse economic conditions.
Table 2: CET1 ratio
|
FY2021 |
FY2022 |
FY2023 |
FY2024 |
FY2025 |
|
|
CET 1 ratio |
17.30% |
15.10% |
14.60% |
14.20% |
14.00% |
Table 3: Peers Comparison
Banks | FY2025 | Regulatory requirement (Internal Target) |
HSBC | 14.90% | 10.5% (Target 14-14.5%)* |
Barclays | 14.30% | 12.2% (Target: 13-14%)* |
Natwest | 14.00% | 10.3% (Target: 13 - 14%)* |
Standard Chartered | 14.10% | 10.3% (Target: 13-14%)* |
Lloyds | 14.00% | 12% (Target: 13.0%)* |
*Internal Target
Source: Company Reports, iFAST compilations. Data as of 31 Dec 2025.
3) Funding / Liquidity
There were not much updates since our previous article in September 2025. Overall, the bank’s balance sheet remains relatively stable, with its loan-to-deposit ratio still maintaining above 95%.
Liquidity Coverage Ratio (LCR) and Net Stable Funding Ratio (NSFR) remain well above the regulatory requirement of 100%.
Recent Incident:
1) Lloyds – added £800 million provision for FCA Motor Finance Commission Review
As mentioned in our previous article, Lloyds, along with other banks, was involved in a motor commission review. In 3Q25, Lloyds added a further £800 million, bringing its total provision to £1.95 billion. The bank made this provision to prepare for a worst-case scenario and the possibility of a substantial fine.
In August 2025, the Supreme Court overturned the ruling on car finance commissions, deciding that car dealers do not owe fiduciary duties to customers when arranging car loans. This reduces the likelihood of banks facing large-scale compensation claims related to commissions paid to dealers, although some claims for overcharging may still arise. The FCA is currently developing a plan to compensate customers who were treated unfairly, but banks may not need to pay as much as initially feared.
As a result, Lloyds could potentially reverse part of its provision, given that the risk of significant compensation claims has now diminished.
2) Technical Glitch
In March 2026, Lloyds’ mobile and online banking systems (which also serve the Halifax and Bank of Scotland brands) experienced a technical glitch where some customers briefly saw other people’s transaction details when logging into the banking app or internet banking. This included the ability to view transaction information that did not belong to them.
UK lawmakers are now pressing Lloyds for detailed answers. The Chair of the UK Parliament’s cross‑party Treasury Committee has written to the bank’s CEO seeking explanations about what caused the glitch, how many customers were affected, what type of data was exposed and whether compensation might be offered.
As of the date of writing (23 Mar 2026), no formal penalties or fines have been announced by the regulators.
Risks to consider
High concentration in UK market: Unlike many of its peers, Lloyds Banking Group has limited geographical diversification, with its business largely concentrated in the UK. As a result, the group’s performance is heavily tied to the performance of the UK economy, making its earnings less diversified compared to international peers such as HSBC.
Liquidity risk: Lloyds’ loan-to-deposit ratio is relatively high. While this reflects efficient use of deposits, it also indicates a potential vulnerability: in the event of significant deposit withdrawals or a bank run, the Group could face financial strain.
Our view
The bank’s operating performance remains resilient, supported by higher average interest-earning assets, improved margins, and stable asset quality.
Despite the motor finance commission review, we maintain a positive view, as the bank’s capital and liquidity positions remain strong enough to absorb potential headwinds, including any residual impact from this issue.
That said, investors should be aware of certain risks. Lloyds’ heavy concentration in the UK market makes it more sensitive to domestic economic shifts compared with more diversified peers. In addition, its relatively high loan-to-deposit ratio, while reflecting efficient use of deposits, could expose the Group to liquidity pressures in the event of sudden funding outflows.
Overall, despite exposure to certain risks, Lloyds’ performance remains solid. We have prepared the following list of recommendations.
For AUD, investors may consider LLOYDS 7.086% 31Aug2033 Corp (AUD) and LLOYDS 5.189% 28May2031 Corp (AUD) as the yield pickup is appealing, at around 6% and 5.8% respectively.
For USD, investors may consider LLOYDS 3.574% 07Nov2028 Corp (USD) and LLOYDS 6.068% 13Jun2036 Corp (USD), yielding at around 4.51% and 5.75%.
For GBP, investors may consider LLOYDS 2.000% 12Apr2028 Corp (GBP), yielding at around 5% level. Additionally, LLOYDS 7.500% Perpetual Corp (GBP) could also be a good choice, as we believe the risk–reward profile is justified with yield to call of approximately 7.5%. However, investors should be aware of the features / risks associated with perpetual bonds (e.g., interest deferral).
Table 4: Recommended bonds***
Bonds | Years to next call / Years to maturity | Yield to next call / Yield to maturity |
2Y5M / 7Y5M | 6% / 6.80% | |
- / 2Y2M | - / 5.49% | |
2Y / 3Y | 5.63% / 5.86% | |
4Y2M / 5Y2M | 5.8% /5.82% | |
1Y8M / 2Y8M | 4.51% / 5.1% | |
9Y2M / 10Y2M | 5.75% / 5.77% | |
3Y6M / - | 6.25% / - | |
5Y6M / - | 6.76% / - | |
1Y / 2Y | 5.02%/ 5.27% | |
4Y3M | 7.57% | |
2Y | 6.14% |
Source: Bloomberg, BSM, iFAST Compilations. Data as of 24 Mar 2025.
***Availability and yield subject to market conditions
Investors have to note that LLOYDS 7.086% 31 Aug 2033 Corp (AUD) and LLOYDS 6.068% 13Jun2036 Corp (USD) are Tier 2 bond, the seniority is 1 rank higher than AT1 securities.
And the above perpetuals are AT1.
There are few things that investors should also be aware of:
1) We would like to highlight that, due to the loss absorption feature inherent in Tier 2 bonds and AT1, these instruments may not be suitable for risk-averse investors.
2) Issuer has the right to call back the bond in a future date before the maturity, otherwise there will be a reset rate (please refer to the bond factsheet for the reset rate).
Nevertheless, we expect the issuer to call back its Tier 2 securities on the first call date. Under the Basel III framework, Tier 2 securities that remain uncalled after this date are subject to amortisation. As a result, banks are incentivised to redeem their Tier 2 securities promptly.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds LLOYDS 7.086% 31Aug2033 Corp (AUD) and the analyst who produced this report holds a NIL position in the abovementioned securities.