ESR Real Estate Investment Trust (“ESR-REIT”) is launching new senior bonds since acquiring Cambridge Industrial Trust in 2017. The notes will be unsubordinated and unsecured with an initial price guidance (“IPG”) of 2.75% and carry a tenor of 5 years.
The bond offering comes on the back of a preferential offering, which was launched yesterday at 40 Singapore cents per unit. The trust is looking to raise up to SGD 50m through the preferential offering.
About the unsecured notes
ESR-REIT is launching direct, unsubordinated, unsecured notes under the SGD 750m Multicurrency Debt Issuance Programme (“MTN program”). The tenor will be 5 years and bondholders will receive a semi-annual coupon payment. The use of proceeds from the issuance will be used to refinance existing borrowings, fund investments of ESR-REIT, development and asset enhancement works and finance general working capital as well as other capital expenditure requirements.
The terms and conditions of the offering are in accordance to the issuer’s MTN program dated 12 September 2019. As long as the notes remains outstanding, the issuer will be subjected to negative pledge covenants. Furthermore, bonds may also be redeemed in taxation events or upon the cessation of trading of the units.
About the Issuer
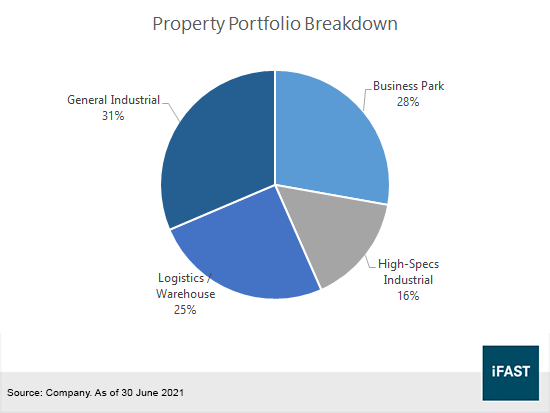
ESR-REIT is an industrial REIT based in Singapore with a property portfolio of 58 properties across Singapore. Properties within their portfolio have a total gross floor area of approximately 15.6m square feet and an aggregate property value of SGD 3.2b. The properties are in the following business sectors: Business Park, High-Specs Industrial, Logistics/Warehouse and General Industrial.
ESR Funds Management Limited is the Manager of ESR-REIT, owned by ESR Cayman Limited (67.3%), Shanghai Summit Pte. Ltd. (25.0%), and Mitsui & Co., Ltd (7.7%). ESR Cayman wholly owns ESR Property Management (S) Pte. Ltd., which provide property management services to ESR-REIT.
Figure 1: Property Portfolio Breakdown
For the half-year period ended 30 June 2021 (“1H21”), the REIT achieved a property occupancy rate of 91.7%, an increase from 90.8% from the previous quarter ending 31 March 2021. Occupancy rate is above the JTC average of 90.0% and also above pre-COVID levels. Year-to-date (“YTD”) rental reversion was at -1.6%, and represents an improvement from the previous year YTD 2Q20 of -4.3%. The lower rental rents was primarily due to lower renewal rents of larger tenants in the business parks. Rental reversions for 2Q21 was at -0.2% as high-specs, logistics and general industrial sectors contributed positive reversions.
Financial Highlights
Gross revenue increased to SGD 119.8m in 1H21, 5.4% higher than 1H20, mainly due to the absence of provision for COVID-19 rental rebates to tenants in 1H21. Net property income (“NPI”) increased to SGD 87.0m, an increase of 8.4% as compared to the prior financial year. The increase in NPI is attributed to higher gross revenue and lower property expenses. Tenants consumed lower electricity and lower electricity rates were re-contracted for some properties for 1H21.
Additionally, the REIT recognized lower maintenance costs compared to 1H20 due to the implementation of COVID-19 safety measures last year such as temperature screening and sanitisation procedures. These measures have been scaled back in accordance with the gradual relaxation of the requirements by the Singapore Government.
ESR-REIT made several acquisitions for the first half of 2021. On 14 May 2021, ESR-REIT completed the acquisition of 10.0% of the total issued units in ESR Australia Logistics Partnership (“EALP”). On 29 June 2021, ESR-REIT completed the acquisition of its sixth modern ramp-up logistics property, located at 46A Tanjong Penjuru, Singapore 609040, and has a total of 12 logistics properties.
Credit Profile
Total gross debt amounted to SGD 1,306.6m in 1H21 from SGD 1,186.0m in FY2020. ESR-REIT has SGD 78.1m of undrawn committed facilities available for use and a debt headroom of SGD 463.2m. ESR REIT has a well-managed debt profile with a healthy gearing of 42.9% (debt to total asset ratio), which is below the MAS regulatory limit of 50% for REITs.
Figure 2: Debt maturity profile
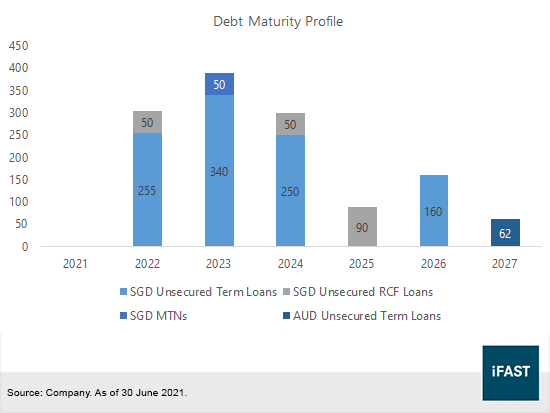
Additionally, ESR REIT has a well spread debt maturity profile, with their weighted average debt expiry of 2.6 years. The company has also refinanced all existing debt due in FY2021 ahead of expiry. The company is looking to start early refinancing of its FY2022 debt with this new bond issue.
Liquidity for the company is also well managed with cash flow from operations of SGD 77.49m. Interest coverage ratio as at 30 June 2021 was 2.8 times as compared to 2.6 times as at 31 December 2020. The increase in interest coverage ratio provides the company the financial flexibility to increase leverage to above 45% due to new MAS regulations. MAS had proposed to require S-REITs to have a minimum ICR of 2.5 times before they are allowed to increase their leverage to beyond the prevailing 45% limit (up to 50%).
We feel ESR-REIT’s debt position to be favourable in the current economic climate as debt is well managed. ESR-REIT has a healthy gearing and adequate liquidity to service its expiring short-term debt. Additionally, there is some allowance for the company to take on more debt should it need for acquisitions or other working capital needs.
Bond Valuation
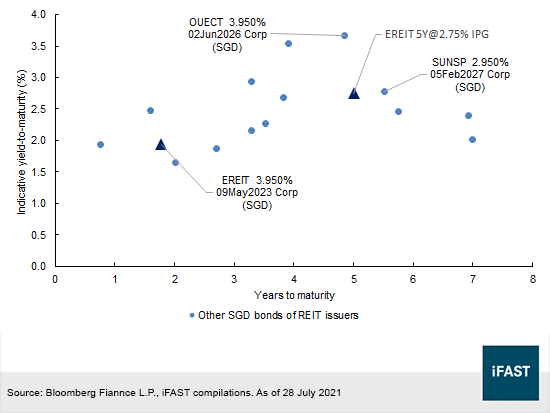
With a credit spread of 192.5 basis points (“bps”) above the prevailing 5-year Swap Offer Rate, we feel that the new bonds from ESR-REIT are fairly priced at its initial price guidance of 2.75%. The 2.75% IPG is 81bps higher than the EREIT 3.950% 09May2023 Corp (SGD), which has an indicative yield-to-maturity (“YTM”) of 1.93%. On a relative value basis, the 2.75% IPG is also more attractive than the SUNSP 2.950% 05Feb2027 Corp (SGD), that is trading at a YTM of 2.77% with 5.5 years of maturity. To find more about Suntec REIT, investors may refer to “Suntec REIT launches new SGD NC5 perps at 4.45% IPG”.
Investors who are looking for a higher yielding issue from an issuer with a smaller portfolio in commercial properties may consider the OUECT 3.950% 02Jun2026 Corp (SGD), which we had elaborated on in our earlier article – “OUE Commercial REIT offers new 5-year SGD bonds at 4.15% IPG”.
Figure 3: Relative valuation among SGD fixed maturity notes of REIT issuers
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in SUNSP 3.800% Perpetual Corp (SGD), OUECT 3.950% 02Jun2026 Corp (SGD), ESRCAY 5.65% Perp Corp (SGD), ESRCAY 6.750% 01Feb2022 Corp (SGD), ESRCAY 7.875% 04Apr2022 Corp (USD) and OUESP 3.750% 17Apr2022 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!