


First Sponsor Group Limited has returned to the bond market after a nearly three-year hiatus, since the company redeemed its last notes in June 2017. We provide a quick introduction on the company, its recent financial performance, and our thoughts on the bond pricing.
About First Sponsor
First Sponsor Group Limited is a real estate company headquartered in Singapore, with business exposures mainly in the Netherlands, Germany, Australia, and China. The group is listed on the SGX since 2014, sporting a market cap of S$1.07 billion as at yesterday’s market close.
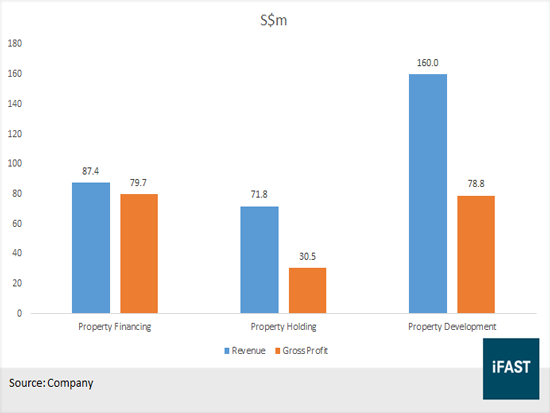
First Sponsor has three primary business lines, namely property development, property holding, and property financing. Property development continued to be the company’s biggest revenue contributor in 2019 (see Figure 1), followed by its property financing and property holding businesses. Although the reported 2019 gross profit of First Sponsor’s property development segment was marginally lower than property financing, we note that the company reported S$71.2m in its share of after-tax profit of associates and joint ventures (“JV”), which was attributable to its property development business.
Figure 1: 2019 revenue and gross profit breakdown by segments
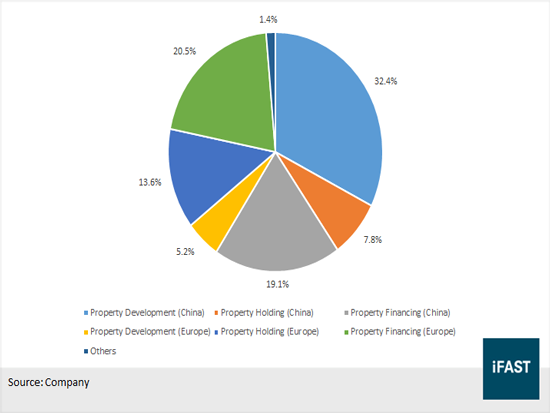
In terms of First Sponsor’s geographical exposure, some 59% of the group’s assets are in China (see Figure 2), comprising mostly of its property development (32.4%) and property financing (19.1%) interests. We understand that First Sponsor has six ongoing development projects in China, with five in Dongguan, Guangdong, and one in Chengdu, Sichuan. The group’s European portfolio mainly comprises of office buildings and hotels in Germany, Italy, and the Netherlands, as well as property financing loans to its European associates and JVs. First Sponsor also owns a 39.9% stake in a project development trust that will redevelop the 125-year old City Tattersalls Club in Sydney, Australia, into a hotel and residential apartments.
Figure 2: First Sponsor’s assets by business and geographic segments
We think First Sponsor enjoys good institutional support due to the financial strength and track record of the company’s sponsors. About 81% of the company’s shares are controlled by two shareholders, namely the Hong Leong group of companies (through its shareholding interests in City Developments Limited) and Tai Tak Estates Sendirian Berhad. Tai Tak Estates is the holding company of Singapore’s Ho family, which also owns stakes in United Overseas Bank, Carlsberg Brewery Malaysia, Heineken Malaysia, and Cordlife Group.
Credit highlights
Given First Sponsor’s relatively young operating history (the company was incorporated in September 2007), the company still has a developing scale, with just S$319.2m of revenue in 2018. Revenue climbed 15.1% YoY in 2019 (2018: S$277.4m) as all three business segments registered growth. Property development (+S$20.6m of revenue in 2019) was the biggest growth driver following the recognition of revenue from the handover of more commercial and residential units in the Chengdu Millennium Waterfront project. Meanwhile, revenue from hotel operations increased by S$18.7m or 45% due to the additional contribution from Bilderberg Bellevue Hotel Dresden and Hampton by Hilton Utrecht Centraal Station.
Gross profit grew correspondingly to S$189.0m in 2019 (2018: S$161.5m), representing an improved gross profit margin of 59.2% (2018: 58.2%). We think First Sponsor’s impressive profitability reflects its solid execution and prudent growth strategy that balances business expansion and profitability.
Other expenses ballooned to S$61.9m (2018: other income of S$3.3m) after First Sponsor recognized S$46.2m of impairment loss on the Crowne Plaza Chengdu Wenjiang hotel and the adjoining hot spring, and S$27.4m of net foreign exchange loss. On the other hand, the group recorded other gains of S$42.8m (2018: S$2.8m), which comprised mainly gain from the partial disposal of its interest in the Oliphant office building in Amsterdam (S$35.5m) and certain commercial spaces of the Chengdu Cityspring project classified as held-for-sale assets (S$7.7m).
As mentioned earlier, First Sponsor reported a share of after-tax profit of associates and JVs of S$71.2m in 2019, as compared to just S$5.5m in 2018. S$43.8m of this amount was attributable to the 30%-owned Star of East River project, following the handover of six residential blocks in 2019. The group’s attributable share of fair value gain on the Oliphant property (held by a 33%-owned associate) of S$22.5m also boosted its share of results in 2019. Overall, First Sponsor achieved a record pre-tax profit of S$194.2m in 2019, up 34.3% YoY from 2018 (S$144.5m).
Finance costs jumped to S$22.9m in 2019 (2018: S$9.9m), which we think was likely partly due to the first-time adoption of IFRS 16 requiring the recognition of interest expense on lease liabilities. Nevertheless, we note that First Sponsor continued to record sizeable finance income from its substantial cash balance and financial derivatives (which as we understand were entered into with the purpose of hedging the group’s foreign exposures). With a finance income of S$23.8m (2018: S$17.1m), First Sponsor registered net finance income of S$0.9m in 2019 (2018: S$7.2m).
First Sponsor’s reported net gearing (net debt over equity) remained low at just 0.20x as of end-2019, down from 0.40x a year ago. Based on our own calculations, we estimated that the group’s debt-to-total capital ratio (including lease liabilities) was 0.30x at the end of 2019 (31 Dec 18: 0.35x), indicating a strong balance sheet. However, due to its still developing scale, First Sponsor’s revenue-to-debt ratio (including lease liabilities) was just 46% in 2019, suggesting that the company still has much work to do in growing its revenue to match its indebtedness.
Cash and cash equivalents rose from S$125.7m to S$313.4m in the twelve months ended December, following First Sponsor’s rights issue of up to S$147.6m of perpetual convertible capital securities. Besides its sizeable cash holdings, First Sponsor enjoys a strong liquidity position from its access to S$410.2m of mostly committed credit facilities.
The management guided that it was still premature for them to ascertain the full financial impact from the coronavirus outbreak in Wuhan, although they anticipated “some impact” on parts of First Sponsor’s operations. As highlighted earlier, we understand that the group’s development projects in China are mainly located in Dongguan, Guangdong. Guangdong province has the second highest number of coronavirus cases in mainland China after Hubei, the province where Wuhan is located.
Bond pricing
First Sponsor has launched new SGD five-year senior unsecured notes at the initial price guidance (“IPG”) of 3.4%, which indicated a spread of around 187 bps above five-year SGD swap rates (as at 12 Feb 20). We can compare the IPG of First Sponsor’s new issue with other real estate credits with substantial China exposure in the SGD space.
Overall, we think the IPG of 3.4% is fair, placing the bond valuation somewhere between Metro Holdings and First Sponsor’s key shareholder, City Developments. As a reference, Metro Holdings’ 4.3% notes due 2024 are yielding 3.73% for a spread of 220 bps above SGD swaps. City Developments’ 2.7% notes due 2025 are indicated at a yield to maturity of 2.60%, for a spread of 106 bps above SGD swaps.
We note that Metro Holdings has a larger business exposure to China, with its China operations constituting 85.9% of its non-current assets and 74.3% of profit from operations before tax in the company’s latest financial year. Also, Metro Holdings’ operating scale is significantly smaller and its profitability weaker. On the other hand, the company’s leverage is lower with its net gearing and debt-to-total capital ratios (both including lease liabilities) at 14% and 23% respectively at the end of September.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a NIL position in the abovementioned securities. The analyst who produced this report owns shares in City Developments Limited.










