


- Total revenues for the fiscal year ended 30 June 2021 (“FY21”) decreased 9% year on year (“YoY”) to SGD 853.7m, while gross profit also fell by 10% to SGD 268.4m.
- GUOLSP has 8 major development projects in its pipeline, most of which are expected to be completed in phases between 2022 and 2024.
- Cash flows for GUOLSP turned positive in FY21 as cash from operations amounted to SGD 388.2m as compared to a net cash used from operations of SGD 731.9m in FY20.
- Among GUOLSP notes, we recommend the GUOLSP 3.400% 10Aug2025 Corp (SGD) with an indicative yield to maturity of 2.95%.
GuocoLand Limited (“GUOLSP”) made the news when it sold the most expensive penthouse in Singapore in 2019. With the newly imposed property cooling measures in Singapore, property developers may face additional headwinds in property sales against the backdrop of Covid-19 and rising interest rates.
We will take a look at GUOLSP’s financial performance and provide our recommendations to investors on whether the GUOLSP notes are still a buy after the announcement of the property cooling measures.
GuocoLand Limited was incorporated in Singapore in 1976, it became a publicly traded company in 1978 and has a market capitalisation of SGD 1.74b at 22 December 2021. Guoco Group Limited is the intermediate holding company that is listed on the Hong Kong Stock Exchange with a market cap of HKD 27.8b. Guoco Group is a member of the Hong Leong Group, a large conglomerate with many listed firms in Singapore, Malaysia, Hong Kong and London. Historically, GUOLSP has had contractual arrangements with the Guoco Group over the course of its business.
GUOLSP’s FY21 Financial Results
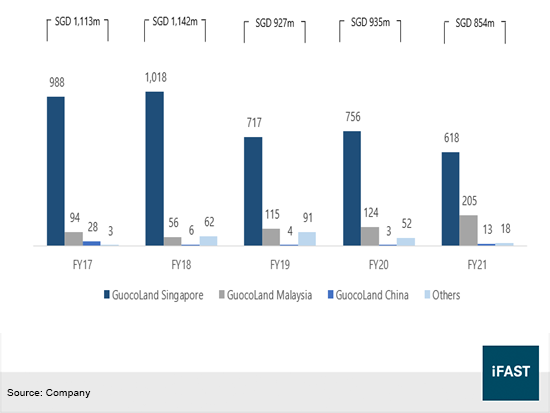
Total revenues for the fiscal year ended 30 June 2021 (“FY21”) was SGD 853.7m, representing a decrease of 9% year on year (“YoY”) while gross profit also fell by 10% to SGD 268.4m. The fall in revenue was partly attributable to lower progressive recognition of sales from Singapore residential projects. Martin Modern obtained its Temporary Occupation Permit in May 2021 and contributed lesser to revenue as it reached its tail end during the financial year.
From Figure 1, GuocoLand Singapore contributed 72.4% of total revenues for FY21 while GuocoLand Malaysia contributed 24.0% and GuocoLand China 1.5%. For GuocoLand Malaysia, revenues increased by 65.3% YoY and was due to higher sales in development properties and also from the disposal of a land parcel in Jasin, Melaka. The segment also turned a profit as compared to a loss in FY20.
GuocoLand China continues to be loss making with a loss before tax of SGD 17.8m. Revenues from the remaining sale of development property in China could not be recognised until construction and handing over of the units to the buyers is completed. Guoco Changfeng City is expected to be completed in 3Q 2022 and GUOLSP plans to retain one office tower and the basement retail units for recurring rental income.
Figure 1: GUOLSP’s FY21 revenue by business segment (in SGD m)
Group profit before tax saw an increase of 53.8% to SGD 239.9m in FY21, mainly due to a decrease in the fair value loss on derivative financial instruments. From Figure 2, profit for GUOLSP has largely seen a downward trend, with profit before tax dipping 36.2% YoY in FY19 when compared to FY18.
On 16 December 2021, the Singapore government raised the additional buyer’s stamp duty for Singapore citizens, permanent residents and foreigners. The total debt servicing ratio (“TDSR”) threshold for obtaining loans was narrowed to 55% from 60%. This may affect future home sales due to the tightening of TDSR as it affects the buyers’ ability to get a loan to purchase additional property to rent or stay.
Figure 2: GUOLSP’s profits (in SGD m)
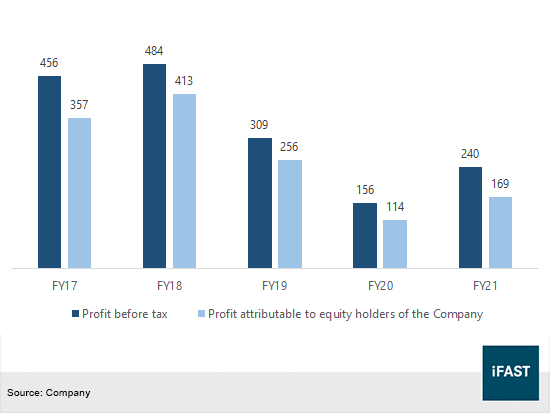
Figure 3: Residential property price index by type
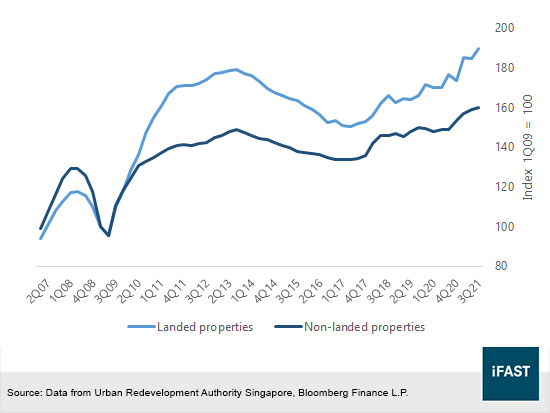
From Figure 3, property prices fell slightly before rebounding after the property cooling measures in 2018. We think property prices would not be significantly impacted in the long run due to the cooling measures. Home sales may decrease in the first few quarters of next year due to the measures. However, most of GUOLSP’s projects that are expected to be completed next year have been sold as seen from Table 1. Thus, we believe that the cooling measures will not have a large impact on GUOLSP’s revenue.
Table 1: GUOLSP’s pipeline of prominent development projects in Singapore
|
Project |
Units sold |
Completion Status |
|
Wallich Residence |
71% |
Completed |
|
Martin Modern |
94% |
Completed |
|
Midtown Modern |
67% |
Under construction, to be completed by 2024 |
|
Midtown Bay |
29% |
Under construction, to be completed in 2023 |
|
Meyer Mansion |
33% |
Under construction, to be completed in 2024 |
|
The Avenir |
24% |
Under construction, to be completed in 2024 |
| Source: Company. | ||
As of 30 June 2021, GUOLSP has 8 major development projects in its pipeline, most of which are expected to be completed by 2025. SGD 3.11b of revenue from development projects are to be recognised over the next few years of which SGD 1.66b are to be recognised over time and SGD 1.45b are to be recognised at a point in time. There are 4 development projects expected to be partially completed and accretive to revenue progressively in 2022.
Given the pipeline of future property development projects currently in progress, we expect GUOLSP to see healthy cash flow and revenue moving forward. In their GuocoLand China segment, revenues are expected to stream in between 2022 and 2024 which will provide a boost to the lost making segment.
Table 2: GUOLSP’s pipeline of major development projects
|
Development Project |
Country |
Tenure |
Expected date of completion |
Gross Floor Area (Sq m) |
Group’s Effective Interest (%) |
|
Guoco Midtown |
Singapore |
99-Year Lease With Effect From 02.01.2018 |
In phases from 4th Quarter 2022 to 2nd Quarter 2023 |
90,029 |
70.00 |
|
Midtown Modern |
Singapore |
99-Year Lease With Effect From 10.12.2019 |
3rd Quarter 2023 |
48,430 |
60.00 |
|
Meyer Mansion |
Singapore |
Freehold |
2nd Quarter 2024 |
22,175 |
100.00 |
|
Lentor Central |
Singapore |
99-Year Lease |
2nd Half of 2022 |
~60,480 |
100.00 |
|
Guoco Changfeng City |
People’s Republic of China |
50-Year Land Use Rights With Effect From 11.12.2005 |
In phases from 3rd Quarter 2021 to 3rd Quarter 2022 |
146,552 |
100.00 |
|
Chongqing GuocoLand 18T |
People’s Republic of China |
Residential: 50-Year Land Use Rights Till 29.06.2069 Commercial: 40-Year Land Use Rights Till 29.06.2059 |
In phases from 2nd Quarter 2023 to 4th Quarter 2024 |
341,080 |
75.00 |
|
Chongqing Central Park |
People’s Republic of China |
Residential: 50-Year Land Use Rights Till 2070 |
TBA |
197,600 |
75.00 |
|
Emerald 9 |
Malaysia |
Freehold |
Plot 1: 2nd Quarter 2023 Plot 2: TBA |
287,235 |
68.00 |
|
PJ Corporate Park |
Malaysia |
Leasehold Till 12.12.2107 |
TBA |
38,053 |
68.00 |
|
Emerald Hills |
Malaysia |
Freehold |
In phases from 2nd Quarter 2022 to 1st Quarter 2025 |
245,980 |
68.00 |
|
Vacant Agriculture Land |
Malaysia |
Freehold |
TBA |
7,474,840 |
46.24 |
| Source: Company FY21 annual report, iFAST compilations. | |||||
Liquidity and credit profile
Liquidity for GUOLSP is healthy with cash and cash equivalents of SGD 1.13b, of which; (i) SGD 214.8m are held under Singapore Housing Developers Rules; (ii) SGD 125.5m under the China Housing Developers Restricted Funds Agreement; (iii) SGD 3.9m under Malaysia’s Housing Development Act; (iv) SGD 5.8m of cash collaterals with financial institutions in Singapore for bank loans. Therefore, among the SGD 1.13b in cash and cash equivalents, SGD 350.0m are restricted cash and SGD 779.29m are unrestricted cash and term deposits.
Cash flows for GUOLSP turned positive in FY21 as cash from operations amounted to SGD 388.2m as compared to a net cash used from operations of SGD 731.9m in FY20. Gearing for the company also dropped YoY. In Figure 3, net debt to equity fell to 0.90 in FY21 compared to 1.02x the year prior.
Figure 4: GUOLSP’s equity and net debt
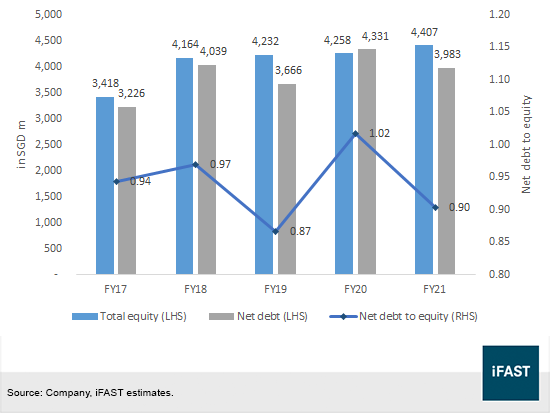
Total borrowings for FY21 was SGD 5.11b, of which SGD 947.4m are short term borrowings. With its cash position, GUOLSP has enough cash (including restricted cash) to cover its short term borrowings, with cash to short term debt at 1.19x. As compared to other property developers, GUOLSP is more leveraged with a net debt to equity of 90.00%. However, we think given the pipeline of future projects and also its current cash balance, GUOLSP will have sufficient cash flows to pay back its debt obligations.
Table 3: Estimated credit ratios of comparable property developers
|
As of Jun 2021 |
Net debt/ |
Net debt/ |
Interest coverage ratio (x) |
|
GuocoLand Ltd |
90.00 |
45.20 |
~1.94 |
|
Frasers Property Ltd |
73.68 |
33.55 |
4.0 |
|
City Developments Ltd |
98.56 |
37.19 |
2.5 |
|
UOL Group Ltd |
28.75 |
19.83 |
12.0 |
|
OUE Ltd |
39.91 |
25.91 |
2.1 |
| Source: Company filings, Bloomberg Finance L.P. estimates, iFAST estimates. As of 30 June 2021. | |||
From Table 3, GUOLSP is more leveraged as compared to peers with a net debt to equity of 90.00%. The company has a net debt to total assets of 45.20%. Other than the Housing Developers (Control and Licensing) Act that requires certain subsidiaries of the Company to maintain a minimum paid-up capital of $1,000,000, the Company and its subsidiaries are not subject to externally imposed capital requirements.
Given its cash balance and healthy cashflows, GUOLSP is able to pay down its debt obligations. With an interest coverage ratio of ~1.94, earnings from the company is able to pay down its financing costs and future pipeline of development projects will provide a steady stream of income to the company.
Relative Valuation
Figure 5: Relative valuation among SGD property developer issues
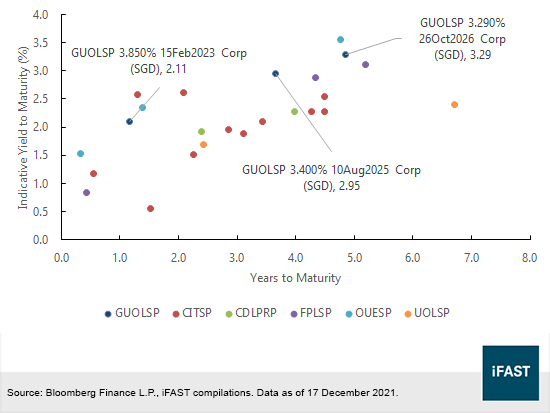
In Figure 5, taking a look at the relative valuation of GUOLSP’s issuances among other property developer issues, we see that the yield curve for GUOLSP sits above other SGD property developer bonds. This is likely due to GUOLSP being more leveraged as compared to its peers as seen from Table 2.
Among GUOLSP notes, we recommend the GUOLSP 3.400% 10Aug2025 Corp (SGD) with an indicative yield to maturity of 2.95%. Among the notes maturing between 2-4 years, the GUOLSP 3.4% 2025’s offer the highest yield to maturity.
We think that given GUOLSP’s liquidity and future pipeline of development projects, GUOLSP will be able to pay its future debt obligations and it is recommended for investors who seek a stable income for the next 3 years.
Figure 6: Relative valuation among other real estate perpetual notes
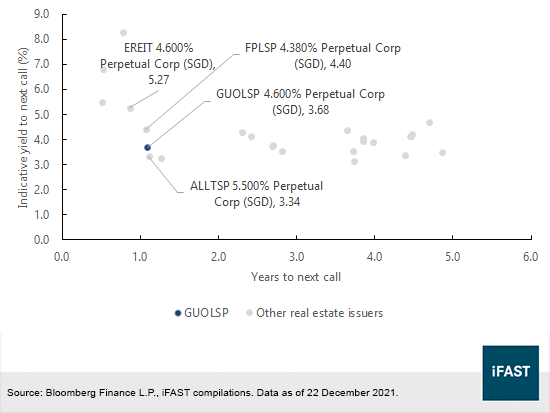
Among perpetual notes issued by other real estate issuers (property developers and REITs), GUOLSP 4.600% Perpetual Corp (SGD) has a yield to next call (“YTC”) of 3.68% with about 1 year to its call date on 23 January 2023. However, the FPLSP 4.380% perpetual notes look more attractive in comparison providing a higher YTC of 4.40%. Additionally, FPLSP’s is less leveraged as compared to GUOLSP as seen from Table 3 and has a higher cash position of SGD 3,776.7m, making FPLSP a less risky option in comparison.
Conclusion
The property cooling measures in Singapore will affect home sales in the first half of 2022 but they are unlikely to put a dent to home prices. A majority of GUOLSP’s completed projects have been sold thus we believe that the cooling measures will not have a large impact on GUOLSP’s revenue. With a healthy amount of projects in its pipeline, GUOLSP will continue to see cash flows coming in from the completion of these projects. We recommend the GUOLSP 3.400% 10Aug2025 Corp (SGD) with an indicative yield to maturity of 2.95% as it provides the most attractive yield for notes maturing within 2 to 4 years when compared to other property developers.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in GUOLSP 3.290% 26Oct2026 Corp (SGD), FPLSP 4.980% Perpetual Corp (SGD), OUECT 3.950% 02Jun2026 Corp (SGD) and OUECT 3.950% 02Jun2026 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









