On Oct 14, Heeton Holdings Limited announced an exchange offer exercise, inviting holders of the company’s 6.08% notes due 2021 to exchange their bonds for a new issue. Bondholders have until Oct 26 for early exchange and Oct 30 to finalise their decision.
Bondholders who participate in the exchange offer will receive the new issue with principal amount of S$200,000, S$50,000 cash, accrued interest and an exchange fee of S$1,000 (0.40% for early exchange) or S$500 (0.20% for exchange submitted after the early exchange deadline). The new issue will have a minimum coupon rate of 6.8% and mature in November 2023.
Assuming Heeton redeems the 6.08% notes due July 2021, bondholders would receive S$261,400 in principal and interest if they hold onto the existing bond, or S$261,200 and savings of fees (from buying the new notes) if they opt to exchange (from the time of this article’s writing to July 2021). With seemingly similar pay-offs, we will examine other factors that help with noteholders’ decision-making.
Looking at the outstanding amount of the HTONSP 6.080% 19July2021 Corp (SGD), the amount of insider holdings and Heeton’s liquidity, we believe the firm needs holders of at least S$39 million in principal amount to exchange their bond. This is assuming Heeton would not have to turn to asset disposals or external funding sources to meet the bond redemption. However, this assumption would mean Heeton completely depleting its cash. Heeton’s management has indicated that they hope to exchange at least S$70 million worth of existing bonds.
Table 1
Estimated amount of bonds required
for exchange
|
S$ '000 |
|
|
Outstanding amount |
117,750 |
|
Cash balances |
- 58,569 |
|
Management’s holdings (and likely reinvestment) |
-5,600 |
|
Unused credit line |
-15,000 |
|
Remaining amount |
38,581 |
|
Source: Heeton Holdings, iFAST estimates |
|
On the other hand, the exchange offer exercise is also not Heeton’s only alternative of freeing up liquidity. We understand that the group is also looking to divest three of their properties – Adam House (the UK), 62 Sembawang Road (Singapore) and a property in Australia. These three properties could fetch at least S$65 million in proceeds.
The residential development, Park Colonial, is also due for completion in 2021. According to management, Heeton has S$70 million of equity invested in the project, so its sales will be a welcome boost to the company’s liquidity. However, due to complications arising from COVID-19, its expected completion date has been delayed from 1Q21 to end-2021. As such, the majority of sales proceeds may not arrive in time for the redemption of the HTONSP 6.08% ‘21s.
The divestment of the three properties mentioned above would allow time for Heeton’s operations to normalise. In 1H20, its revenue decreased by 56.6% YoY to S$12.66 million from S$29.15 million a year ago. A major portion of the decline was due to lockdown measures in the UK as the group has a number of hotels in the UK. Three months of zero occupancy (from April to June) resulted in a decrease in hotel operation income of S$9.23 million. There were no residential sales in 1H20 too, while rental rebates were given to tenants, thus further decreasing revenue. All in all, the group suffered a loss of S$8.9 million before tax.
In 1H20, the group’s cash and cash equivalents decreased from S$116.92 million to S$58.57 million due to the repayment of S$75 million notes in May. Net bank loan proceeds of S$24.12 million helped with the liquidity position.
Looking forward, things should improve. Only one out of eleven of Heeton’s hotels remained closed, and occupancy rates for the firm’s hotels in the UK are reaching 80-90% during weekends. If the situation in the UK were to worsen again, Heeton’s management estimated a loss of GBP 100,000 per month, under a full lockdown scenario in the UK.
Heeton has eight hotels operating in the UK, two in Thailand and one in Japan. Thus, if the UK enters another lockdown, a large portion of its revenue will be lost. Although Heeton’s operating profits might not be as low as 1H20, it would still be a significant hit on its cash balances.
Table 2
Liquidity analysis
|
S$'000 |
|
|
Outstanding amount of bonds |
117,750 |
|
Loans to be repaid next year |
34,850 |
|
Asset disposals |
-65,000 |
|
Cash and cash equivalents |
-40,000 |
|
Unused credit line |
-15,000 |
|
Management’s bond holdings (and likely reinvestment) |
-5,600 |
|
Remaining short-term debt |
27,000 |
|
Source: Heeton Holdings, iFAST estimates |
|
Assuming the group manages to refinance at least some of its near-term bank loans and achieves a satisfactory exchange of the existing bond, the group’s liquidity looks adequate. Furthermore, with a debt-to-asset ratio of 0.45x, the group should still have meaningful debt headroom. We understand from management that 52% of the group’s property value are unencumbered, which should allow it to take on more loans if needed.
Relative valuation
We compare the group against other high-yielding names in the Singapore real estate sector.
Table
3
Peer
comparison
|
1H20 key ratios |
EBIT over interest (x) |
Net debt over equity (%) |
Total debt over total assets (%) |
|
Heeton Holdings |
-0.14 |
92.8 |
45.45 |
|
Centurion Corporation |
2.99 |
119.9 |
54.10 |
|
Chip Eng Seng Corporation |
-1.02 |
155.51 |
55.53 |
|
Fragrance Group |
0.23 |
147.2 |
58.56 |
|
Oxley Holdings |
1.07 |
193.9 |
54.39 |
|
Tuan Sing Holdings |
0.45 |
137.4 |
57.32 |
|
Source: Bloomberg Finance L.P., iFAST estimates |
|||
Figure
1
Relative
valuation
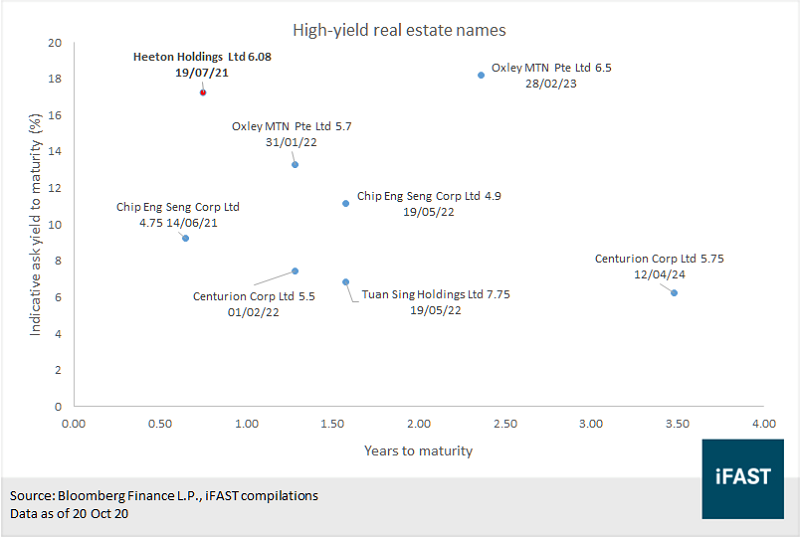
Looking at financial ratios, of the most concerning is the negative EBIT over interest of Heeton. Its gearing ratios look the best of the lot.
By divesting its assets and/or refinancing, Heeton has a high chance of tiding through this crisis in our view. Combined with a satisfactory exchange exercise result, it should be able to redeem the 6.08% notes due 2021. Even with additional gearing, there should still be room for its spreads to compress, reaching similar values of its peers. Thus, the minimum coupon rate of 6.8% for the new issue seems fair.
To exchange or not to exchange?
In the event where the exchange offer achieves unsatisfactory participation, we could have two scenarios: 1) Heeton fails to redeem the HTONSP 6.08% ‘21s; or 2) Heeton redeems the bond.
In the negative first scenario, if you had exchanged the bonds, the bright side is that you have already cashed in S$50,000.
In scenario 2, Heeton might continue to lack liquidity visibility after the bond redemption, or it could continue to suffer from the global pandemic, both of which could lead to the new issue due 2021 trading below par. Assuming this last point, it would have been better for you not to have exchanged the bonds (as you could have bought the notes from the secondary market at a discount to par instead). However, this sequence of events should be unlikely, as we understand that the firm is already considering proposals for asset disposals.
If the exchange offer exercise achieves satisfactory participation, the new notes due 2023 should also trade near par. If you did not exchange your bonds, it could be possible for the existing 2021 bond to trade above par, especially if asset disposals are announced soon. However, a substantial amount of notes submitted for the exchange would led to significantly reduced trading liquidity of the remaining outstanding notes, making it unlikely that investors holding on to the 2021 bond would be able to exit early.
Overall, the best action seems to be for the investor to exchange his/her bonds. A noteholder can push his luck and wait for the possibility of better (lower) prices for the new notes due 2023 bonds, although the likelihood of this scenario seems lower to us. Prices of the existing HTONSP 6.08% ‘21s also look attractive at the ask yield of 17.26%. Investors may also choose to invest in the bonds and opt for the exchange offer.
Declaration: For specific disclosure, at the time of publication of this report, IFPL holds a position in OHLSP 6.375% 21Apr2021 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!