


Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
- F&N delivered solid results in 1H23 and 9M23, with 9M23 revenues and PBIT showing positive growth in constant-currency terms. This was however weighed down by FX headwinds.
- We think its core businesses should continue to deliver solid sales and profits, while its recent acquisitions may also help to boost its long-term growth outlook.
- F&N's debt remains relatively well-managed with a solid cash buffer.
- We like F&N as an issuer, with a preference for their FNNSP 3.000% 09May2025 Corp (SGD) given its lower duration and maturity risks.
About Fraser and Neave, Limited (F&N)
Fraser and Neave, Limited (F&N) is a Singaporean conglomerate founded in 1883, and is today a household name within the regional food and beverage (F&B) space. Its shares are currently majority-owned by Thai business magnate Charoen Sirivadhanabhakdi, founder of ThaiBev.
F&N has three main business segments: (i) dairies; (ii) beverages; and (iii) publishing & printing (P&P). We elaborate on these segments below (data as of 9M23 – note that FY ends in Sep each year):
- Dairies: This segment is F&N’s largest contributor to revenues and profits before interest and tax (PBIT), accounting for 57% of revenue and 84% of PBIT respectively. Some of its signature products include Magnolia, Farmhouse Milk, and King’s Ice Cream.
- Beverages: This is another key contributor to F&N’s performance accounting for 29% of revenues and 16% of PBIT. Some of its signature products include 100Plus and NutriSoy.
- P&P: This segment accounts for 10% of F&N’s revenues, with signature brands like Marshall Cavendish (publishing) and TIMES bookstores (retail).
F&N recently reported its financial statements for 1H23, as well as a voluntary business update in 9M23. We like its stable business model reflected in its recent performance, and think it remains a solid issuer for fixed income investors.
Performance highlights
Its recent 9M23 update generally showcased resilience for F&N’s core F&B business (which includes dairies and beverages), despite some FX headwinds.
9M23 revenues grew 5.6% YoY from SGD 1495.5m to SGD 1579.9m, led by the beverages segment which saw a 7% YoY increase in revenues. Management also highlighted the contribution of soft drinks, beer, and dairies, which benefited from higher selling prices, the successful execution of festive campaigns, new product launches, and higher export sales. Despite decent top-line growth, PBIT fell by -2.1% YoY from SGD 180.0m to SGD 176.3m, while PBIT margins also saw a decline from 12.0% to 11.2% over the same period. Management has attributed this primarily to factors like higher advertising spending and input costs, as well as FX headwinds (highlighted below).
On a group level, FX headwinds were a significant headwind to both top-line and bottom-line performances (Table 1). Revenues grew +11% YoY while PBIT grew +4% YoY in constant-currency terms, indicating that FX effects accounted for about 6 percentage points off of performance.
Table 1: Summary of performance highlights – FX headwinds were an important contributor
| F&N | 9M22 | 9M23 | Change (YoY) | Change in constant FX terms |
| Revenue (SGD m) | 1,495.5 | 1,579.9 | +5.6% | +11% |
| PBIT (SGD m) | 432.9 | 460.3 | -2.1% | +4% |
| PBIT Margin (%) | 12.0% | 11.2% | -88 bps | - |
| Source: F&N, iFAST compilations. Data as of 9M23 (FY ends in Sep 2023). | ||||
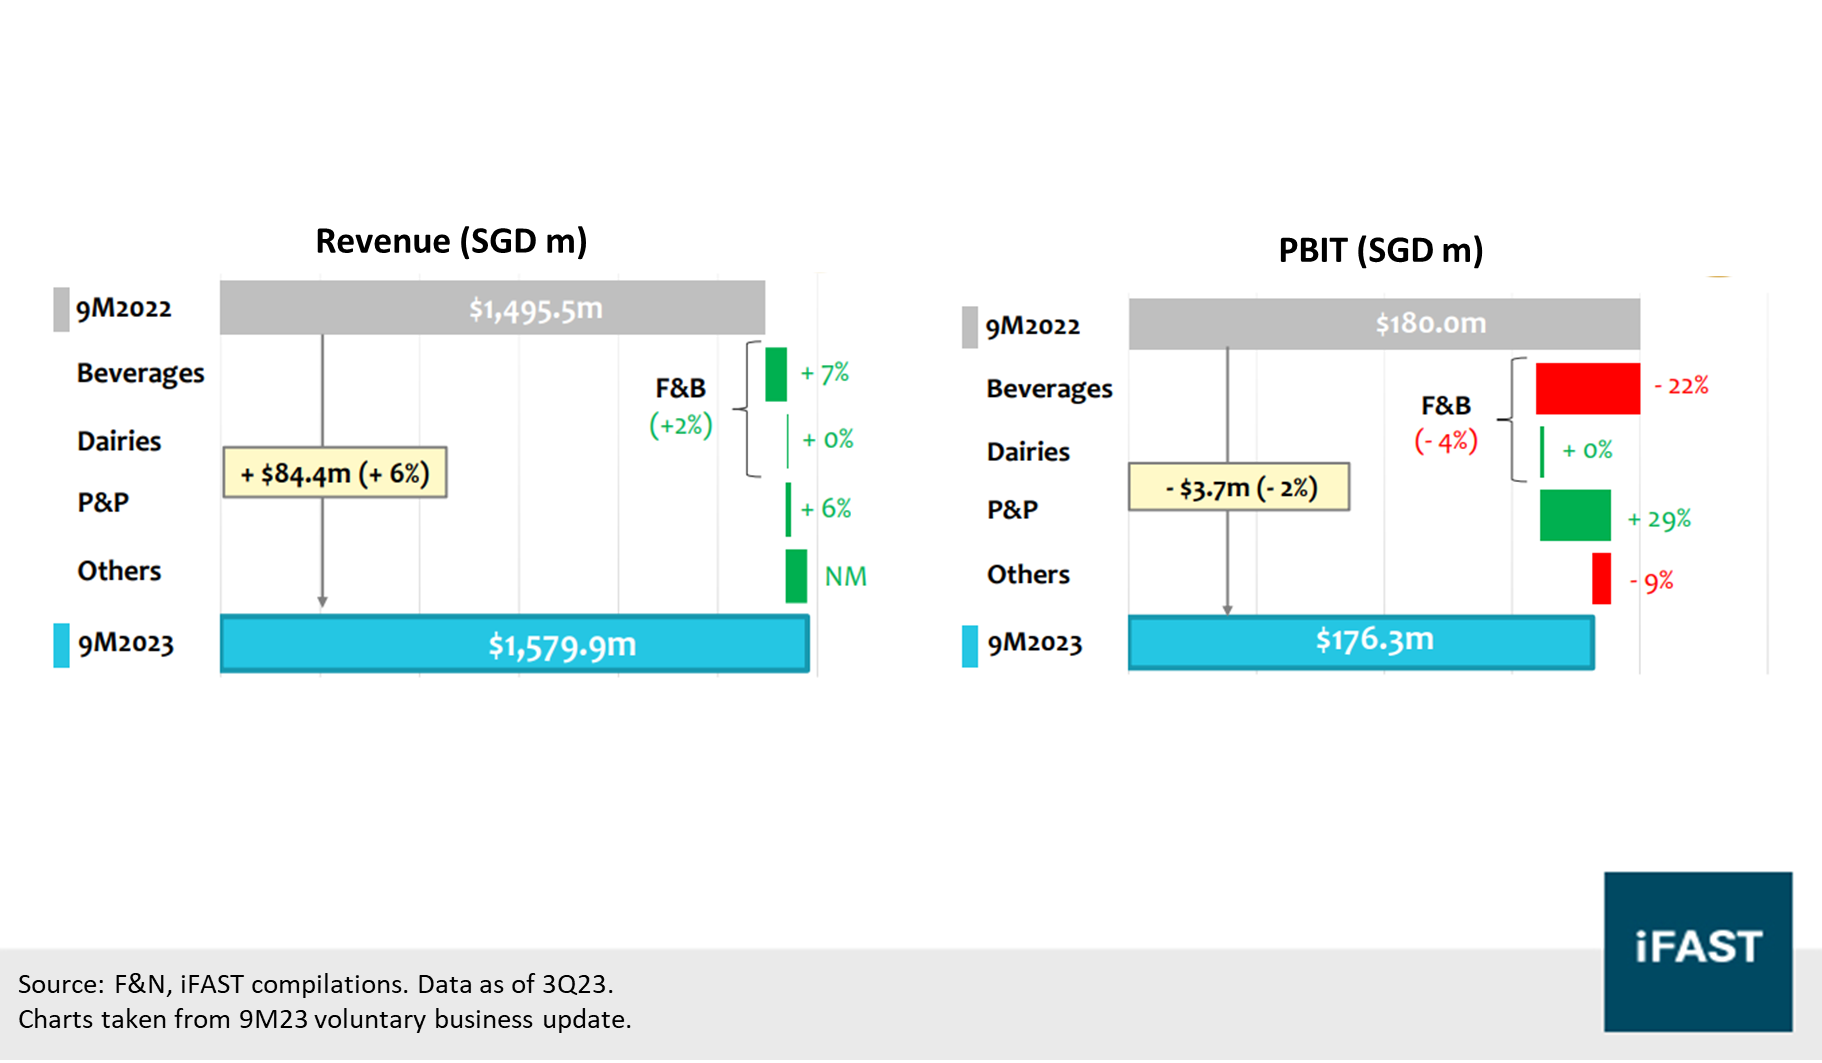
On a segmental level (Chart 1), Beverages revenues grew 7% YoY, likely due to higher selling prices and festive campaigns across the Lunar New Year and Hari Raya seasons (among other factors highlighted above). Despite this decent top-line performance, Beverages PBIT fell by a sizeable -22% YoY, once again partially due to FX (-16% in constant-FX terms). Similarly, Dairies performance was relatively flat (mildly positive: displayed as +0% revenue and PBIT growth by F&N), with FX also resulting in about a 5-percentage-point headwind.
The P&P segment meanwhile saw a solid 6% YoY revenue growth as well, on the back of strong book distribution and retail sales. However, P&P still failed to turn a positive PBIT despite narrowing losses in 9M23 – we note that this segment has generally been among the least profitable segments for F&N, as it also had negative PBIT in FY20, FY21, and FY22. We also note the small positive contribution from the “Others” segment (4% of revenues, 8% of PBIT). In particular, 9M23 revenues were lifted by the additional contribution of revenues from Cocoaland (recently acquired in Nov 2022).
Chart 1: Segmental breakdown of changes in revenue and PBIT
Outlook for F&N
We think F&N can leverage its strong branding to continue growing its existing core businesses. Many of its top brands are household names within the region, which would likely lend some stickiness to overall consumption patterns. Even in the event of an economic slowdown (a possibility acknowledged by management), we think its products are relatively less cyclical, and demand should remain broadly supported even through such a slowdown.
F&N’s recent investments and acquisitions may also prove to be beneficial for its profitability over the longer term. For instance, its full acquisition and privatisation of Cocoaland (of its remaining 72% equity interest) shows its willingness to expand beyond its traditional Beverages and Dairies portfolios, into the Halal packaged-food / snack segments, potentially allowing F&N to reach a wider pool of customers. Another example is its development of a (vertically) integrated dairy farm in Malaysia (with 20,000 milking cows, targeting 200m litres of milk annually), which management has said would help to reduce its overall import costs.
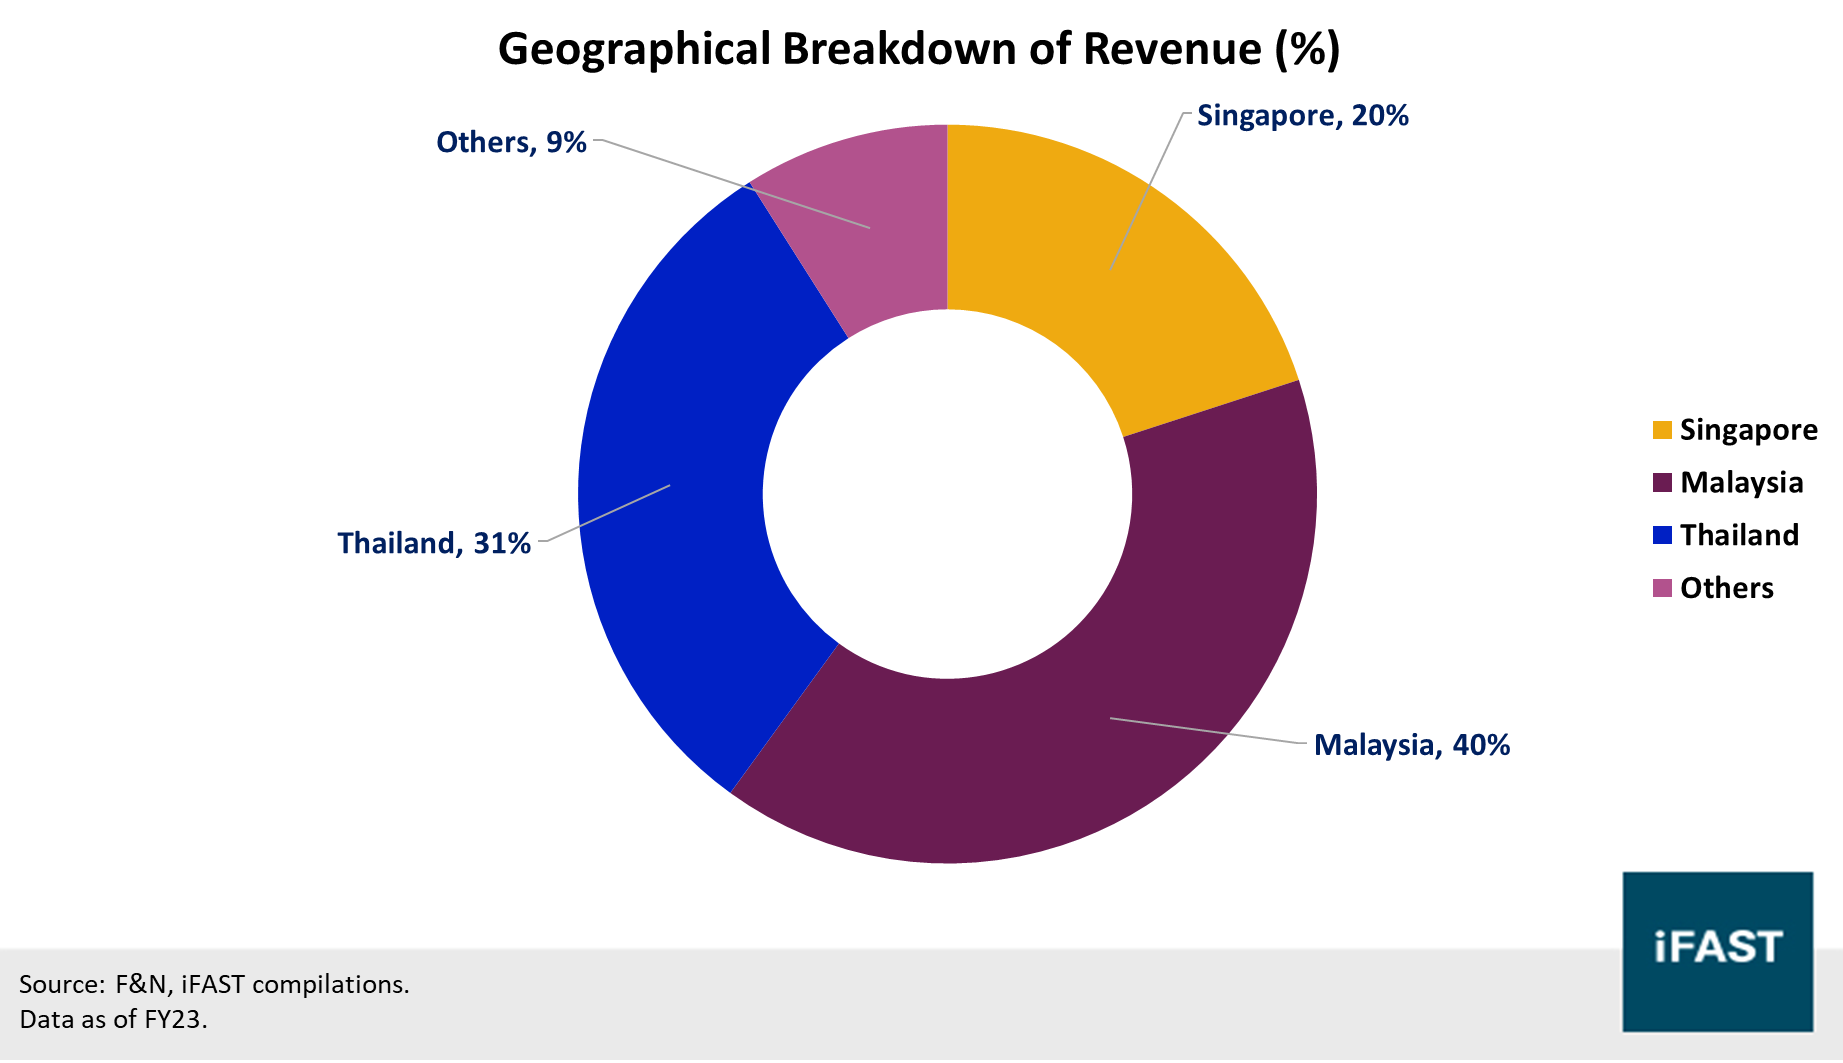
We acknowledge the ongoing FX headwinds as the continued strength of the SGD (versus counterparts like MYR and THB) would hurt headline performance, especially given that F&N only generates 20% of its revenues in Singapore (40% in Malaysia, 31% in Thailand) (Chart 2). However, we note unfavourable FX translations have already been repeatedly cited as headwinds for several quarters, and think that (barring a drastic move in the SGD) these FX headwinds have likely already been taken into account by investors.
F&N management themselves (as of 1H23) remain “cautiously optimistic” that 2H23 performance will improve from the previous 2H22’s performance. As a whole, we think F&N remains well-placed to deliver consistent returns over the medium term and see a fairly stable outlook for the company.
Chart 2: F&N makes a large proportion of revenue outside of Singapore
Credit highlights
F&N continues to have ample liquidity as of 1H23 (Table 2). Its current ratio remained stable at 1.85X (a slight drop from FY22’s 1.97X, but nonetheless fairly solid), while it has also improved its cash position significantly to SGD 348.1m in 1H23 (and to SGD 372.1m in 3Q23).
Looking at other credit metrics, we find that its net gearing ratio has increased somewhat in 1H23 (22.7%) compared to previous halves (1H22: 16.7% / 2H22: 17.6%). In addition, net debt to last-12-months PBIT also generally rose over the same period. This is due to a fairly large increase in borrowings (offsetting the improved cash balance seen above), which we attribute to the multiple acquisitions and expansions made by F&N in recent times (including the two examples above of Cocoaland and the integrated dairy farm). Nonetheless, we see signs of these two ratios stabilising in 3Q23 and believe that F&N remains disciplined in its borrowings as a whole, with gearing well below its target maximum of 80% (Table 3).
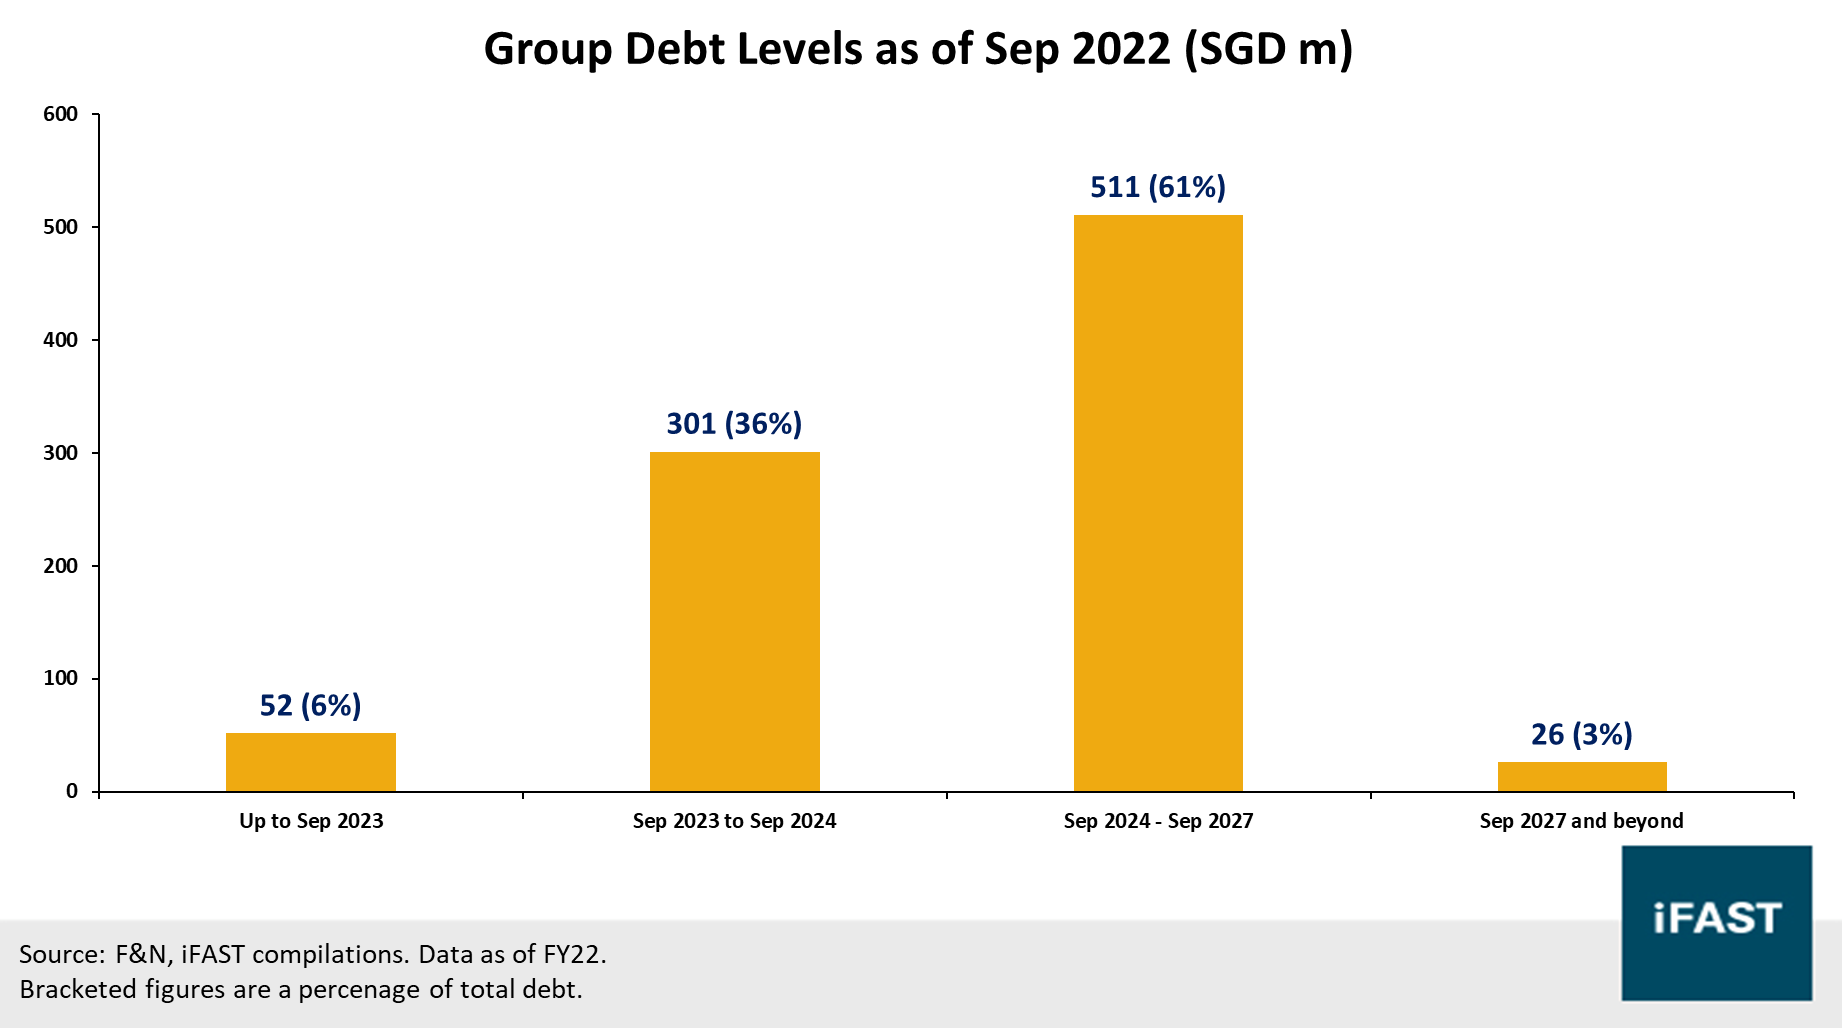
Looking at F&N’s overall debt maturity profile, it revealed that it had SGD 138.3m of current borrowings maturing by Jun 2024 as of 3Q23. Previously, F&N also indicated in its FY22 (year ended Sep 2022) report that it had approximately SGD 352.7m of debt maturing between Sep 2022 and Sep 2024 (Chart 3). We also consider its latest reported cash position of SGD 372.1m as of 3Q23, supplemented by about SGD 1.2b of aggregate banking facilities reported as of FY22. Finally, we like that a large majority (83%) of F&N’s debt is on fixed rates, helping to mitigate funding pressures in a rising-rates environment.
As a whole, we think F&N’s debt remains well-managed, and we think its cash position continues to have a healthy buffer over maturing debt over the near term.
Table 2: F&N continues to have ample liquidity
| F&N's Liquidity Metrics | 1H22 | 2H22 | 1H23 |
| Current Assets (SGD m) (A) | 996.6 | 1,066.6 | 1,088.1 |
| Current Liabilities (SGD m) (B) | 778.6 | 541.2 | 587.4 |
| Current Ratio (A / B) | 1.28 | 1.97 | 1.85 |
| Cash & Bank Deposits (SGD m) (C) | 252.8 | 274.6 | 348.1 |
| Cash Ratio (C / B) | 0.32 | 0.51 | 0.59 |
| Source: F&N, Bloomberg, iFAST compilations. Data as of 1H23. | |||
Table 3: F&N’s debt levels increased due to acquisitions, but now appear to be stabilising
| F&N's Credit Metrics | 1H22 | 2H22 | 1H23 | 3Q23** |
| Net Debt (SGD m) (A) | 580.9 | 614.7 | 766.6 | 744.5 |
| Total Equity (SGD m) (B) | 3,478.4 | 3,502.5 | 3,375.9 | Not available |
| Net Debt / Equity (A / B) | 16.7% | 17.6% | 22.7% | 22.0% |
| PBIT (SGD m) (C) | 127.0 | 106.4 | 105.8 | 176.3 |
| Net Debt / LTM PBIT* | 2.47 | 2.63 | 3.61 | 3.24 |
| Interest Expense (D) | 13.3 | 12.9 | 18.5 | Not available |
| Interest Coverage (C / D) | 9.53 | 8.26 | 5.73 | Not available |
| Source:
F&N, Bloomberg, iFAST compilations, iFAST estimates. Data as of
1H23. *Last 12 months data taken for PBIT. Ratio for 1H22 therefore includes SGD 108.5m PBIT earned in 2H21. **Data is limited as company only provided a voluntary update. |
||||
Chart 3: Debt maturity profile remains healthy
Recommendations
F&N currently has three bonds outstanding. Among these, our primary preference is for the FNNSP 3.000% 09May2025 Corp (SGD), as it has the lowest maturity and duration of the three bonds.
Currently, we think the yield pickups for the 2026 bond (13 bps) and the 2027 bond (18 bps) are fairly thin. First, these yield pickups may not necessarily justify the duration risks especially as we head towards a higher-for-longer interest rate environment. Second, these yield pickups may also not justify the term maturity risks, especially considering the execution uncertainty involved regarding F&N’s recent acquisitions. With that being said, investors who are aware of and willing to take on additional duration and term maturity risks can still consider the 2026 bonds and 2027 bonds for the slight yield pickup.
F&N’s business model – as a leading regional player in Beverages and Dairies – naturally results in relatively stable revenues and profits. Meanwhile, while it has strategically taken on more debt to fund acquisitions and initiatives (e.g. Cocoaland) that could further its long-term growth potential, we like that it maintains a healthy cash position which covers its near-term maturities. To summarise, we think F&N remains a solid issuer for bond investors, with a preference for the FNNSP 3.000% 09May2025 Corp (SGD) bond.
Table 4: List of F&N bonds (recommendations bolded)
| Bond Name | Maturity Date (Years to Maturity) |
Ask Price | Current Yield (%) | Yield to Worst (%) |
| FNNSP 3.000% 09May2025 Corp (SGD) |
09 May 2025 (1.6) |
98.310 | 3.052% | 4.114% |
| FNNSP 2.000% 16Jun2026 Corp (SGD) |
16 Jun 2026 (2.7) |
94.365 | 2.119% | 4.242% |
| FNNSP 3.800% 21Apr2027 Corp (SGD) |
21 Apr 2027 (3.5) |
98.400 | 3.862% | 4.293% |
| Source: Bloomberg, Bondsupermart, iFAST compilations. Data as of 05 Oct 2023. | ||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









