Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
- AAREIT saw a robust performance in FY23, with gross revenues climbing 17.6% and net property income rising 18.7% YoY.
- Looking ahead, we continue to expect a stable outlook for AAREIT supported by solid rental reversions.
- AAREIT’s liquidity and credit profile remain decent, especially considering its relatively light debt maturity schedule in the near term.
- We remain positive on both of AAREIT’s perpetuals, with a slight preference for the AAREIT 5.650% Perpetual Corp (SGD) given its larger reset spread, earlier call date, and smaller issuance size.
About AIMS APAC REIT (AAREIT)
AIMS APAC REIT (“AAREIT”) is an industrial REIT focused on the Asia Pacific region, whose portfolio currently comprises 29 properties in Singapore (26) and Australia (3). A majority of its properties in Singapore are logistics warehouses and industrial properties, while its three properties in Australia consist of two business parks and one industrial property.
It is managed by AIMS APAC REIT Management Limited, a wholly-owned subsidiary of AIMS Financial Group, which in turn is its sponsor. AIMS Financial Group is a financial services investment group which is active in many areas including property investment.
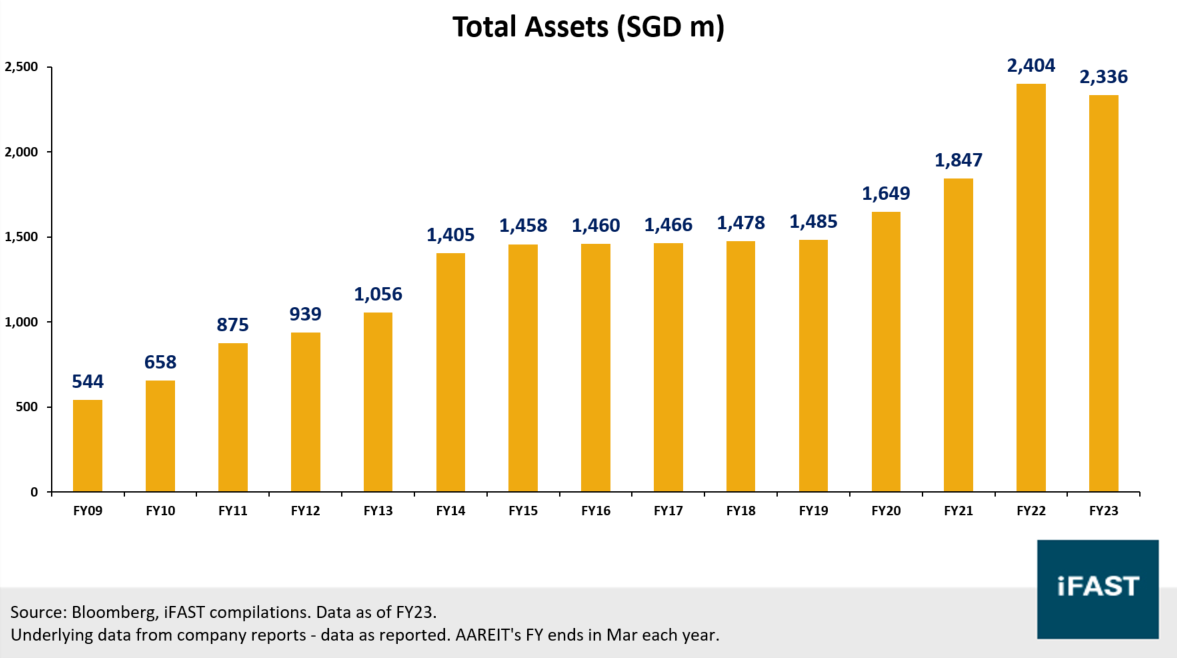
Currently, AAREIT has a market cap of SGD 885m (as of 8 Jun 2023) and total assets of SGD 2.3b (as of 31 Mar 2023) (Chart 1).
Chart 1: AAREIT’s had total assets of SGD 2.3 billion as of 31 Mar 2023
Latest updates on AAREIT
FY23 financial results (Ended Mar 2023)
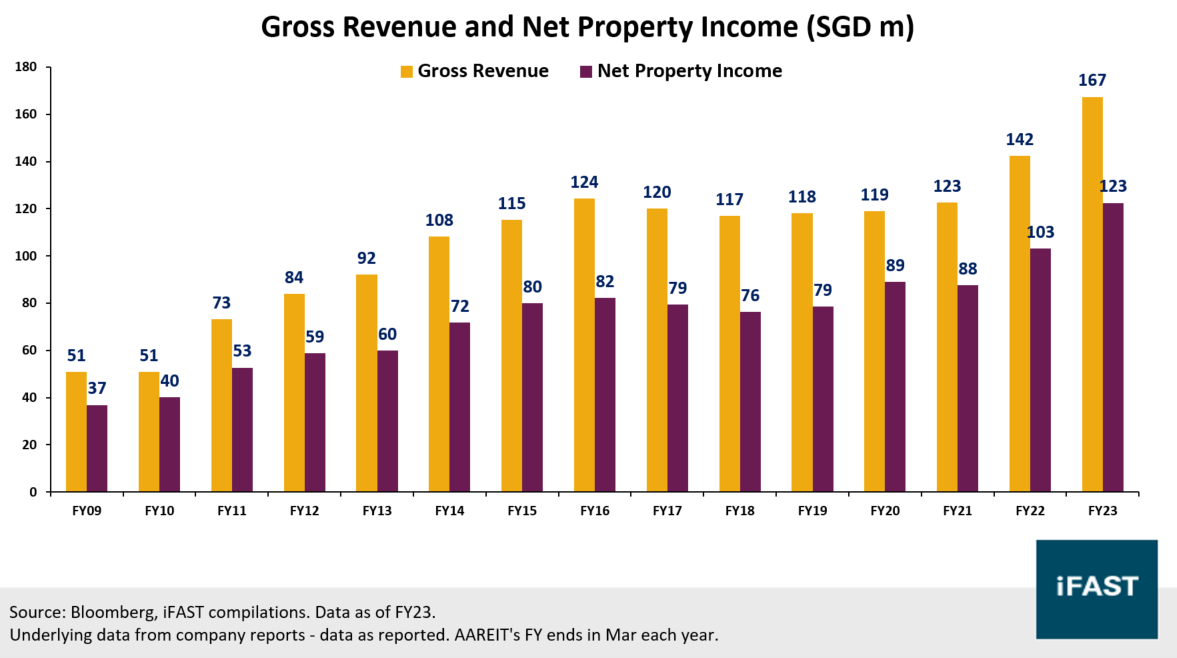
For the full year ended 31 Mar 2023 (“FY23”), AAREIT’s gross revenues climbed 17.6% to SGD 167.4m, while net property income rose 18.7% to SGD 122.5m (Chart 2). AAREIT attributed the increases to higher rental and recoveries from AAREIT’s logistics and warehouse, hi-tech and industrial properties, as well as full-year revenue contribution from the acquisition of Woolworths HQ in Australia (completed in Nov 2021).
These robust FY23 results mean that on a compounded annual growth rate (“CAGR”) basis, gross revenues and net property income have increased by 6.2% and 8.7% respectively over the past 10 years. These have likely been supported by robust portfolio occupancy rates (FY23: 98.0% / 10y average: 94.6%) and positive rental reversion rates (FY23: 18.5%).
Looking ahead, AAREIT’s management has guided for resilient operational performance and occupancies even amidst an uncertain macro environment. They expect this to be driven by steady demand in the industrial market, as well as strong rental reversions in the logistics and warehouse segment.
Chart 2: AAREIT’s gross revenues and net property income saw strong growth in FY23
Equity funding exercise (announced May 2023)
AAREIT recently launched an equity funding exercise to raise gross proceeds of approximately SGD 100m. This includes a private placement to raise around SGD 70m and a non-renounceable preferential offering to raise around SGD 30m. Both have since closed at $1.214 and $1.189 per unit respectively at the lower end of their estimated price ranges.
- approximately SGD 32.0m for asset enhancement initiatives (AEIs) for two of AAREIT’s Singapore properties;
- approximately SGD 65.2m for any other AEIs, re-developments of the properties owned by AAREIT and potential acquisitions, as well as pare down AAREIT’s existing debt to keep AAREIT’s aggregate leverage within the desired range; and
- approximately SGD 2.8m to pay the estimated professional and other fees and expenses incurred by AAREIT in connection with the Equity Fund Raising.
Overall, spending on AEIs could potentially support further positive rental reversions and hence total returns in future, while the paring of debt will also likely be beneficial to bondholders. Therefore, we believe this equity funding exercise does not weaken the broadly stable outlook for AAREIT and their bonds.
Liquidity and credit profile remain decent
In our view, AAREIT continues to maintain ample liquidity. Current assets climbed +13% YoY to SGD 34.1m in FY23, despite a decline in cash and equivalents. Cash from operations climbed 7% YoY to SGD 99.7m in FY23. As a whole, several liquidity metrics of AAREIT, including operating cash flow ratio, current ratio, and cash ratio, all improved from FY22 to FY23 (Table 1).
AAREIT’s longer-term credit profile also remains fairly decent. It recently reported an interest coverage ratio (ICR) of 3.8X, and an adjusted ICR (including perpetual distributions) of 2.3X as of FY23. Its aggregate leverage ratio also remained fairly stable at 36.1%, below the MAS requirement of 45%. Its most recent net-debt-to-EBIT ratio was also 8.7X in FY23, lower than FY22’s 11.0X (Table 2).
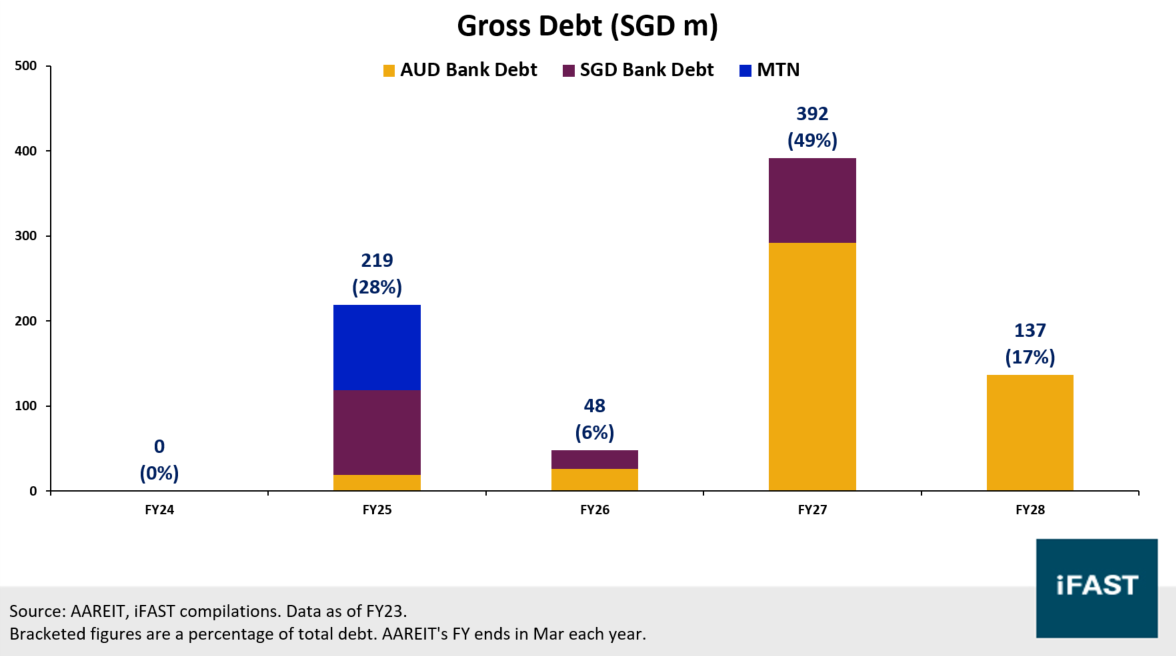
We also observe AAREIT has a solid debt maturity profile. First, AAREIT has a relatively light debt maturity schedule in the near term – it has a weighted average debt maturity of 3.1 years with no refinancing required in FY24 (Chart 3) (out of its total gross debt of SGD 796m). Almost half of its debt will expire in FY27 itself, suggesting AAREIT has sufficient time (several years) to find new refinancing alternatives in the interim. Second, a large majority (88%) of its borrowings are on fixed rates, which could keep its debt manageable in a higher-for-longer rates environment.
Considering these factors above, we believe AAREIT’s overall debt profile remains decent.
Table 1: AAREIT continues to maintain ample liquidity
| AAREIT's Financial Metrics | FY2022 | FY2023 |
| Cash from Operations (A) | 93.3 | 99.7 |
| Current Assets (B) | 30.2 | 34.1 |
| Current Liabilities (C) | 80.9 | 43.2 |
| Cash & CE (D) | 21.4 | 13.2 |
| Operating Cash Flow Ratio (A / C) | 1.15 | 2.31 |
| Current Ratio (B / C) | 0.37 | 0.79 |
| Cash Ratio (D / C) | 0.26 | 0.31 |
| Source: Bloomberg, iFAST compilations. Data as of
FY23. AAREIT's FY ends in Mar each year. All non-ratio data-points are in SGD millions. |
||
Table 2: AAREIT’s longer-term credit profile remains decent
| AAREIT's Financial Metrics | FY2022 | FY2023 |
| Adjusted Interest Coverage Ratio (X) | 2.3 | 2.3 |
| Aggregate Leverage Ratio (%) | 36.1% | 36.4% |
| Interest Coverage Ratio (X) | 4.1 | 3.8 |
| Net Debt / EBIT (X) | 11.0 | 8.7 |
| Gross Debt (SGD m) | 818 | 796 |
| Source: AAREIT, Bloomberg, iFAST compilations.
Data as of FY23. AAREIT's FY ends in Mar each year. |
||
Chart 3: AAREIT has a relatively light debt schedule in the near-term
Risks
AAREIT is exposed to foreign currency (“FX”) risks with its large share of assets in Australia (36.4% as of 31 Mar 2023). Nonetheless, management has reported that 70% of AAREIT’s AUD distributable income is hedged to SGD on a rolling four-quarter basis. We have also written that demand for AUD could remain supported in 2023 due to a slowdown in Fed hikes as well as the end of China’s zero-COVID policy here. As such, we do not expect FX risks to have a significant effect on AAREIT’s long-term potential.
We also note the risk of non-calls for AAREIT’s perpetuals, which are next callable in 2025 and 2026. Given current ICRs and aggregate leverage ratios, AAREIT may find it difficult to replace these perpetuals with fresh non-perpetual issuances without exceeding MAS limits. Nonetheless, we believe there is ample time to the next call (over 2 years) for AAREIT to improve its credit profile, and there is an incentive for AAREIT to refinance the perpetuals given the high reset spreads for both of their existing perpetuals.
Recommendation: AAREIT 5.650% Perpetual Corp (SGD)
Looking ahead, AAREIT’s earnings are likely to continue seeing stable growth in the years ahead backed by robust trends in both Singapore and Australia, particularly if rental reversions remain solid. Coupled with AAREIT’s decent liquidity and credit profile especially considering its light debt maturity schedule in the near term, we believe both of AAREIT’s perpetuals will be able to provide stable and robust cash flows for investors in the years ahead.
AAREIT currently has three issued SGD bonds outstanding (Table 3). From these bonds, the AAREIT 5.650% Perpetual Corp (SGD) has an indicative ask yield-to-call (“YTC”) of 6.26%, compared to AAREIT 5.375% Perpetual Corp SGD’s 6.50%. While the former does have a slightly lower yield (by 24 basis points [bps]), we note that its (i) larger reset spread of 520.7bps (compared to its counterpart’s 465.4bps); (ii) earlier call date (2025); and (iii) smaller issuance size reduces the likelihood of non-calls of the former compared to the latter.
As such, while we find both perpetuals attractive as a whole given AAREIT’s stable outlook, we slightly prefer AAREIT 5.650% perpetuals for the lower likelihood of non-calls. Nonetheless, Bond Express investors who wish to purchase AAREIT’s 5.375% perpetuals can still benefit from the solid outlook for AAREIT ahead.
Table 3: Profile of AAREIT bonds
| Bond Name | Maturity / Call Date (Years to Maturity / Next Call) |
Reset Rate | Ask Price (SGD) | Current Yield (%) | Yield to Next Call / Maturity (%) |
| AAREIT 5.650% Perpetual Corp (SGD) |
14 Aug 2025 (2.2y) |
5Y SOR + 5.207% | 98.79 | 5.72% | 6.26% |
| AAREIT 5.375% Perpetual Corp (SGD) |
01 Sep 2026 (3.2y) |
5Y SORA OIS + 4.654% | 96.75 | 5.56% | 6.50% |
| AAREIT 3.600% 12Nov2024 Corp (SGD) |
12 Nov 2024 (1.4y) |
- | 99.12 | 3.63% | 4.27% |
| Source: Bloomberg, Bondsupermart, iFAST compilations. Data as of 08 Jun 2023. | |||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in AAREIT 5.375% Perpetual Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!