


- SUNSP revenues improved from higher shopper traffic in Suntec City Mall
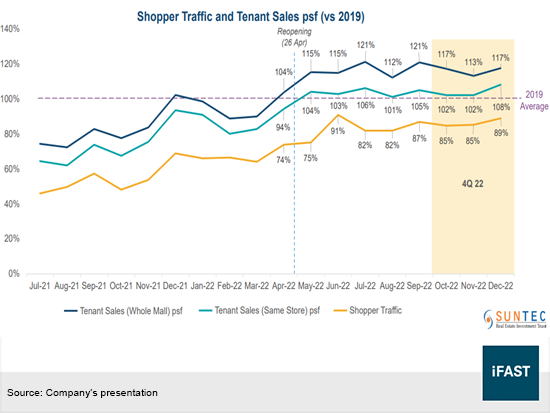
- Since reopening, shopper traffic for Suntec City mall have been on an upwards trend
- We expect further improvement in Suntec Convention from the strong pipeline of events in 2023
- Although SUNSP is leveraged with little debt headroom for future acquisitions, we are confident of SUNSP’s debt repaying ability as it is able to refinance its bank borrowings
- Among its bonds, we like the SUNSP 2.950% 05Feb2027 Corp (SGD) giving close to 5% YTM over a period of ~4 years
Meetings, Incentives, Conventions and Exhibitions (“MICE”) events have finally returned to Singapore after a long hiatus due to COVID-19. One beneficiary of this is Suntec REIT as it holds one of the biggest convention halls in Singapore. Poised to make a rebound in 2023, we are positive on SUNSP’s bonds yielding close to 5%.
FY22 Financial Results
Suntec REIT (“SUNSP”) benefited from the reopening of Singapore’s borders as gross revenues increased by 19.3% to SGD 427.3m for the financial year ending 31 Dec 2022 (“FY22”). Net property income also increased by 24% to SGD 315.8m. Contributions from higher shopper traffic from Suntec City and the return of MICE events contributed to the revenue growth from SUNSP.
SUNSP have greatly benefited from the performance of Suntec City mall. Since the reopening, shopper traffic for Suntec City mall have been on an upwards trend. Shopper traffic have returned back to pre-pandemic levels and tenant sales have surpassed 2019 levels. The mall also saw upwards rental revision of 4.8% for FY22 and 7.1% for 2H22. Occupancy for the mall have also remained stable at 98.3%.
Figure 1: Shoppers' traffic exceeded 2019 levels
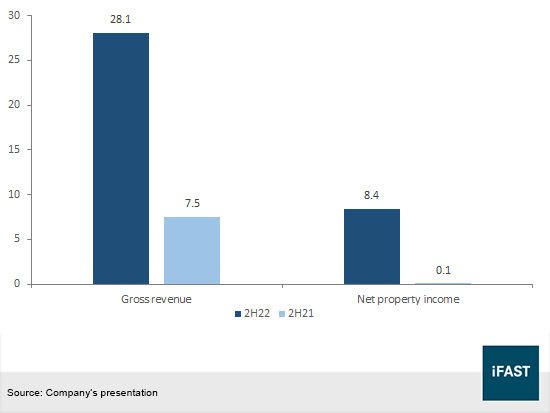
The recovery of MICE events in Singapore also boosted SUNSP’s revenue for 2H22. Revenues for Suntec Convention improved by 274.7% to SGD 28.1m from SGD 7.5 in 2H21. We expect further improvement in Suntec Convention from the strong pipeline of events in 2023. The synergies between Suntec Convention and Suntec City Mall will also likely boost revenues for Suntec City Mall.
Figure 2: Great improvement for Suntec Convention after the return of MICE events
In other segments, Singapore office portfolio saw growth of 4.6% in gross revenue from higher rental. In its overseas portfolio, slower growth was experienced due to the negative impacts of weaker Australian dollar and lower occupancy rates at 177 Pacific Highway in Australia.
Overall, SUNSP’s property portfolio was stable in FY22. All of its properties maintained occupancy rates above their respective markets. Higher rental reversion was also experienced in most of its properties. Looking forward, we expect SUNSP retail portfolio to improve from higher occupancy rates as well as the rebound of MICE events in Singapore. From SUNSP management, MICE events are expected to reach full recovery in 2024. For its overseas portfolios, UK is expected to have a slowdown in its economy. Office occupancy may fall in 2023 but SUNSP is underpinned by long WALE which should secure tenants during this period. For Australia, economic growth is also expected to slow down but we still expect positive rental growth albeit at a slower pace.
Table 1: Performance of SUNSP’s property portfolios
|
Portfolio |
Gross revenue (m) |
% change |
Net property income (m) |
% change |
Occupancy rate (%) |
Rental reversion (%) |
|
Singapore office |
68.7 |
4.6% |
54.7 |
7% |
98.5 |
6.8% |
|
Singapore retail |
65.2 |
27.3% |
49.4 |
38.8% |
98.1 |
4.4% |
|
Australia |
49.1 |
-9.6% |
38.4 |
-12.1% |
97.6 |
24.3% |
|
UK |
12.7 |
1.6% |
13.1 |
3.5% |
98.3 |
- |
|
Source: Company’s presentation. |
||||||
Credit profile
As of FY22, SUNSP’s total borrowing amounted to SGD 4.9b while cash and cash equivalents amounted to SGD 269.6m. Gearing ratio for SUNSP was 42.4%, which we find it to be on the higher side compared to other REITs in Singapore. Adjusted interest coverage ratio was 2.4x, down from 2.6x in 2H21. Overall, we think the credit profile of SUNSP to be leveraged with little headroom for future acquisitions. At an interest coverage ratio of 2.4x, SUNSP is unable to raise their leverage above 45% to 50% as per MAS regulations. This makes future acquisitions through additional debt much harder for SUNSP.
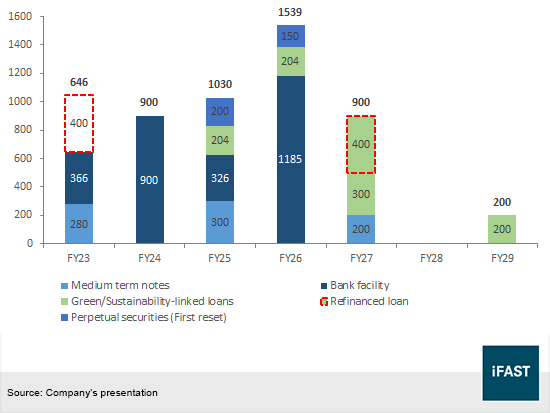
However, we remain confident of SUNSP’s ability to refinance their short-term bank borrowings. In FY22, SUNSP obtained SGD 500m and SGD 400m of sustainability linked loans on 7 Apr 22 and 20 Dec 22 respectively to refinance their maturing bank facilities due in FY23. SUNSP has also increased their proportion of fixed interest rate borrowings from 53% in FY21 to 66% in FY22 to hedge against higher interest rates. This will limit the impact on higher interest rates on SUNSP’s interest coverage ratio and interest costs. SUNSP also has good cash flow generating ability as they are able to generate SGD 273.0m from operations in FY22.
Figure 3: Debt Maturity Profile of SUNSP
Recommendation
Compared to other retail and office REITs peers, SUNSP bonds trade at a much higher yield to maturity (“YTM”). This is due to the credit profile of SUNSP. REITs like OUE Commercial Trust (“OUECT”) and Starhill Global REIT (“SGREIT”) have better credit ratios (Table 2) as compared to SUNSP. Although SUNSP’s credit ratios are much weaker, SUNSP being the bigger REIT in assets is still able to generate much more in cash flows from operations. On top of that, we are confident of SUNSP’s ability to refinance their short-term bank borrowings which they have successfully done so over the years.
Table 2: SUNSP credit ratios are weaker than other REIT peers
|
As of 31 Dec 22 |
SUNSP |
OUECT |
SGREIT |
|
Aggregate leverage ratio |
42.4% |
38.8% |
36.3% |
|
Adjusted interest coverage ratio |
2.4x |
2.5x |
3.3x |
|
Weighted average debt maturity |
2.38 |
2.9 |
3.0 |
|
Source: Respective company’s presentations. |
|||
For SUNSP’s fixed rate bonds, we like the SUNSP 2.950% 05Feb2027 Corp (SGD) with an ask YTM of 4.99% and ~4 years to its maturity date. SUNSP has a stable occupancy rate for its property portfolios and the resurgence of MICE events in Singapore will help to provide stable revenues for the REIT.
Perpetual bonds for SUNSP are yielding close to 6% yield to next call (“YTC”) for ~ 3 years to its call dates. Due to higher interest rates, we are cautious of perpetual bonds as refinancing these bonds will make it more uneconomical for the issuer. For investors who want to take more risk can consider the SUNSP 3.800% Perpetual Corp (SGD) offered on Bond Express where you are able to invest in smaller lot sizes.
Table 3: Relative value of SUNSP fixed rate bonds
|
Bond |
Issuer |
Bond Price |
Maturity date |
Years to maturity |
Yield to maturity (%) |
|
OUECT 3.950% 02Jun2026 Corp (SGD) |
OUE CT Treasury Pte. Ltd. |
97.92 |
02-Jun-26 |
3.31 |
4.63 |
|
SUNSP 2.950% 05Feb2027 Corp (SGD) |
Suntec REIT MTN Pte. Ltd. |
92.71 |
05-Feb-27 |
3.99 |
4.99 |
|
OUECT 4.200% 05May2027 Corp (SGD) |
OUE CT Treasury Pte. Ltd. |
97.73 |
05-May-27 |
4.23 |
4.80 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 9 Feb 2023. |
|||||
Table 4: Relative value of SUNSP’s perpetual bonds
|
Bond |
Issuer |
Bond Price |
First call date |
Years to next call |
Yield to next call (%) |
|
CRCTSP 3.375% Perpetual Corp (SGD) |
CapitaLand China Trust |
94.03 |
27-Oct-25 |
2.71 |
5.79 |
|
SUNSP 3.800% Perpetual Corp (SGD) |
Suntec REIT MTN Pte. Ltd. |
95.15 |
27-Oct-25 |
2.71 |
5.76 |
|
SUNSP 4.250% Perpetual Corp (SGD) |
Suntec REIT |
94.34 |
15-Jun-26 |
3.35 |
6.15 |
|
SGREIT 3.850% Perpetual Corp (SGD) |
Starhill Global REIT |
95.67 |
15-Dec-25 |
2.85 |
5.52 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 9 Feb 2023. |
|||||
Conclusion
In summary, we expect revenues for SUNSP to improve in 2023 underpinned by the growth of its Singapore retail malls. The resurgence of MICE events will boost revenues in the next few quarters and provide synergy to Suntec City Mall. Although SUNSP is leveraged with little debt headroom for future acquisitions, we are confident of SUNSP’s debt repaying ability as it is able to refinance its bank borrowings.
Among its bonds, we like the SUNSP 2.950% 05Feb2027 Corp (SGD) giving close to 5% YTM over a period of ~4 years. Property portfolio is still stable and will provide stable cash flows for them to repay their bonds. For more risky investors they can consider the SUNSP 3.800% Perpetual Corp (SGD)offering at an indicative YTC of 5.76%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in SUNSP 3.800% Perpetual Corp (SGD) and OUECT 3.950% 02Jun2026 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









