


- Hotel Properties Limited reported an increase of 52.7% in revenue to SGD 525.5m in FY22
- We expect revenues to improve from the growth in tourism in Maldives and property development in London
- Tourism in Maldives have recovered back to near pre-pandemic levels and is expected to exceed pre-pandemic levels in 2023
- The HPLSP 4.200% 30Mar2027 Corp (SGD) looks the most attractive at a yield to maturity (“YTM”) of 5.2% for 3.9 years
FY22 Financial Results
For the year ended 31 December 2022 (“FY22”), Hotel Properties Limited (“HPL”) reported revenues of SGD 525.5m, a 52.7% increase from FY21 of SGD 344.2m. The increase was due to the reopening of borders globally and this has led to a strong rebound in travel and tourism. Revenues have generally returned to pre-pandemic levels comparing to FY19 and FY18 revenues of SGD 556.4m and SGD 579.5m respectively. Group net profit attributable to shareholders rose to SGD 76.4 million compared to a net loss of SGD 7.7 million in FY21. Higher profits were due to higher revenues and also the sale of 7 shop units in Ming Arcade for SGD 62m.
Looking ahead, we expect additional revenue contribution to improve from HPL’s hotels in Maldives. HPL’s latest acquisition of a resort in Kanuhura, Maldives is set to finish renovation and reopen in late 2023. Tourism in Maldives will benefit from the reopening of China’s borders and is expected to exceed pre-pandemic levels in 2023. In 2022, HPL also completed construction on two properties in London – Bankside Yards West – Arbor and Paddington Square in December 2022. The next phase of development for Bankside Yards will be the residential tower in Bankside Yards West and building of a new 5 star hotel located in Bankside Yards East. The construction of the remaining retail units of Paddington Square is expected to be completed in 2023. HPL has a 30% stake in Bankside Yards and 70% stake in Paddington Square and the completion of these properties will provide meaningful contributions to HPL’s profits.
China opens up its borders
Maldives resorts and hotels makes up 43% of HPL’s FY22 revenues (Chart 1). Tourism in Maldives suffered in 2020 as a result of the pandemic. Prior to the pandemic, tourist arrivals to Maldives grew at a CAGR of 8.0% from 2010 to 2019. Since the reopening of borders globally, tourism in Maldives have recovered back to near pre-pandemic levels.
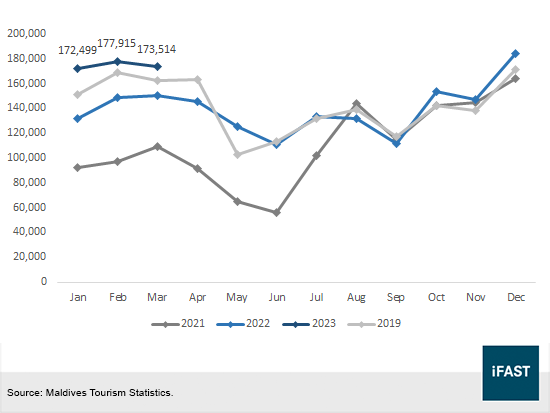
In January 2023, Maldives recorded a record number of monthly tourist arrivals of 172.5k tourist, a 13.8% increase from pre-COVID levels of 151.6k arrivals. As a result, hotel and resort occupancy rates have also seen an increase to 74.4% in the first 2 months of 2023. Higher occupancy rates will help to push revenue per available room (“RevPAR”) higher. RevPAR in Dec 22 was USD 376, 109% higher relative to RevPAR in 2019. As a whole, tourism in Maldives have rebounded back to pre-pandemic levels and at the current pace tourism is expected to exceed and break its record high of 1.7m tourist arrivals in 2019.
Chart 1: Revenue breakdown by geographic segments
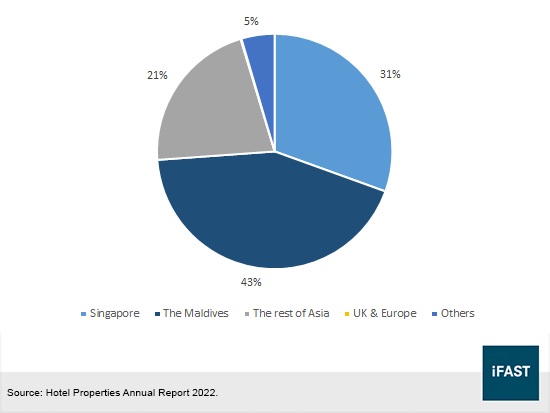
Chart 2: Maldives tourism arrivals per month
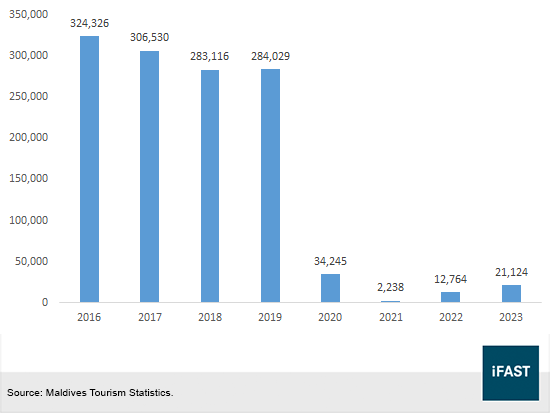
After a 3 years absence, Chinese tourist will be returning to Maldives again. Prior to the pandemic, Chinese tourist have consistently topped the tourism arrival chart in Maldives averaging around 300k tourists per year from 2016 to 2019. So far in 2023, Chinese tourist is now back to the top 10 of tourist arrivals after ranking 27th in 2022. We expect Chinese tourists to rebound back to pre-pandemic levels of around 280k to 300k.
The rebound in tourism in Maldives will provide consistent revenue for HPL’s hotels and resorts. Higher RevPAR will be positive to HPL’s revenues and new acquisitions in Maldives will provide revenue growth as tourism demand in Maldives continues to grow consistently.
Table 1: Top 10 tourism arrivals by nationality
|
Country |
Arrivals |
2022 Rank |
|
Russia |
68,102 |
2 |
|
India |
58,859 |
1 |
|
UK |
55,093 |
3 |
|
Italy |
48,135 |
5 |
|
Germany |
41,489 |
4 |
|
US |
23,184 |
7 |
|
France |
22,780 |
6 |
|
China |
19,748 |
27 |
|
Switzerland |
12,853 |
10 |
|
Austria |
9,696 |
12 |
|
Source: Maldives Tourism Statistics. |
||
Chart 3: Chinese tourist arrivals in Maldives
Credit Profile
Table 2: Credit ratios of HPL vs Shangri-La
|
Name |
Net debt to equity (%) |
Net Debt to EBITDA (x) |
Interest coverage ratio (x) |
Current ratio (x) |
|
Hotel Properties Ltd |
81.01 |
16.58 |
1.60 |
0.92 |
|
Shangri-La Asia Ltd |
99.72 |
25.05 |
1.00 |
0.72 |
|
Source: Bloomberg Finance L.P., iFAST Compilations. |
||||
For FY22, HPL had cash and cash equivalents of SGD 105.3m while total borrowings amounted to SGD 1,697.9m. Total borrowings have been growing since 2017 due to the company funding acquisitions through debt. Interest coverage ratio was 1.6x in FY22 and we expect ICR to be thinner as financing costs increase for HPL. Finance costs almost doubled from SGD 34.7m to SGD 59.4m. The company is leveraged with a net debt to equity ratio of 81%. While credit metrics for the company may be weak, we think the improvement in revenues from the rebound in the hospitality sector will be able to provide it with consistent cash flow in the medium term. Comparing to similar peers within the hotels and hospitality sector, Shangri-La Asia Limited (“Shangri-La”) has a similar business profile. Referencing Table 2, HPL’s credit metrics are better compared to similar peers within the industry in Singapore.
Recommendation
Among its bonds, the HPLSP 4.200% 30Mar2027 Corp (SGD) looks the most attractive at a yield to maturity (“YTM”) of 5.2% for 3.9 years. It provides a G-spread of 230.4 basis points (“bps”) which is the highest spread among the rest of its bonds.
For its perpetual bonds, our view is that it may run into non-call risks due to higher interest rates. This year, we have seen a few SGD issuers such as Frasers Property Limited and GuocoLand Limited opting to not redeem their perpetual bonds on the first call date. Out of the 5 perpetual bonds that were callable year-to-date, only 1 perpetual bond was called which was the ALLTSP 5.500% Perpetual Corp (SGD). Among perpetual bonds with a call date in 2024, we prefer the FPLSP 4.980% Perpetual Corp (SGD) due to the coupon step up of 100 bps. The FPLSP 4.98% perps have a yield to next call of 6.135% and have shorter years to next call when compared to HPLSP 4.400% Perpetual Corp (SGD). Although the FPLSP 4.98% has a lower YTC, we think the coupon step up ensures that there will be higher probability for the issuer to redeem the bonds on its call date.
All in all, we remain positive on HPL due to the rebound in hospitality. Revenue and Cash flows have recovered to pre-pandemic levels and the improvement in hospitality in Maldives will be beneficial to HPL. While its credit profile may be weak, we believe the improvement in the hospitality sector and future cash flows from the completion of their development properties in London will be positive to its credit profile.
Table 3: Recommendation
|
Bond name |
Issuer |
Maturity |
Years to maturity |
Ask Price |
Yield to maturity (%) |
|
HPLSP 3.800% 02Jun2025 Corp (SGD) |
HOTEL PROPERTIES LTD |
2-Jun-25 |
2.1 |
98.8 |
4.4 |
|
SLHSP 4.500% 12Nov2025 Corp (SGD) |
SHANGRI-LA HOTEL LIMITED |
12-Nov-25 |
2.6 |
100.4 |
4.3 |
|
HPLSP 4.200% 30Mar2027 Corp (SGD) |
HOTEL PROPERTIES LTD |
30-Mar-27 |
3.9 |
96.6 |
5.2 |
|
HPLSP 5.250% 09Mar2028 Corp (SGD) |
HOTEL PROPERTIES LTD |
9-Mar-28 |
4.9 |
101.0 |
5.0 |
|
HPLSP 3.750% 31May2028 Corp (SGD) |
HOTEL PROPERTIES LTD |
31-May-28 |
5.1 |
94.8 |
4.9 |
|
SLHSP 3.500% 29Jan2030 Corp (SGD) |
SHANGRI-LA HOTEL LIMITED |
29-Jan-30 |
6.8 |
93.1 |
4.7 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 19 Apr 23. |
|||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in FPLSP 4.980% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities. HPL is a substantial shareholder of iFAST Corporation Ltd (parent of IFPL) through its subsidiary, Tiga Stars Pte. Ltd.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









