


- In 1H22, Olam reported 24.6% year-over-year increase to SGD 28.4b in revenue.
- Olam Food Ingredient earnings were affected by higher input costs.
- On the other hand, Olam Global Agri EBIT grew 49.4% from higher commodity prices.
- Ofi’s IPO delayed due to unfavourable market conditions but still not off the table.
- OLGPSP 5.375% Perpetual Corp (SGD) provides a 200 bps yield pick up over the OLAMSP 4.000% 24Feb2026 Corp (SGD) which we find attractive.
Olam Group Limited reported strong growth in its business in the backdrop of higher commodity prices. After the completion of Olam’s restructuring, we continue to maintain our positive view on Olam.
About Olam Group Limited
Olam Group Limited (“Olam”) is a major food and agri-business company with operations in 60 countries supplying food and raw materials. Olam is among the world’s largest suppliers of coca beans, coffee, cotton and rice. Olam after a successful restructuring carved out 3 main operating segments – Olam Food Ingredients (“ofi”), Olam Global Agri (“OGA”) and remaining Olam Group (“OG”). Temasek Holdings is a major shareholder of the company with a 51.1% stake in Olam.
Ofi, or Olam Food Ingredients provides sustainable, natural and healthy products to end consumers. OFI caters to trending food-groups who have a growing appetite for healthier, traceable foods from sustainable sources. Ofi supplies cocoa, coffee, nuts, spices and dairies to more than 8,000 customers around the world.
OGA, or Olam Global Agri is a food, feed and fibre global agri-business that primarily operates in emerging markets, particularly Asia and Africa. OGA focuses on providing proteins to consumers in these regions and it has been operating in these markets for more than 30 years. OGA supplies cotton, edible oils, grains, rice, rubber and wood products to over 30 countries.
The remaining Olam Group consists of Olam Global Holdco, Olam Ventures and Olam Technology and Business Services. OG is responsible for the divestment of non-core assets and businesses identified in the 2019-2024 Strategic Plan and redeploying the capital released.
1H22 financial highlights
For the half year ended 30 June 2022 (“1H22”), Olam reported SGD 28.4b in revenue, a 24.6% year-over-year (“yoy”) increase from the year prior. Volumes also increased by 0.5% to 22.5 million tons. Trade volume was contributed mainly by OGA (89.8%), followed by ofi (8%), while the remaining Olam group contributed 2.2%. EBIT also saw growth of 25% yoy to SGD 802.1m on the backdrop of inflationary pressures and supply chain disruptions.
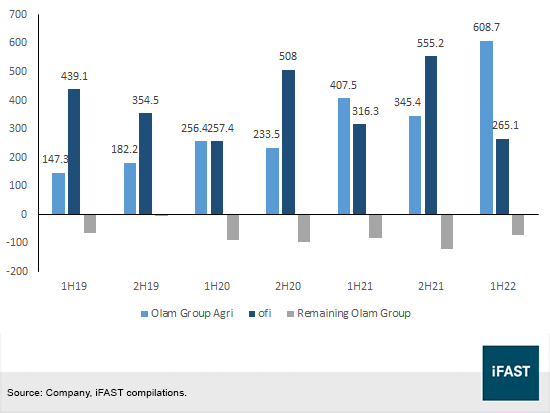
Ofi which usually contributes the majority of Olam’s EBIT fell by 11.8% to SGD 265.1m. This was due to higher depreciation and amortisation from the recent acquisition of Olde Thompson in 2H21. Higher input costs weighed down ofi’s bottom line due to volatile energy prices which led to higher input costs. We expect margins for ofi to improve in the next few quarters as pricing adjustments from Olam will face some lag before flowing through to its income statements.
From 2018 – 2021, OGA’s EBIT grew at a compound annual growth rate of 46.7%. In 1H22, OGA experienced strong growth with EBIT growing 49.4% to SGD 608.7m. This was largely contributed by the freight business, wheat and pasta, Edible Oils and Rice exports from India into Middle East and Africa. Due to higher commodity prices, revenues for OGA grew 26% yoy in 1H22. We expect revenues to normalise as inflationary pressures fall.
OG continues to be loss making as most businesses in OG are still in their early growth stage. OG consists of 3 operating groups, Olam Global Holdco (“OGH”) holds exit assets which Olam plans to divest over a period of 2 years. Out of the 28 assets announced in Olam’s 2019 to 2024 strategic plan, 23 assets have been divested. Olam Ventures is Olam’s start-up businesses that the company invests in. As of 1H22, they have incubated 6 business with Jiva and Terrascope being the most matured. Olam Technology and Business Services solutions is Olam’s IT services and they plan to pivot OTBS into a digital services company in the next 3 years.
Chart 1: Operating segments by EBIT (in SGD m)
Successful reorganisation, ofi IPO next
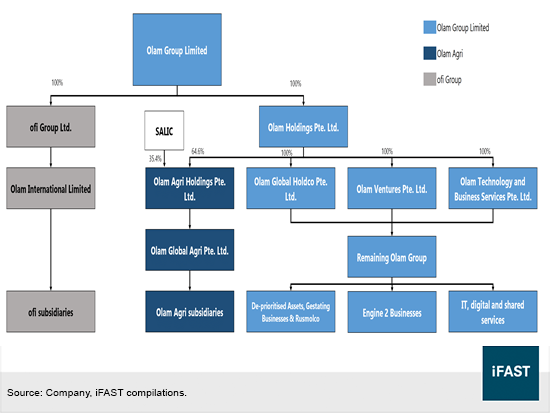
In 2021, Olam went through a reorganisation which carved out 3 separate operating groups – ofi, OGA, OG. Olam International Limited (the previous listed company) was delisted and now part of ofi. Subsequently, Olam Group Limited was listed on the SGX and now owns 100% of all 3 operating groups (chart 2). Temasek Holdings is still the majority shareholder through Breendens Investments and Aranda Investments, representing 51.1% of total issued share capital of Olam. Other shareholders include Mitsubishi Corporation (14.4%) and Kewalram Chanrai Group (6.8%).
In March 2022, Olam announced the sale of a minority stake in Olam Agri to The Saudi Agricultural and Livestock Investment Company (“SALIC”) for USD 1.24b. After the transaction, Olam will still hold a majority stake in OGA of 64.6%. The sale is expected to be completed in 4Q22. The proceeds from the sale will be used to downsize debt and to optimise the capital profile of Olam. On a pro forma basis, Olam’s net gearing will be reduced from 1.73x to 1.28x. We find the transaction to be credit positive to Olam as it downsizes its debt burden ahead of the demerger and IPO of ofi. Looking ahead, Olam is looking to raise another 10% of secondary share sale through either a private placement or a secondary share sale through an IPO of OGA.
Olam planned to demerge ofi and bring the company public on the London Stock Exchange through an IPO but the IPO had been delayed due to unfavourable market conditions. Management have said that the IPO still remains part of their plan and will follow through once market conditions become more favourable.
Chart 2: Current company structure of Olam Group Limited
Credit profile
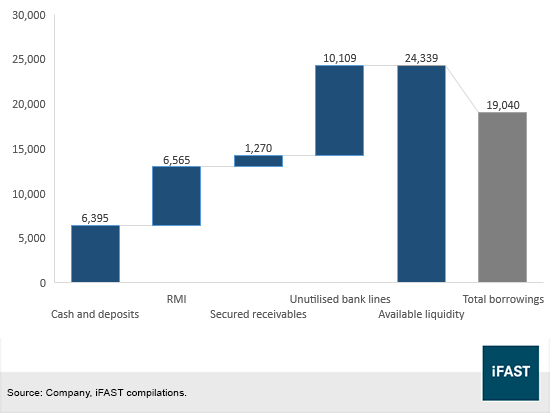
In 1H22, Olam reported positive free cash flow of SGD 465.7m. Liquidity for Olam remains strong with total available liquidity of SGD 24.3b from cash and short-term fixed deposits as well as from unused banking lines. Available liquidity consists of cash and short-term fixed deposits of SGD 6.4b, SGD 6.6b of readily marketable inventories, SGD 1.3b of secured receivables and SGD 10.1b of unutilised banking lines. Total liquidity is enough to cover its borrowings of SGD 19.0b in 1H22. Short-term borrowings made up SGD 10.0b of total borrowings. Debt servicing ability from Olam is adequate with an interest coverage ratio of approximately 2.45x. Olam are in discussions to allocate various debt facilities between the three operating groups. This allows OGA to tap on debt facilities to repay debt obligations or for working capital needs.
We find Olam’s credit profile to be decent as they have been able to manage their working capital despite the rise in interest rates. In July, OGA announced that it has secured a financing facility of an aggregate amount of AED 2,740m (~USD 745m) from banks in the United Arab Emirates. Olam Global Agri Pte. Ltd. and Olam Global Agri Treasury Pte. Ltd., both subsidiaries of OGA, are co-borrowers and the loan will have a tenor of 2.5 years. The facility will be guaranteed by Olam Group and proceeds from the facility will be used to refinance Olam Agri’s existing loans and for general corporate purposes. The share sale of OGA when completed will also reduce Olam’s net gearing from 1.73x to 1.28x.
Chart 3: Olam’s liquidity remains strong in 1H22
Recommendation
We maintain our positive view on OLGPSP 5.375% Perpetual Corp (SGD). The OLGPSP 5.375% perp has an indicative yield to next call of 7.89% with around 3.74 years to its next call date on 18 July 2026. The perp has a high reset spread of 4.807% and a step up margin of 200 basis points (“bps”). Compared to the OLAMSP 4.000% 24Feb2026 Corp (SGD) which is issued by Olam International Limited, the perp has approximately 200 bps pick up over the fixed rated bonds, which we find attractive. Holders of the OLAMSP 6.000% 25Oct2022 Corp (SGD) may also consider to invest in OLGPSP 5.375% Perpetual Corp (SGD) when the bond matures on 25 Oct 2022.
After the restructuring of Olam, the OLGPSP 5.375% perps will be issued under Olam Group Limited which cash flows will be derived from OGA after ofi’s IPO. We think OGA will have the financial capability to service debt and repay the notes on their call dates post ofi IPO as a standalone business. The step up margin of 200 bps also incentivises the issuer to call back the notes on its call date. The stake sale of OGA to SALIC when completed will also reduce the debt burden of the company.
Table 1: Relative valuation of Olam’s bonds
|
Bond Name |
Issuer |
Maturity Date / Call Date |
Years to Maturity / Call date |
Bond Price |
Yield to Maturity / Next Call (%) |
| OLGPSP 5.375% Perpetual Corp (SGD) | Olam Group Limited |
18 July 2026 |
3.74 |
91.98 |
7.89 |
| OLAMSP 4.000% 24Feb2026 Corp (SGD) | Olam International Limited |
24 Feb 2026 |
3.35 |
94.37 |
5.88 |
| OLAMSP 6.000% 25Oct2022 Corp (SGD) | Olam International Limited |
25 Oct 2022 |
Maturing |
100.12 |
-4.89 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 21 Oct 2022. |
|||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OLGPSP 5.375% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!










