


- HPL reported a 33% increase in revenue from SGD 258.8m in FY20 to SGD 344.2m in FY21 due to higher contributions from its Maldives resorts.
- We expect the property contribution to pick up in 2022 as developments in London reach their phase completions in the tail-end of 2022.
- The acquisition of SPH and SPH REIT will provide synergies to the existing HPL portfolio as it provides steady rental income to HPL.
- We recommend the HPLSP 4.400% Perpetual Corp (SGD) with an indicative yield to next call of 5.28% with 2.46 years to its next call date on 22 Oct 2024.
- We believe that following the redemption of their HPLSP 4.650% Perpetual Corp (SGD) prior to its call date, the issuer has adequate capital management to redeem its expiring perps prior to its call date.
Hotel Properties Limited (“HPL”) was incorporated in Singapore on 28 January 1980 and was listed on the SGX (SGX: H15) in 1982. HPL is an owner and operator of hotels under brands such as Four Seasons, Hilton International and InterContinental Hotels Group.
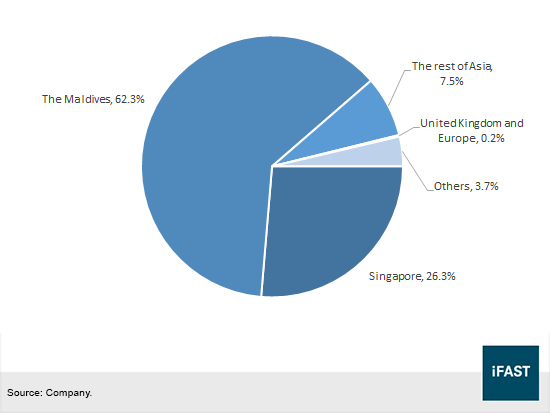
It has 39 hotels under its portfolio and have a presence in 15 countries. Other than hotel management, HPL is also a property developer of premium residential and commercial properties. Some of its past projects include, Tomlinson Heights, Cuscaden Residences as well as joint ventures with CapitaLand such as The Interlace. HPL’s 9 hotel properties in the Maldives generated SGD 214.5m in revenue, which made up the bulk of HPL’s revenue in 2021.
Figure 1: HPL’s revenue by geographic segments
FY21 financial highlights
For full year financial results ending 31 December 2021 (“FY21”), HPL reported a 33% increase in revenue from SGD 258.8m in FY20 to SGD 344.2m in FY21. The increase in full year revenue was attributed to better performance by resorts in Maldives. Total loss after tax was SGD 5.72m which is a significant improvement from its total loss after tax of SGD 188.1m in FY20 due the hospitality industry being negatively affected by the pandemic. In addition, the gradual resumption in overseas travel also benefited its hotels in Singapore. However, hotels in other parts of South East Asia were still affected by pandemic-related restrictions.
The group’s share of results of associates and jointly controlled entities improved from a loss of SGD 42m to a loss of SGD 9m. Properties contribution declined in 2021 due to Holland Park Villas and Burlington Gate being fully sold. We expect the property contribution to pick up in 2022. Phase 1 of HPL’s Bankside Yards development in London is expected to be delivered in the second half of 2022 and practical completion of Paddington Square is also expected to be completed in the second half of 2022.
Acquisition of SPH
HPL as part of a consortium (Cuscaden Peak Pte Ltd) comprising of 40% Tiga Star Pte Ltd (70% owned by HPL and 30% owned by Como Holdings Inc), 30% Adenium Pte. Ltd. (a wholly-owned subsidiary of CLA Real Estate Holdings Pte Ltd) and 30% Mapletree Fortress Pte. Ltd. (an indirect, wholly-owned subsidiary of Mapletree Investments Pte Ltd) to acquire Singapore Press Holdings (“SPH”).
Cuscaden’s offer to SPH’s shareholders was either an all cash consideration of SGD 2.360 for each share of SPH, or a cash and units consideration of SGD 1.602 in cash and 0.782 SPH REIT units for each share of SPH. Cuscaden’s bid was rivaled by Keppel which offered a cash and units consideration of SGD 0.868 in cash and 0.782 SPH REIT and 0.596 Keppel REIT units per share. SPH shareholders rejected Keppel’s offer and voted for Cuscaden’s scheme offer. 42.1% of SPH shareholders voted for the cash and units consideration while 57.9% voted for the all cash consideration. As per Section 210 of the Companies Act 1967 of Singapore and the Singapore Code on Take-overs and Mergers, as Cuscaden will own more than 30% of SPH REIT units, Cuscaden will need to make a chain offer on SPH REIT units. As such, Cuscaden will make an offer of SGD 0.9372 in cash for each unit of SPH REIT.
The acquisition of SPH and SPH REIT will provide synergies to the existing HPL portfolio as it provides steady rental income to HPL. For SPH REIT’s first half financial results ended 28 February 2022 (“1H22), SPH REIT reported net property income of SGD 105.2m. SPH REIT has retail properties in Singapore and Australia. Paragon is located in the shopping belt of Orchard Road in Singapore and provides synergies with existing hotel properties of HPL. This acquisition will also bolster HPL’s properties segment which only contributed 6.61% of total revenues in FY21 (SGD 22.8m).
However, we expect the acquisition to increase HPL’s net gearing by a substantial amount. HPL has a net gearing ratio of 0.54x and we believe there is still some headroom for HPL to raise external financing for the acquisition.
Outlook
Singapore’s tourism is expected to pick up after easing of travel restrictions in Singapore. From April 1, all vaccinated travels will be able to enter Singapore without quarantine and the need of VTL flights. Total tourist arrivals in 1Q22 was ~246,000 and saw a 55.8% increase quarter-over-quarter. Hotel room revenue in Singapore saw a steady increase per month, reaching SGD 135.8m in Mar 2022. Average room rate and occupancy rates also saw a steady increase and we expect these numbers to increase from 1 Apr as the country eases travel restrictions.
Maldives saw steady stream of travelers to the archipelagic country in 2022. Total arrivals year to date (as of 25 Apr 2022) surpassed more than 550,000. In 2021, tourism surpassed 1.3m and at its current pace, 2022 tourism is expected to surpass 2021 levels. We expect tourism in Maldives to reach near pre-pandemic levels in 2022 (2019: ~1.7m). U.K. tourists took the top spot with a 13.1% market share as of 25 April 2022. However, Maldives is still missing its top contributor of tourism from Chinese tourists. In 2019, China topped Maldives’ tourism market share and with strict travel restrictions imposed in China, we do not expect Chinese tourism to return to Maldives in the near-term.
HPL’s hotels in Singapore are all situated in the Orchard shopping belt and will see high demand as tourism picks up. Revenues from Maldives is expected to improve as the country continues to see travel demand from international tourism.
Credit and liquidity profile
For FY21, HPL had cash and bank balances amounting to SGD 85.6m. Total borrowings for HPL was SGD 1.218b, of which SGD 156.9m were short-term borrowings. With a cash-to-short term debt ratio of 0.55x, HPL’s cash is unable to cover its short term borrowings.
In terms of gearing, HPL has an adequate gearing profile, with a net-debt-to-equity of 0.54x. Although HPL’s liquidity is weak, we think the company has headroom to refinance its borrowings with debt as seen from this new issuance where the proceeds will be used to repay its outstanding SGD 150m of HPLSP 4.650% Perpetual Corp (SGD).
Comparing HPL to another leisure and hospitality issuer, Shangri-La Asia Ltd. (“Shangri-La”), HPL has a much better credit profile. We expect some liquidity issues from HPL to improve as the hospitality industry is rejuvenated from the easing of travel and tourism.
Table 1: Comparison between HPL and Shangri-La
|
Property Developer |
Current Ratio |
Net Gearing |
LTM EBITDA Coverage |
Total Debt/Total Asset |
Net Debt/LTM EBITDA |
|
Hotel Properties |
1.04 |
0.54 |
1.75 |
34.36% |
18.67 |
|
Shangri-La Asia Ltd. |
0.65 |
0.79 |
2.46* |
41.5% |
11.49 |
|
Source: Company Financial Reports, iFAST estimates. As at 31 December 2021. *Excluding interest paid on lease liabilities |
|||||
Recommendation
Table 2: HPL and Shangri-La bonds
|
Bond name |
Issuer |
Maturity/ Next call date |
Years to maturity/ next call |
Ask price |
Yield to maturity/ next call (%) |
|
Hotel Properties Limited |
22 Oct 2024 |
2.46 |
98.0 |
5.28 |
|
| HPLSP 3.800% 02Jun2025 Corp (SGD) | Hotel Properties Limited |
02 Jun 2025 |
3.07 |
100.53 |
3.62 |
|
Hotel Properties Limited |
30 Mar 2027 |
4.89 |
100.88 |
4.00 |
|
|
Hotel Properties Limited |
31 May 2028 |
6.06 |
98.33 |
4.06 |
|
|
Shangri-La Ltd |
12 Nov 2025 |
3.51 |
103.09 |
3.56 |
|
|
Shangri-La Ltd |
29 Jan 2030 |
7.73 |
97.41 |
3.89 |
|
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 9 May 2022. |
|||||
We recommend the HPLSP 4.400% Perpetual Corp (SGD) with an indicative yield to next call of 5.28% with 2.46 years to its next call date on 22 Oct 2024. We believe that following the redemption of their HPLSP 4.650% Perpetual Corp (SGD) prior to its call date, the issuer has adequate capital management to redeem its expiring perps prior to its call date. The 4.40% perps has a call date on 22 Oct 2024 and if not called will reset at the prevailing SGD 5Y SOR + initial spread of 291.5 basis points. We prefer the HPL bonds over Shangri-La due to its better credit profile. Although we expect net gearing to increase following the acquisition of SPH, we believe that the resurgence of tourism will be able to provide HPL liquidity as earnings is expected to improve moving forward.
Conclusion
We expect tourism in Maldives and Singapore to pick up following the easing of travel restrictions globally. This will benefit HPL as majority of their revenue comes from the hospitality segment. The acquisition of SPH and SPH REIT will provide synergies to the existing HPL portfolio as it provides steady rental income to HPL. Although HPL has weak liquidity, we believe that the resumption of travel will be able to provide improved liquidity to HPL. We recommend the HPLSP 4.400% Perpetual Corp (SGD) with an indicative yield to next call of 5.28% with 2.46 years to its next call date on 22 Oct 2024. Following the redemption of their HPLSP 4.650% Perpetual Corp (SGD) prior to its call date, we believe the issuer has adequate capital management to redeem its expiring perps prior to its call date.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!











