


- Revenues for ARTSP increased by 7% to SGD 394.4m while gross profit grew by 16% to SGD 173.3m.
- Although being a hospitality trust, cash flow from operations for ARTSP remained positive even during FY20.
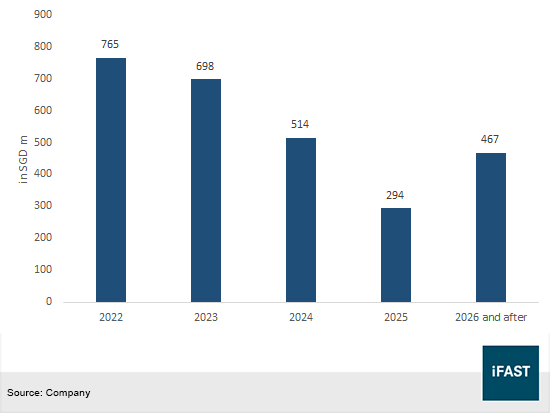
- ARTSP being an investment grade issuer has adequate liquid with enough total available funds to cover its short term borrowings of SGD 765m in 2022.
- There is a high likelihood ARTSP will redeem the 3.88% perps on its call date due to the much higher reset rate.
- We think the ARTSP 3.880% Perpetual Corp (SGD) offers quite an attractive yield to next call of 4.28% with ~2.4 years to its next call date.
Travel may soon become a reality as countries around the world start to ease Covid-19 restrictions for travellers. Expedia’s CEO Peter Kern in an interview in Feb 2022 said that he expects the summer of 2022 to be “the biggest summer ever for travel”.
One of the issuers we believe to be able to capture the growth in a resurgence of international travel is Ascott Residence Trust. The Trust continues to maintain a resilient and stable portfolio of properties that continued to generate positive cash flows despite the pandemic. In this article, we highlight the aspects of the Trust and provide our recommendations for its bonds.
About Ascott Residence Trust
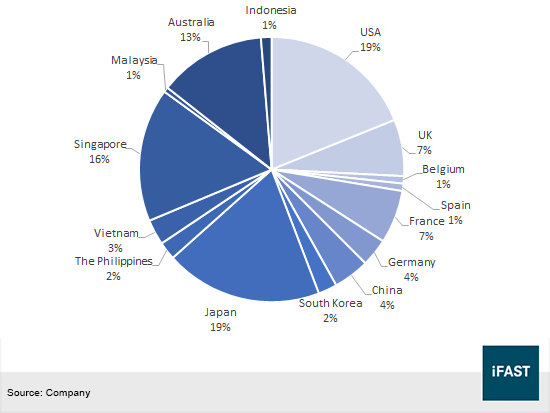
Ascott Residence Trust (“ARTSP”) is a stapled group comprising of Ascott Real Estate Investment Trust and Ascott Business Trust. ARTSP’s properties are well-diversified geographically, comprising of 93 properties across 15 countries in the Asia Pacific, Europe and the United States of America as at 31 December 2021. ARTSP operates most properties under the Ascott the Residence, Somerset, Quest and Citadines brands.
ARTSP is managed by Ascott Residence Trust Management Limited and Ascott Business Trust Management Pte. Ltd., both of which are wholly-owned subsidiaries of CapitaLand Investment Limited.
ARTSP’s properties consist of mainly hospitality properties such as serviced residences (54 properties), hotels and business hotels (18 properties), rental housing (14 properties) and student accommodation (7 properties).
Figure 1: ARTSP properties by total assets
FY21 financial highlights
For full year results ending 31 December 2021 (“FY21”), revenues for ARTSP increased by 7% to SGD 394.4m. Gross profit for FY21 was SGD 173.3m which was 16% higher as compared to the year prior. The growth in revenue was due to higher contributions of SGD 45.4m from its existing portfolio. Additionally, acquisitions of 6 student accommodations and 3 rental housing properties completed in FY21 contributed SGD 11.7m in revenue.
Although being a hospitality trust, cash flow from operations for ARTSP remained positive even during FY20. This was due to its geographical diversity and also stability from master leases and longer-stay accommodation. ARTSP is looking to build up stability and resiliency by acquiring student accommodations. In Dec 2021, ARTSP acquired 4 student accommodation properties in the USA for SGD 291.2m. ARTSP is looking to invest in 11 longer-stay assets, replacing the distributable income from ARTSP’s divestments at higher yields. We believe this shift to longer-stay accommodation will be an anchor to ARTSP’s property income, providing income stability and resiliency to the Trust.
Resurgence of international travel
More countries are easing Covid-19 restrictions and reopening their borders for international visitors. This could lead to a rebound for the leisure and hospitality industry. ARTSP operates in 8 key markets namely – Australia, China, France, Japan, Singapore, UK, USA and Vietnam. We see restrictions easing in these markets and a resurgence of international travel could benefit ARTSP.
In Europe, the EU Digital Covid Certificate was rolled out in July 2021 and allows for easier travel across the EU. From Feb 2022, the UK will no longer require Covid-19 tests and quarantine for vaccinated and unvaccinated arrivals respectively. USA and France both opened their borders to vaccinated travel. Singapore will reopen its borders to all fully vaccinated travelers, removing all existing vaccinated travel lanes.
It is also worth mentioning that France, US, China and the UK were in the top 10 most visited countries by tourist arrivals in 2019. As travel and Covid-19 restrictions start to ease around the world, we believe international travel will start picking up due to the pent up travel demand caused by the pandemic. Forecasts by The World Travel and Tourism Council (“WTTC”) projects US travel and tourism to rebound strongly this year. Their economic model predicts US domestic travel and tourism to reach more than USD 1.1t, surpassing pre-pandemic levels by 11.3% while international tourism spending to reach USD 155b (14% below 2019 levels).
Liquidity and credit profile
ARTSP has an adequate credit profile and is rated BBB- (stable) by Fitch. For FY21, total cash on hand totalled to SGD 346.3m and SGD 700m of available credit facilities. This brings its total available funds to SGD 1.04b which is enough to cover its short term borrowings of SGD 765m in 2022. Total borrowings was SGD 2.74b of which 72% consists of bank loans and 28% consisting of medium term notes.
Gearing for ARTSP is below MAS regulatory requirements at 37.1%. This gives them ~SGD 1.9b of debt headroom should ARTSP require to raise more debt for acquisitions or refinancing needs. Interest servicing ability is also adequate at 3.7x.
We are confident of ARTSP’s debt repayment ability due to its strong liquidity profile. Management have also stated that they are in the midst of refinancing loan facilities ahead of their maturity dates in 2022.
Figure 2: Debt maturity profile
Recommendation
In 2020, ARTSP decided to not redeem the ARTSP 3.070% Perpetual Corp (SGD) on its call date on 30 June 2020. The distribution rate for the perp was reset at a much lower rate from 4.68% to 3.07%. The decision to miss its call date could be due to market conditions at that time as it was during the height of the pandemic where credit spreads widened.
Looking at past perp issuances from ARTSP, the group issued SGD 150m of ARTSP 3.880% Perpetual Corp (SGD) in September 2019 and subsequently used the proceeds from the issuance to call back and redeem SGD 150m of ARTSP 5.000% Perpetual Corp (SGD) on its call date on October 2019.
Although the issuer missed its call date for its ARTSP 3.070% perps, we could see a similar situation whereby the issuer will refinance its perps by replacing it with a similar perp nearing its call date. This is because credit conditions have improved as compared to 2020 and with rising interest rates, the issuer will have a higher incentive to call back its perps as the perps will likely have a reset rate higher than its current coupon rate.
We think the ARTSP 3.880% Perpetual Corp (SGD) offers quite an attractive yield to next call of 4.28% with ~2.4 years to its next call date. ARTSP 3.880% Perpetual Corp (SGD) is due to reset on 4 September 2024 and will reset at the prevailing SGD 5Y SOR + initial spread of 2.352%. Taking reference to the 5Y SOR on 1 April 2022 of 2.51%, this would mean that the ARTSP 3.88% perps will reset at a much higher coupon rate of 4.86%. This gives a higher incentive for ARTSP to call back its perps due to higher financing costs borne. We think there is a high likelihood ARTSP will redeem the 3.88% perps on its call date due to the much higher reset rate and also the past treatment of its perps prior to the call date. Given its issuer's investment grade rating of BBB-, we think the 3.88% perps offer quite an attractive yield with about 2.4 years to its next call date.
Table 1: ARTSP SGD bonds
|
Bond name |
Issuer |
Maturity / next call |
Years to maturity / next call |
Ask price |
Yield to maturity / next call (%) |
|
ARTSP 3.070% Perpetual Corp (SGD) |
Ascott Residence Trust |
30 Jun^ 2025 |
3.25^ |
97.256 |
4.09* |
|
ARTSP 3.880% Perpetual Corp (SGD) |
Ascott Residence Trust |
04 Sep 2024 |
2.43 |
99.07 |
4.28 |
|
ARTSP 4.205% 23Nov2022 Corp (SGD) |
Ascott REIT MTN Pte Ltd |
23 Nov 2022 |
0.65 |
101.62 |
1.63 |
|
ARTSP 4.000% 22Mar2024 Corp (SGD) |
Ascott REIT MTN Pte Ltd |
22 Mar 2024 |
1.97 |
102.69 |
2.59 |
|
ARTSP 3.523% 09Nov2023 Corp (SGD) |
Ascott REIT MTN Pte Ltd |
9 Nov 2023 |
1.61 |
101.97 |
2.26 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 1 April 2022. ^Next reset date and years to next reset date respectively. *Yield to next reset on 30 Jun 2025. |
|||||
Business-related risks
A lower than expected rebound in international travel or a resurgence of new Covid-19 variants may dampen ARTSP’s recovery efforts. In 2021, there were cases where countries lifted restrictions on international travel only to close borders weeks later. Japan, for example, eased travel restrictions in November 2021 but reversed its decision after a wave of the Omicron variant. Japan have since eased its entry restrictions to only allow entry for foreigners entering the country for non-tourism related purposes such as for study and business travel.
Despite that, we remain positive on ARTSP’s operational and income generating ability due to its geographical diversity and also stability from master leases and longer-stay accommodation. ARTSP’s pivot to longer-stay accommodation may be a step in the right direction to build up resilience in its portfolio in a post-Covid world.
Conclusion
Cash flow from operations for ARTSP still remained positive even during the height of the pandemic. This was due to its geographical diversity and also stability from master leases and longer-stay accommodation. Travel may soon become a reality as international travel may start picking up due to the pent up travel demand and easing of travel restrictions. ARTSP, being an investment grade issuer have decent credit metrics and its perps are trading at an attractive yield to next call of 4.28%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in ARTSP 3.070% Perpetual Corp (SGD) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









