- Significant rebound in its Energy & Environment and Asset Management segments which contributed to the improvement in revenue.
- Net profit also increased significantly by 66% to SGD 498m as all segments reached profitability for 1H22.
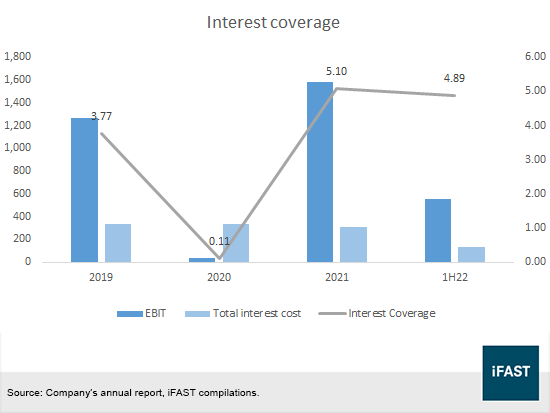
- Net gearing remains adequate at 0.68x as at 1H22 and interest coverage is approximately 4.9x.
- We think it is more likely that Keppel will call back its KEPSP 2.9% perps on its next reset date in 2026.
- We recommend the KEPSP 2.9% perps for stable income seekers with a yield to next reset of 4.81%.
Keppel Corp Limited is a large conglomerate in Singapore with diversified business segments in Energy & Environment, Urban Development, Connectivity, and Asset Management. With a market capitalisation of SGD 12.7b, it is one of the largest companies in SGX. Temasek has a shareholder interest of 20.50%.
1H22 financial highlights
For the first half financial results ending 30 June 2022 (“1H22”), Keppel delivered SGD 3.36b in revenue, an increase of 16% the year prior. Significant rebound in its Energy & Environment and Asset Management segments which contributed to the improvement in revenue. Net profit also increased significantly by 66% to SGD 498m as all segments reached profitability for 1H22.
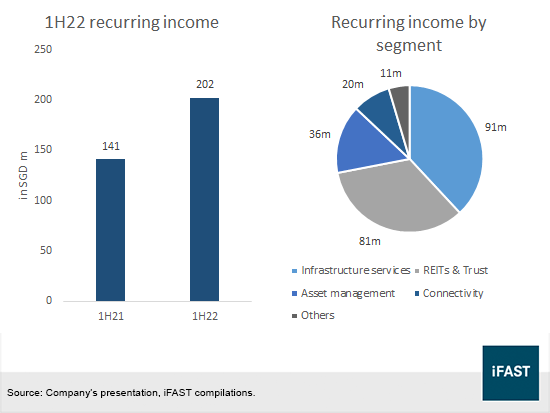
Keppel has been focusing on growing its recurring income as part of its Vision 2030 plan. Recurring income grew 43% year-on-year (“yoy”) from SGD 141m to SGD 202m. Keppel announced to monetise about SGD 3.6b of assets and so far have received SGD 2.9b of cash from its asset monetisation plan. Recently, Keppel Infrastructure Trust entered into a non-binding term sheet for 50% stake in Keppel Marina East Desalination Plant (“KMEDP”). KMEDP will be monetised through Keppel Infrastructure Trust.
Figure 1: Recurring income grew 43% YoY
Energy & Environment
Energy and environment net profit was SGD 109m including net profit of SGD 64 from discontinued operations (Keppel O&M excluding certain out-of-scope assets). The Energy & Environment segment saw profitability after a net loss of SGD 179m in 2021, mainly due to stronger performance from Keppel Infrastructure. Keppel Infrastructure’s net profit improved by 77% yoy, and embarked on several projects in renewables, carbon capture and floating solar solutions.
In 1H22, Keppel O&M’s net profits improved to SGD 64m from a net loss of SGD 44m. Keppel O&M secured SGD 256m of new orders and net order book for 1H22 reached SGD 4.4b. Regarding the proposed Keppel O&M transactions, Keppel hopes to complete the proposed transaction with Sembcorp Marine by the end of 2022. The total realisable value from the transaction is expected to be approximately SGD 9.4b.
Urban Development
Keppel was affected by headwinds in the China and Vietnam markets. Urban Development’s net profit fell by 40% to SGD 168m in 1H22 from SGD 279m in 1H21. Keppel Land sold 1,010 homes in 1H22 as compared to 2,650 the year prior. The China property market is expected to have several headwinds, affected by the fall in home sales and the fall in average selling price in some cities. In the medium-term, we expect the property market in China to pose some challenge to Keppel due to the deleveraging policies and COVID-19 lockdowns in China. Over the long-term, we expect Keppel to monetise its sizable landbank in China and Vietnam as it seeks to be an asset-light developer providing urban development solutions.
Connectivity
Net profit fell 63% to SGD 168m due to the absence of gain from disposal of interests in Keppel Logistics (Foshan). Keppel announced a data centre project in China, its 6th data centre project since entering China in 2020.
M1’s earnings improved 62% due to its transformation plans as well as the increase in roaming and prepaid revenues from the reopening of economies. China contributes significantly to M1’s roaming revenues and with the China economy yet to reopen, M1’s roaming revenues is still half of pre-COVID levels. Roaming revenue from M1 will contribute significantly to net profits when China reopens its borders.
Asset Management
For Asset Management, net profit rose by 32% to SGD 155m from higher fee income as well as higher share of fair value gains on investment properties and data centres. Asset management fees grew 14% to SGD 125m, boosting Keppel’s recurring income. For 1H22, Keppel completed a total of SGD 3.3b of acquisitions and divestments as Keppel continues its asset monetisation plan.
Table 1: Net profit by operating segments
|
(SGD m) |
1H22 |
1H21 |
Change |
|
Energy & Environment |
45 |
(135) |
N.M. |
|
Urban Development |
168 |
279 |
(40%) |
|
Connectivity |
10 |
27 |
(63%) |
|
Asset Management |
155 |
117 |
32% |
|
Corporate & Others |
56 |
56 |
- |
|
Discontinued Operations* |
64 |
(44) |
N.M. |
|
Source: Company’s presentation, iFAST compilations. *Keppel O&M excluding certain out-of-scope assets |
|||
Credit profile
As of 1H22, Keppel had SGD 1.79b of cash and cash equivalents and total borrowings of ~SGD 10.4b of which SGD 3.5b are short-term borrowings. As of 31 December 2021, Keppel had SGD 8.08b of total available credit facilities. Net gearing remains adequate at 0.68x as at 1H22 and interest coverage is approximately 4.9x. Net gearing has seen a slight reduction from 0.85x in 2019 to 0.68x in 1H22.
Figure 2: Keppel’s net gearing
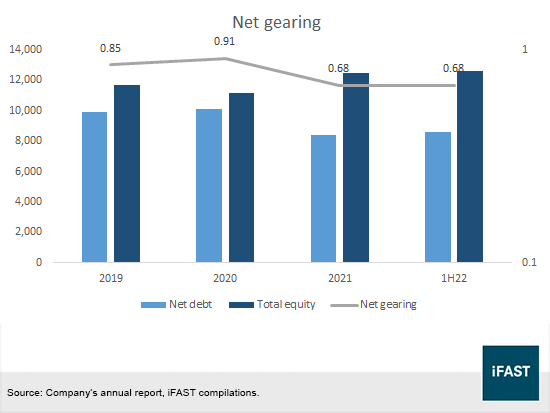
Figure 3: Keppel’s interest coverage
Recommendation
At first glance, the KEPSP 2.900% Perpetual Corp (SGD) looks attractive at its indicative yield to call of 6.06%. The bond is callable in 2024 and has around 2.08 years to its next call date. The bond have largely been sold off as the market have priced in a non-call from the issuer. This is because the bonds do not reset on the call date in 2024 but have a later reset date in 2026. Having a much later reset date does not provide much incentive for the issuer to call the notes in 2024 and the issuer would rather wait till its reset date before calling the notes. Given the current credit conditions, it would be more costly for Keppel to call back the notes on 2024 and refinance it with a new bond as they would incur higher interest expenses from the refinancing.
Taking a deeper look at the KEPSP 2.9%, its yield to next reset (on 16 Sep 2026) is calculated to be 4.81% with 4.08 years to its next reset date. This yield makes more sense for the credit profile of Keppel and is in line with perps of other Temasek-linked companies like Mapletree Logistics Trust and Mapletree Industrial Trust, whose notes are also callable in 2026 (Table 3).
We think it is more likely that Keppel will call back its KEPSP 2.9% perps on its next reset date as the notes will reset at prevailing SGD 5-year SORA OIS plus the initial spread of 2.097% and an additional 100 basis point step up margin. Compared to MLTSP 3.725% Perpetual Corp (SGD) (YTC: 4.72%) and MINTSP 3.150% Perpetual Corp (SGD) (YTC: 4.98%), both notes do not have an additional step up margin. Thus, we think the KEPSP 2.9% notes with the additional step up margin gives Keppel much more incentive to call. We think the KEPSP 2.9% perp will be suitable for stable income seekers who wish to invest in stable income during these times of uncertainty in the markets.
At first glance, investors might jump at the opportunity of holding a Keppel bond that is yielding over 6%, but after looking deeper, we think it is likely that the notes is actually being priced at a yield to next reset of 4.81%. With that said, we still think the KEPSP 2.9% is a good option for stable income seekers but for high yield seekers who wish to gain the 6.06% yield to call, we think it is unlikely that the notes will be called in 2024 due to the structure of the notes.
Table 2: Relative Valuation of KEPSP with other perpetual bonds callable in 2024
|
Bond name |
Issuer |
Next Call Date |
Years to next call |
Ask price |
Yield to call |
|
KEPSP 2.900% Perpetual Corp (SGD) |
Keppel Corporation Ltd |
16 Sep 2024 |
2.08 |
93.90 |
6.06% |
|
HPLSP 4.400% Perpetual Corp (SGD) |
Hotel Properties Ltd |
22 Oct 2024 |
2.18 |
95.05 |
6.88% |
|
CAPLSP 3.650% Perpetual Corp (SGD) |
CapitaLand Treasury Ltd |
17 Oct 2024 |
2.17 |
98.37 |
4.45% |
|
ARTSP 3.880% Perpetual Corp (SGD) |
Ascott Residence Trust |
04 Sep 2024 |
2.05 |
97.69 |
5.07% |
|
SPHRSP 4.100% Perpetual Corp (SGD) |
SPH REIT |
30 Aug 2024 |
2.04 |
98.63 |
4.82% |
|
MAPLSP 3.700% Perpetual Corp (SGD) |
Mapletree Treasury Services Limited |
12 Aug 2024 |
1.99 |
95.94 |
3.86% |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 17 Aug 2022. |
|||||
Table 3: Relative Valuation of KEPSP with other perpetual bonds callable in 2026
|
Bond name |
Issuer |
Next Call Date |
Years to next call |
Ask price |
Yield to call |
|
KEPSP 2.900% Perpetual Corp (SGD) |
Keppel Corporation Ltd |
16 Sep 2026* |
4.08* |
93.90 |
4.81%* |
|
CERTSP 5.000% Perpetual Corp (SGD) |
Cromwell European REIT |
24 Nov 2026 |
4.27 |
92.50 |
7.06% |
|
MLTSP 3.725% Perpetual Corp (SGD) |
Mapletree Logistics Trust |
02 Nov 2026 |
4.21 |
96.21 |
4.72% |
|
ARASP 5.600% Perpetual Corp (SGD) |
ARA Asset Management Ltd |
04 Sep 2026 |
4.05 |
98.06 |
6.14% |
|
AAREIT 5.375% Perpetual Corp (SGD) |
AIMS APAC REIT |
1 Sep 2026 |
4.04 |
99.22 |
5.59% |
|
SUNSP 4.250% Perpetual Corp (SGD) |
Suntec REIT |
15 Jun 2026 |
3.83 |
95.24 |
5.65% |
|
MAGIC 3.500% Perpetual Corp (SGD) |
Mapletree North Asia Commercial Trust |
08 Jun 2026 |
3.81 |
91.59 |
6.00% |
|
LREIT 4.200% Perpetual Corp (SGD) |
Lendlease Global Commercial REIT |
4 Jun 2026 |
3.80 |
96.59 |
5.20% |
|
MINTSP 3.150% Perpetual Corp (SGD) |
Mapletree Industrial Trust Treasury Co Pte Ltd |
11 May 2026 |
3.73 |
93.82 |
4.98% |
|
ESRCAY 5.650% Perpetual Corp (SGD) |
ESR Group Limited |
2 Mar 2026 |
3.54 |
96.53 |
6.76% |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 17 Aug 2022. *Where applicable, next reset date, yield to reset, and yield to reset |
|||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in KEPSP 2.900% Perpetual Corp (SGD) and MLTSP 3.725% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.