


Highlights:
- Just Group provides pension solutions and management services. Its customers have a higher degree of stickiness on the core products. The new business sales are strong. The high growth trend is likely to continue.
- Benefiting from the rate hike cycles, Just Group’s liquidity is improving continuously. Also, the Group’s leverage ratio was the lowest amongst its peers. The leverage level is quite decent.
- Investors could consider Just Group’s GBP bonds, with the yield to maturity of 6.6% to 8.2%.
Provide Pension Solutions and Management Services; High Degree of Customer Stickiness on Core Products
Just Group PLC (“Just Group”) is a UK-based financial services group that provides pension solutions and management services. The Group is listed on the London Stock Exchange (Stock Code: JUST.LN) and has a current market capitalization of around GBP 880 million.
Just Group offers a range of products and services (see Table 1), with its core product being defined benefit de-risking solutions (“DB”), which account for up to 80% of its insurance premium. These DB products incur stable cash flows for the company, as the trustees and contributors to pension schemes are large financial institutions and employers respectively, who have a high degree of customer stickiness.
This type of DB product is extremely important to trustees as it helps them to minimise their financial risk. Because of the long service life of pension schemes, it is difficult to switch to a similar service from another company once you have used Just Group's service, so there is rarely any switching of the customers’ subscriptions.
Table 1: A List of Just Group’s Products and Services
|
Product / Service Name |
Illustration |
Main Targets |
|
Defined Benefit De-risking Solutions (“DB”) |
Solutions for pension scheme trustees to reduce financial risks of operating pension schemes and increase certainty that members’ pensions will be paid in the future |
Pension Scheme Trustees |
|
Guaranteed Income for Life (“GIFL”) |
A solution for individuals/couples who want the security of knowing they will receive a guaranteed income for life |
Individuals / Couples |
|
Secure Lifetime Income (“SLI”) |
A solution for individuals which is tax-efficient and allows the flexibility to make changes in the plan of receiving a guaranteed income |
Individuals |
|
Care Plans (“CP”) |
A solution for people moving to residential care who want the security of knowing a regular payment will be made to the care provider |
The Elderly |
|
Lifetime Mortgages (“LTM”) |
A solution for property owners to pledge their properties to borrow funds |
Property Owners |
|
Hub Group |
Provide technology, brokerage and consulting services to institutional clients or pension schemes |
Potential and Existing Clients |
|
Sources: Company’s Reports, iFAST Compilations Data as of 30 June 2023 |
||
New Business Sales are Strong; High Growth Trend is Likely to Continue
As shown in Chart 1, in the first half of 2023, Just Group’s new business sales reached GBP 1.90 billion, which significantly increased by 116% YoY. The overall performance is decent. The new business margin was stable at around 8.5%.
Just Group expects that in the second half of this year, the DB sales income will be higher than or close to that in the first half year. Over the past five years, DB sales income’s CAGR reached 18.2%. The rapid growth drives the overall new business sales to reach a double-digit growth.
Chart 1: Just Group’s New Business Sales and Margin
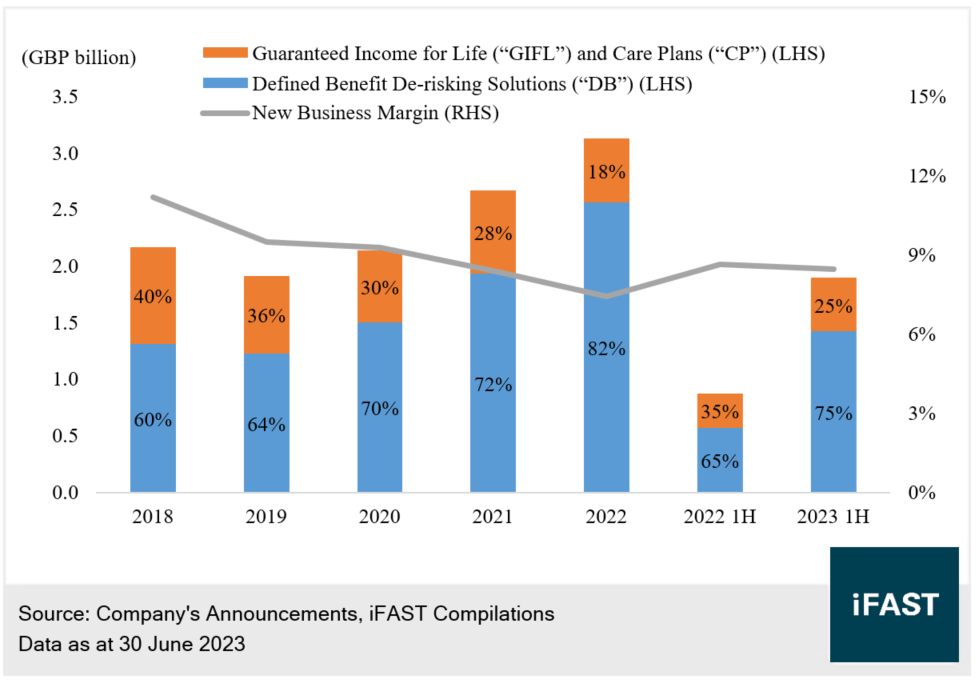
Since 2012, the UK has introduced an auto-enrollment policy for pensions. Employers must enroll employees in a pension scheme and make contributions on their behalf. The government required employers to increase the contribution rate in 2018. With the high inflation, rising wages and the trend that employers are gradually replacing the original employee benefits with pension schemes, we believe that the high growth trend of DB is likely to continue.
Currently, DB accounts for around 75% of new business sales revenue. The contribution of DB will continue to increase with a better DB’s growth, so it is a business that is increasingly influential for the Group.
In terms of profitability, Just Group's main profit sources can be attributed to two parts: (1) Profits from New Business as mentioned above and (2) In-force Profit, which consists mainly of investment income, Contractual Service Margin amortization and the risk reserve provision/surplus, etc.
As shown in Chart 2, in the first half of 2023, Just Group’s underlying operating profit after attributed tax increased 140% YoY to GBP 130 million, driven by the significant increase in profits from new business and better returns on the investment portfolio. The annualised return on equity in the same period also rose 225 bps to 13.0%. These reflected the strong performance in profitability.
Chart 2: Just Group’s Underlying Operating Profit After Attributed Tax and Return on Equity
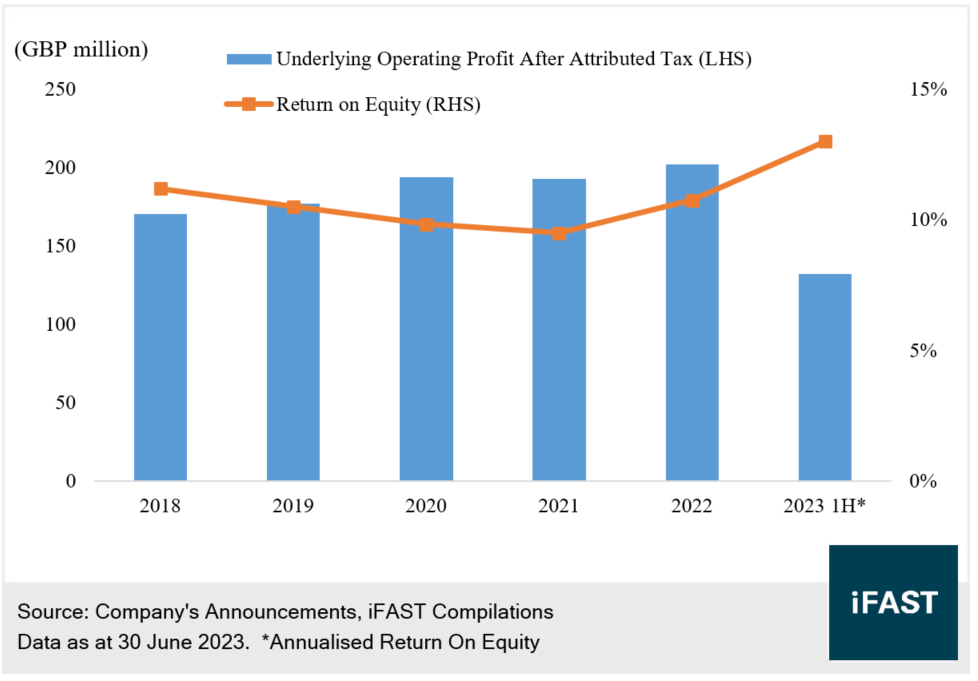
In the short to medium term, Just Group is targeting core operating profit growth of 15% per annum, based on new business profits driven by the high rate of DB growth. We believe this growth target may be a bit aggressive, as in-force profit is more susceptible to market conditions, and overall new business sales are only growing at around 10%. However, it is not difficult to maintain high single-digit core operating profit growth. The Group still has good growth capacity.
Benefited From Rate Hike Cycles, the Group’s Liquidity is Improving Continuously
Benefiting from the rate hike cycle across the globe, the widening margins in the insurance sector are expected to boost the earnings, net book value and embedded value of major insurance companies. In general, their asset sides are less sensitive to interest rates than the liability side (since the portfolio duration is shorter than that of insurance policies). Also, driven by an increase in interest rates, the portfolio's expected return is higher.
Additionally, their capital requirements are generally reduced under the scenario stress tests due to higher discount rates, driving their capital adequacy ratios. As a result, their capital adequacy ratios are expected to be improved, enhancing their solvency.
Just Group is also one of the beneficiaries of this wave of rate hikes. As seen in Chart 3, Just Group's shareholder capital coverage ratio (total eligible own funds/solvency capital requirement) increased to 204% in the first half of 2023, reflecting the continued improvement in the Group's liquidity.
Chart 3: Just Group’s Shareholder Capital Coverage Ratio
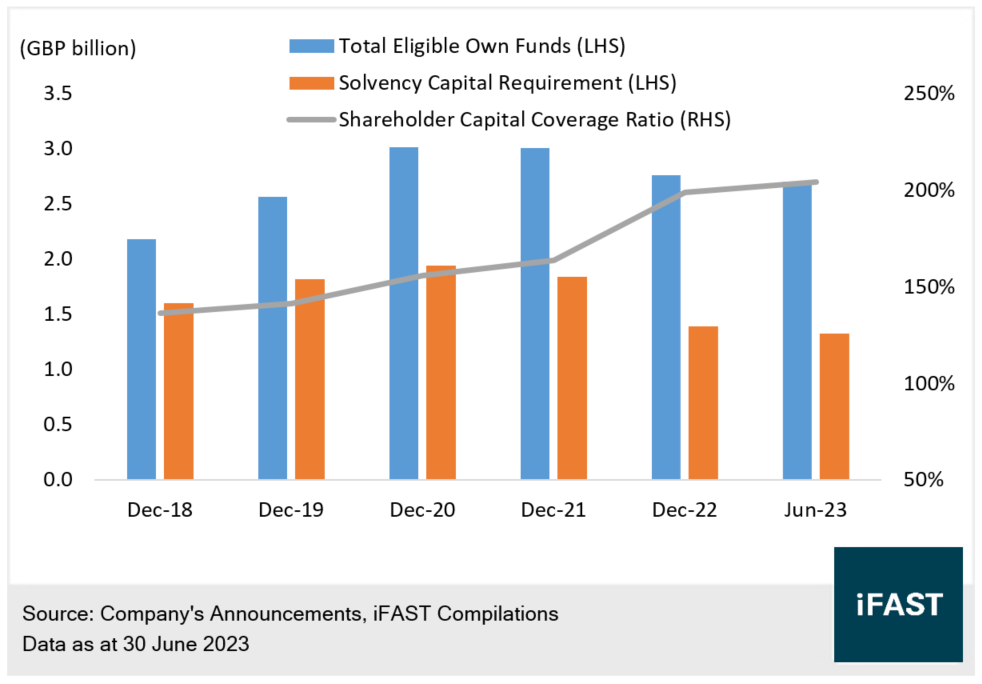
Compared to the peers (see Table 2), the Group’s shareholder capital coverage ratio was slightly higher than the peers’, and it was still much larger than the Solvency II regulatory requirement, i.e. 100%. The Group’s leverage ratio was the lowest amongst the peers. The leverage level is quite decent.
Table 2: The Peers’ Shareholder Capital Coverage Ratios and Leverage Ratios
|
|
Shareholder Capital Coverage (%) |
Adjusted Leverage Ratio (%) |
|
Just Group |
204% |
22% |
|
Phoenix Group* |
189% |
30% |
|
Legal & General |
230% |
28% |
|
Aviva |
202% |
30% |
|
Admiral Group |
182% |
53% |
|
Direct Line Insurance Group* |
147% |
24% |
|
Adjusted Leverage Ratio = Total Debt / (Total Debt + Total Equity + Contractual Service Margin Surplus), the lower is better Sources: Company Reports, iFAST Compilations Data as at 30 June 2023 *Data as at 31 December 2022 |
||
Investors could Consider GBP Bonds with yield to maturity of 6.6% to 8.2%
Investors looking to hold GBP assets could consider investing in Just Group's GBP bonds, which currently offer net yield to maturity of 6.6% to 8.2% (see Table 3). It is worth investors’ attention.
The Group’s issuer credit rating is A (Fitch). The bond credit rating is either BBB or BBB+ (Fitch), belonging to investment grade.
Table 3: Just Group’s Bonds
|
Bond Name |
Years To Maturity |
Issuer |
Guarantor |
Bond Credit Rating (Fitch) |
Ask Price (Investors Buy) |
Yield To Maturity (%) |
| JUSTLN 3.500% 07Feb2025 Corp (GBP) | 1.4 |
Just Group |
/ |
BBB |
94.6 |
7.6% |
| JUSTLN 9.000% 26Oct2026 Corp (GBP) | 3.1 |
Just Group |
Just Retirement Ltd |
BBB+ |
106.7 |
6.6% |
| JUSTLN 8.125% 26Oct2029 Corp (GBP) | 6.1 |
Just Group |
/ |
BBB |
101.4 |
8.2% |
|
Source: Bondsupermart Data as of 15 September 2023 |
||||||
This bond does not have a call date, a coupon reset date or a loss absorption feature (it has more advantages compared to normal bank bonds). But there are two features of this bond, namely deferred interest payment and extendable tenor. If the regulatory authority makes a judgement that the Group falls into operation crisis, the Group might need to suspend paying coupons (and accumulate the coupons until the regulatory authority approves it to pay coupons again) or/and delay the maturity date of the bond. Under these circumstances, the bond is not still considered as defaulted.
Related Risks
Features of the bond include deferred interest payment and extendable tenor. Hence, the bond credit rating is lower than the issuer’s credit rating. It is riskier than general bonds.
Just Group's growth prospects depend on the UK pension schemes. If there is a change in the policy about pension schemes, it could result in a large deterioration in the new business sales, which in turn could affect the Group's profitability.
In addition, if the UK economy were to fall into recession and local employers were to substantially lay off employees or reduce the salaries of their remaining staff, these would affect product sales, resulting in a decline in the Group's revenue and profitability.
Structurally, these bonds are all subordinated bonds. In the event of bankruptcy and liquidation, the bondholders would be in an unfavorable position.
Conclusion
Just Group provides the pension solutions and management services. Its customers have a higher degree of stickiness on the core products. The new business sales are strong. The high growth trend is likely to continue.
Benefiting from the rate hike cycles, Just Group’s liquidity is improving continuously. Also, the Group’s leverage ratio was the lowest amongst the peers. The leverage level is quite decent.
Investors could consider the GBP bonds, with the yield to maturity of 6.6% to 8.2%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.











