


Highlights:
- New World Development has made a number of moves in recent years and is quite aggressive in style. Its overall performance is solid, with a more resilient profit structure. The "Northern Metropolis" policy will accelerate the conversion of agricultural land, K11 properties will support earnings growth upon subsequent completion.
- The Group’s credit risk is not high, with actual liquidity pressure being not significant. The Group is still able to raise funds by issuing bonds, which reflects a good financing ability.
- The Group’s USD bond due in 2027 has an attractive current yield to maturity of around 5.7%.
Several Moves Have Been Made in Recent Years with An Aggressive Style
New World Development Company Limited (abbreviated “New World” hereafter) is one of the large property developers in Hong Kong. It engages in property development, property investment, hotel operation, roads, infrastructure, insurance, department stores and other strategic businesses. New World was listed on Hong Kong Stock Exchange (Ticker: 17.HK), with its current market capitalisation of around HKD 65.2 billion. New World also holds a number of listed companies, including NWS Holdings (Stock Code: 659.HK) that engages in roads, infrastructure and insurance and New World Department Store China (Stock Code: 825.HK), a department store business.
In recent years, New World has made a number of significant moves, including the purchase of FT Life from JD Capital, the exit of its aircraft leasing, public bus, ferry and environmental businesses. New World plans to dispose its non-core assets of about HKD 10 billion which includes car parking spaces, hotels in operating loss and non-controlling projects in the next two years. New World has also invested over tens of billions in property projects in the Greater Bay Area and has been developing its K11-branded investment properties, aiming at generating at least half of its core profit in FY2024 as sustainable profit. New World is quite aggressive in terms of style compared to those large Hong Kong Property developers which are generally more conservative. So, how is New World doing with its grand plans?
Solid Overall Performance and More Resilient Profit Structure
In the first half of FY2022 (from July to December 2021), New World's total property contracted sales amounted to around HKD 13.2 billion which decreased by 65% YoY. The fall is mainly due to the lack of pre-sales of large-scale projects in Hong Kong. In the first half of FY2021, the Pavilia Farm project in Hong Kong is included in the pre-sales figures. The total revenue for the same period reached HKD 35.6 billion, it is roughly flat YoY, yet core profit increased by 5% YoY to HKD 3.9 billion. The gross profit margin has increased from 26.2% to 28.3% in the same period last year. These represent a solid overall performance.
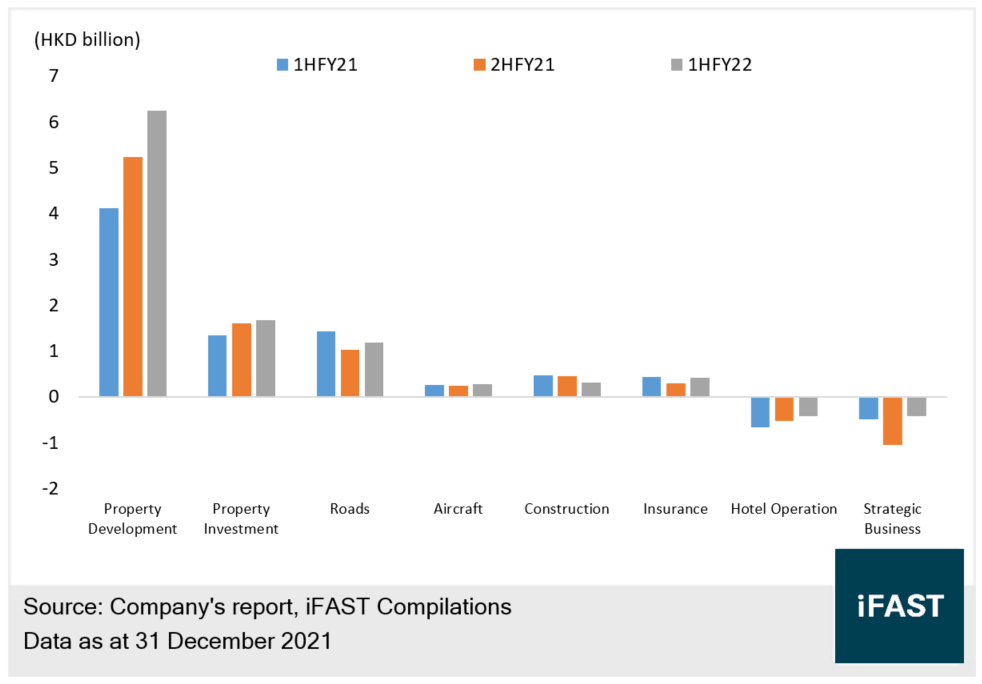
As shown in Table 1, New World’s major profit is still generated from property development (accounting for over 50% of the Group's profit). New World views the profit from property development as non-sustainable profit and focuses on other businesses with higher sustainability and more stable cash flows like property investment, roads, construction and insurance businesses. We believe that the profit contribution from these four businesses will continue to increase in the coming years.
In addition, New World has already exited the aircraft business as well as businesses that continually experience operating losses (transportation and environmental businesses). New World also hopes to gradually sell a part of its hotel businesses. This is expected to narrow down the losses of the hotel and strategic businesses and make New World’s profit structure more resilient.
Table 1: New World Development’s Segment Profits (Including Attributable Profits From JVs and associates, Excluding the Change in Fair Value of Investment Properties)
In terms of Mainland China’s sales, New World's total contracted sales for the first half of FY2022 amounted to RMB 9.34 billion, its average selling price is RMB 38,000 per square meter. The high selling price is because New World focuses on developing mid-to-high-end projects in first-tier cities. This approach is quite different from other mainstream Chinese property developers. The average gross profit margins of these mid-to-high-end projects range from 40% to 50%, or even reaching 70% margin for some projects, which is much higher than that of its peers.
Despite the worsened market sentiment affected by the Chinese real estate debt crisis and the fact that Chinese homebuyers refuse to repay mortgage for abandoned projects, we believe the impact on New World will be relatively mild. It is because of (1) New World’s Hong Kong background which gives homebuyers more confidence in its capital strength, and (2) the fact that its projects located in the core areas of the city that have more supporting facilities nearby. Homebuyers are thus more willing to buy these types of units.
For example, New World sold out all 601 units within one day in the first round pre-sale of the “New World Hangzhou Arts Centre River Opus” in June this year. The subscription amount is exceeding RMB 7 billion. It is reflected that its sales capacity are not affected by the poor market sentiment in the property sector.
The "Northern Metropolis" Policy will Accelerate Conversion of Agricultural Land; K11 Properties Will Support Earnings Growth upon Completion
The Hong Kong Government proposed a “Northern Metropolis Development Strategy” in the 2021 Policy Address, spanning 300 square kilometers across the northern New Territories like Yuen Long, Sheung Shui, Fanling, Kwu Tung, Lok Ma Chau and Man Kam To. This policy is to address the shortage of housing supply in Hong Kong. Although this development strategy is still a preliminary plan, we believe that it will facilitate the discussion with the government in accelerating the conversion of the agricultural land and replenishing its land reserve. It will be beneficial to New World’s medium to long-term development.
As shown in Table 2 and 3, as of the end of December 2021, New World has approximately 4.88 million square feet of attributable land reserve for immediate development in Hong Kong and around 16.27 million square feet of attributable agricultural land, of which nearly 90% of them are located in the Northern Metropolitan Region. We estimate that New World’s current saleable resources are at around HKD 48-55 billion and potential saleable resources related to agricultural land of HKD 950-1,450 billion. Based on New World’s current contracted sales target of HKD 20 billion in Hong Kong, if the conversion of agricultural land goes smoothly, these reserves will be more than sufficient to support New World’s development needs for many years to come.
Table 2: The Group’s Attributable Land Reserve for Hong Kong Property Development
|
Attributable Gross Floor Area (thousand square feet) |
Estimated Salable Resources* |
|
|
Hong Kong Island |
770 |
/ |
|
Kowloon |
2,060 |
/ |
|
New Territories |
2,050 |
/ |
|
Total |
4,110 |
HKD 48 billion to HKD 55 billion |
|
*Assume the efficiency rate (salable floor area to gross floor area) of 70% to 80% and average selling price of HKD 14,000 per square feet Source: Company’s report, iFAST Compilations Data as at 31 December 2021 |
||
Table 3: The Group’s Attributable Potential Land Bank from Agricultural Land
|
Attributable Land Area (thousand square feet) |
Estimated Salable Resources* |
|
|
Northern Metropolitan Region |
13,380 |
/ |
|
- Yuen Long Region |
11,200 |
/ |
|
- North District |
2,180 |
/ |
|
Other New Territories Regions |
2,880 |
/ |
|
Total |
16,270 |
HKD 950 billion to HKD 1450 billion |
|
*Assume the plot ratio of 6 times to 8 times, the efficiency rate (salable floor area to gross floor area) of 70% to 80% and the average selling price of HKD 14,000 per square feet Source: Company’s report, iFAST Compilations Data as at 31 December 2021 |
||
Aside from the conversion of agricultural land, New World’s K11-branded investment properties (including malls, offices and hotels) also drive its growth, this portfolio will increase from the current 1.356 million square feet to 2.794 million square feet by the end of June 2026, representing a CAGR of around 17.4% (see Table 4). Upon completion of these K11 investment properties, New World’s rental revenues and support its earnings growth will be boosted (1H FY2022: property investment income of around HKD 2.52 billion and segment profit of around HKD 1.68 billion).
Table 4: Completion Date of New World’s K11-branded Investment Properties
| Completion date | Place | Gross Floor Area (thousand square feet) | Accumulated Gross Floor Area (thousand square feet) |
| Existing | Hong Kong | 321 | 1,356 |
| Mainland China | 1,035 | ||
| FY 2022 | Mainland China | 9 | 1,365 |
| FY 2023 | Hong Kong | 52.5 | 1,558 |
| Mainland China | 140 | ||
| FY 2024 | Hong Kong | 354.5 | 2,139 |
| Mainland China | 227 | ||
| FY 2025 | Mainland China | 422 | 2,561 |
| FY 2026 | Mainland China | 230 | 2,794 |
| Source:
Company’s Presentation, iFAST Compilations Data as at 31 December 2021 |
|||
Low Credit Risk and Actual Liquidity Pressure
In terms of credit profile, at the end of 2021, New World’s total assets amounted to HKD 639.7 billion, the adjusted net gearing ratio is approximately 63.9% (see Table 5), representing a moderate level of leverage. Despite New World having merely 0.9 times of cash to short term debt ratio (around HKD 55.6 billion short term debt), it has an undrawn credit facility of HKD 51 billion for refinancing. Its average cost of borrowing is at 2.5% which is extremely low. This reflects its low credit risk and high refinancing ability. The actual liquidity pressure is not significant.
Table 5: New World’s Credit Indicators
|
June 2021 |
December 2021 |
|
|
Total Asset (HKD billion) |
639.7 |
627.1 |
|
Total Debt (HKD billion) |
225.0 |
227.2 |
|
Total Cash (HKD billion) |
62.0 |
52.4 |
|
Adjusted Net Gearing Ratio (%)* |
63.9% |
68.1% |
|
Cash to Short-term Debt (times) |
1.6 times |
0.9 times |
|
Average Cost of Borrowing (%) |
2.9% |
2.5% |
|
Short-term Debt to Total Debt (%)* |
17.0% |
24.5% |
|
*Include Perpetual debt Sources: Company’s Reports, iFAST compilations Data as at 31 December 2021 |
||
Still Able to Raise Funds by Issuing Bonds, Showing Good Financing Ability
It is worth mentioning that investors may worry about the refinancing risk brought by New World’s bank loans and bond issuance. Generally speaking, the refinancing terms of bank loans are dependent on New World's operating condition, profitability and industry prospect.
At present, New World's operating conditions remain strong. The diversified businesses help to diversify the individual industry and business risks. Although property sales still account for more than 50% of its profit (roughly half in Hong Kong and half in the Mainland China), more sustainable businesses (such as investment properties, roads, insurance and construction) have more stable cash flows. As such, we believe that New World is not comparable to Chinese property developers which only have single business and face industry risks. Banks would also assess the above-mentioned factors. Therefore, we believe that New World will still be able to get loan renewals or refinancing from banks under normal circumstances.
As for the bond market, the prices of many New World USD bonds remain resilient. Most of them are still within a safe range of at least $80 or above. Although it is inevitable for New World to issue new bonds at a higher cost, it is still able to raise funds, given the solid operating performance and a number of businesses with relatively stable cash flows. For example, in June 2022, New World issued a USD 200 million, five-year social bond and a USD 500 million perpetual green bond. Both of them were oversubscribed by nearly five times, reflecting the market confidence in its credit profile and a good financing ability.
Attractive Current Yield to Maturity of Around 5.7% for the Bond Due in 2027
Even though New World and its bonds are not rated, it does not mean that their credit profile is poor. Currently, there are a number of New World's USD or HKD bonds available on the FSMOne platform for investors to choose from (see Table 6 and Table 7).
Considering the fact that New World is expected to benefit from the "Northern Metropolis" policy, as well as its boosted recurring revenues because of the completion of K11 investment properties, and the active disposal of non-core assets and exiting non-core businesses by its management, we believe that New World’s solvency is strong and the default risk of its short-and-medium term bonds is low.
Combining factors such as the tenor and yield, we think that the bond due in 2027, “NWDEVL 5.875% 16JUN2027 CORP (USD)” has a higher attractiveness. Its current yield to maturity is around 5.7%. Investors could also select bonds according to your personal financial goals.
However, investors have to pay attention that each New World’s perpetual bond has different terms and next call dates (Table 7) with complicated details. In terms of yields, these perpetual bonds are not very attractive. Thus, we believe that investors should prioritise considering non-perpetual bonds (Table 6).
Table 6: New World’s Non-perpetual Bonds
|
Bond Name |
Currency |
Years to Maturity |
Ask Price (Investor Buys) |
Net Yield to Maturity |
|
HKD |
1.6 |
101.9 |
4.0% |
|
|
USD |
4.9 |
100.2 |
5.7% |
|
|
HKD |
6.8 |
93.2 |
5.0% |
|
|
USD |
7.8 |
88.5 |
6.4% |
|
|
USD |
8.4 |
82.7 |
6.4% |
|
|
Source: Bondsupermart Data as at 5 August 2022 |
||||
Table 7: New World’s Perpetual Bonds
|
Bond Name |
Currency |
Next Call Date |
Ask Price (Investor Buys) |
Yield to Call |
Yield to Maturity |
|
USD |
March 2026 |
90.5 |
8.4% |
5.8% |
|
|
USD |
March 2025 |
95.6 |
8.3% |
6.4% |
|
|
USD |
September 2023 |
71.0 |
45.0% |
6.5% |
|
|
USD |
March 2028 |
78.8 |
8.9% |
9.1% |
|
|
Source: Bondsupermart Data as at 5 August 2022 |
|||||
Related Risks
If the interest rate hike cycle continues because New World's gearing ratio is higher than other Hong Kong developers (such as Sun Hung Kai Properties, CK Asset Holdings, Henderson Land and Sino Land), New World's interest expenses will increase even more, which will further affect New World’s profitability.
In addition, the interest rate hike cycle may affect Hong Kong people's desire to purchase residential properties. It may require price reductions for promotions or accept a lower sell-through rate. At the same time, theoretically, an increase in the interest rate will put a certain degree of downward pressure on Hong Kong property prices.
The major debt of New World is bank loans. If the renewal or refinancing of bank loans is affected by some systemic risks in financial systems or industry risks, New World’s liquidity will be pressured.
New World has a rather aggressive approach, which may lead to higher capital expenditure and land acquisition cost. These may affect its cash flow performance.
Conclusion
New World Development has made a number of moves in recent years and is quite aggressive in style. Its overall performance is solid, with a more resilient profit structure. The "Northern Metropolis" policy will accelerate the conversion of agricultural land, K11 properties will support earnings growth upon subsequent completion.
The Group’s credit risk is not high, with actual liquidity pressure being not significant. The Group is still able to raise funds by issuing bonds, which reflects a good financing ability.
The Group’s USD bond due in 2027 has an
attractive current yield to maturity of around 5.7%.










