


Olam Group (“Olam”) reported strong results for their full year 2021 financial report ending 31 December 2021. However, bond prices of Olam’s bonds fell after the announcement of their consent solicitation exercise as Olam proposed to amend several terms of its Notes.
On top of that, Olam is one of the few SGD issuers that have exposure to the Russia and Ukraine crisis in Europe. In this article, we highlight the key changes of the consent solicitation exercise passed by Olam’s noteholders as well as Olam’s impact from their exposure to Russia and Ukraine.
FY21 financial highlights
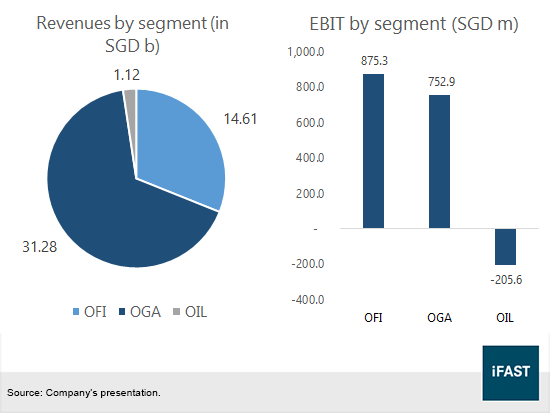
For full year results ending 31 December 2021 (“FY21”), revenues for Olam increased by 31.2% to SGD 47.00b while EBITDA also increased by 25.7% to SGD 2.05b. The improvement in revenues were largely attributed to higher commodity prices such as grains, rice, cotton, cocoa and edible oils. Total sales volume increased by 2.3% to 45.4m metric tonnes, largely contributed by Olam Global Agri (“OGA”).
Figure 1: Olam’s FY21 results
Olde Thompson acquisition provides additional synergies
OFI, or Olam Food Ingredients provides sustainable, natural and healthy products to end consumers. OFI caters to trending food-groups who have a growing appetite for healthier, traceable foods from sustainable sources.
For FY21, OFI was the best performing segment with an EBIT growth of 16.8% to SGD875.3m, as Global Sourcing and Ingredients & Solutions segments continue to grow. In OFI’s ingredients & solutions segment, the acquisition of Olde Thompson provides additional synergies for OFI’s existing businesses, however, margins were impacted due to the labour cost inflation as well as supply chain disruptions in the US. Margins are expected to normalise in 2022 and OFI’s EBIT margin to improve in FY22.
Strong recovery of cotton for OGA
OGA, or Olam Global Agri is a food, feed and fibre global agri-business that primarily operates in emerging markets, particularly Asia and Africa. OGA focuses on providing proteins to consumers in these regions and it has been operating in these markets for more than 30 years.
For OGA, the segment reported strong EBIT growth of 42.7% to SGD 267m due to a strong recovery in cotton for OGA’s Fibre, Agri-industrials and Ag Services segment. EBIT for this segment more than tripled to SGD 211 in FY21 as compared to SGD 59m in FY20. This was due to a stronger demand for cotton as well as improvements in capacity utilization of textile mills.
OIL losses widens in 2021
Olam International (“OIL”) provides interim stewardship to the operating groups until IPOs and demergers are completed. OIL is responsible for the divestment of non-core assets and businesses identified in the 2019-2024 Strategic Plan and redeploying the capital released.
Losses for OIL widened to a loss of SGD 206m in FY21 as the segment continues to invest in developing its Gestating Assets to maturity as well as incubating new ventures. Some of the ventures OIL is currently exploring include: a digital farmer services platform “Jiva”, a B2C sustainability lifestyles platform “Adva”, a B2B smart carbon management platform Terrascope, a carbon trading and sustainable landscapes investment platform. As these ventures are still in their early stages, losses are to be expected in this segment.
Demerger and proposed IPO of OFI Group Limited
Following the completion of the scheme of arrangement, OIL will be delisted from the SGX and be replaced with Olam Group Limited (“OG”). The scheme of arrangement was carried out so as to enable the demerger of OFI as Olam intends to spin-off OFI as a separate publicly listed entity with a primary listing on the London Stock Exchange. Figure 2 maps out the intended corporate structure after the completion of the proposed transactions where OFI Group Limited and OG will be two separate entities and independent from each other.
Figure 2: Intended corporate structure after the completion of the proposed transactions
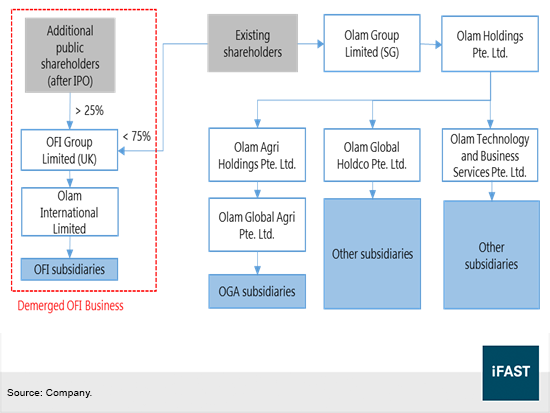
In conjunction with the Scheme of Arrangement, Olam announced a consent solicitation exercise (“CSE”) to substitute OIL with OG as the principal debtor and issuer, and release OIL from all obligations and liabilities under the notes. The securities that were affected by the CSE to substitute OIL with OG were: 1) OLAMSP 5.375% Perpetual Corp (SGD); 2) OLAMSP 5.500% Perpetual Corp (SGD); and 3) OLAMSP 4.375% 09Jan2023 Corp (USD). Noteholders for OLAMSP 5.375% Perpetual Corp (SGD) and OLAMSP 5.500% Perpetual Corp (SGD) passed the Extraordinary Resolution while noteholders for OLAMSP 4.375% 09Jan2023 Corp (USD) did not pass the Extraordinary Resolution. As such, OG will substitute OIL to be the issuer of the two perps.
We find the resolution passed at the CSE to be credit negative to the securities affected by the CSE as the new issuer, OG, will have a weaker credit profile as compared to OIL. Olam’s business segment OGA will be under OG which is slightly less profitable than OFI. As mentioned above, OGA in FY21 reported EBIT of SGD 753m as compared to OFI’s EBIT of SGD 875m.
Exposure to Russia and Ukraine is manageable
Russia and Ukraine are both important markets for the world agri-business markets. They both account for 19% of the world’s corn trade flow and 29% of the global wheat trade. Ports in Ukraine have been shut down by the government while the Russian government have shut down ports in the Azov Sea. This may disrupt some exports of grains from the two countries.
Regarding Olam’s exposure to Russia and Ukraine, Olam employs 127 employees in Ukraine and 1,938 employees in Russia. Olam’s own direct exposure to these markets is limited, with Russia and Ukraine combining for 1% of their total sales volume and 0.8% of their sales revenues. In Ukraine, Olam exports wheat, corn, edible oil and sunflower oil under OGA and imports cocoa and dairy products under OFI. In Russia, Olam has dairy farming operations and agri-farming operations under OFI.
Through Olam’s diversified sourcing, the company is better positioned to tap on different regions for their exporting needs. Countries such as India, Australia and Canada are markets in which Olam have a presence in and are able to provide Olam wheat in case of a supply shortage of wheat exports from Russia and Ukraine. India has become a net exporter of wheat after many years and will export substantial quantities of wheat, which didn't occur for many years in the past.
We think with a low exposure of 1% of total sales volume and 0.8% of revenue, Olam’s exposure to Russia and Ukraine is low and manageable. On top of that, Olam is able to substitute some of their contracts that are based on wheat from Ukraine or Russia with wheat from other wheat exporting countries with similar quality or values.
Liquidity and credit profile
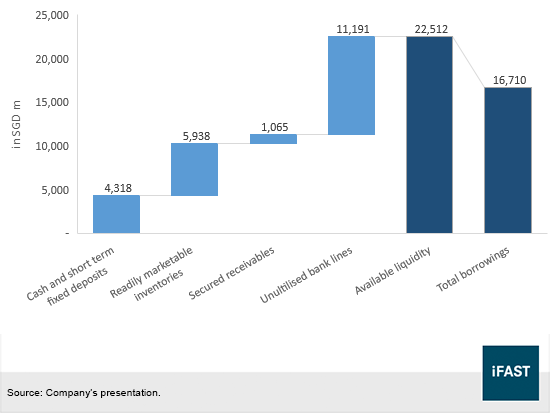
Although highly geared, Olam has sufficient liquidity to meet its borrowings of SGD 16.71b. For FY21, Olam had SGD 4.32b of cash and short term fixed deposits and SGD 11.19b of unutilised bank lines. As of 31 December 2021, Olam had a total of SGD 22.51b of liquidity available for the company to utilise and this includes SGD 5.94b of readily marketable inventories and SGD 1.07b of secured receivables along with the abovementioned cash and bank lines. This sufficiently covers its total borrowings of SGD 16.71b. With a net debt to equity of 1.72x, Olam remains highly leveraged, however, with the liquidity available to Olam, we think Olam is able to manage its debt. Debt servicing ability also remains adequate with an interest coverage ratio (taken as EBIT/ interest expense) of 2.68x.
Figure 3: Liquidity waterfall for Olam
As OGA will no longer be a subsidiary under OIL when the demerger is completed, OG might not have access to various debt facilities from OIL. As such, Olam is currently in discussions to allocate various debt facilities between the three operating groups. This allows OGA to tap on debt facilities to repay debt obligations or for working capital needs.
Recommendation
Prices of Olam’s bonds fell after the announcement of its CSE on 18 Jan 2022. Longer tenure bonds such as the OLAMSP 4.000% 24Feb2026 Corp (SGD) and OLAMSP 5.375% Perpetual Corp (SGD) are now trading below par. Among the notes, we think that the OLAMSP 5.375% Perpetual Corp (SGD) are trading at attractive levels with its yield to next call (“YTC”) of 6.14%. The 5.375% perps reset on its call date on 18 July 2026 at the prevailing 5-year SOR + 4.807% + step up margin of 200 bps. The step up margin reduces the probability of a non-call by the issuer.
Although the issuer for both the OLAMSP 5.5% perp and OLAMSP 5.375% perp will be substituted with OG as the issuer which has a weaker credit profile than OIL, we think that OGA will still have the financial capability to service debt and repay the notes on their call dates. OGA is expected to benefit from the rise in commodity prices and it continues to grow at a compounded annual growth rate of 9.1% since 2019. OGA also accounted for a majority of Olam’s total sales volume. On top of that, Olam is in discussions to allow OGA to tap on OIL’s debt facilities for its unutilised debt facilities which would provide sufficient liquidity for OG.
Table 1: Olam SGD bonds
|
Bond name |
Issuer |
Maturity / next call |
Years to maturity / next call |
Ask price |
Yield to maturity / next call (%) |
|
OLAMSP 5.500% Perpetual Corp (SGD) |
Olam International Ltd (to be substituted to Olam Group Limited) |
11 Jul 2022 |
0.31 |
100.40 |
4.19 |
|
OLAMSP 4.000% 24Feb2026 Corp (SGD) |
Olam International Ltd |
24 Feb 2026 |
3.94 |
98.44 |
4.43 |
|
OLAMSP 6.000% 25Oct2022 Corp (SGD) |
Olam International Ltd |
25 Oct 2022 |
0.61 |
101.83 |
2.87 |
|
OLAMSP 5.375% Perpetual Corp (SGD) |
Olam International Ltd (to be substituted to Olam Group Limited) |
18 July 2026 |
4.33 |
97.15 |
6.14 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 18 March 2022. |
|||||
Business-related risks
Olam has a small exposure to Russia and Ukraine and the crisis remains to be fluid and evolving. Olam’s business operations may be impacted by further sanctions that may include food. However, food has always been exempted during a sanction regime and is unlikely a food sanction will be imposed in Russia. On another note, currently only ports in Azov Sea have been shut down by Russia and further port closures may impact Olam’s businesses in Russia. With that said, Olam’s exposure to Russia and Ukraine is a small portion of their revenues and total sales volume and we think Olam is well positioned to manage any developments that may occur in Russia.
Conclusion
Olam reported strong earnings growth in FY21 and we expect growth to continue heading into 2022. We think with a low exposure of 1% of total sales volume and 0.8% of revenue, Olam’s exposure to Russia and Ukraine is low and manageable. The OLAMSP 5.375% Perpetual Corp (SGD) are trading at attractive levels with its yield to next call (“YTC”) of 6.14%. The new issuer OG although having slightly weaker credit metrics will still have the ability to tap on OIL’s banking lines and the financial capability to service debt and repay the notes on their call dates.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OLAMSP 5.375% Perpetual Corp (SGD) and OLAMSP 6.000% 25Oct2022 Corp (SGD) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!