- Oxley reported revenues decreasing by 13% year-on-year and as a result of lower revenues net profit for the period also saw a decrease of 18% year-on-year.
- Revenues for Oxley is expected to increase going into 2022 as a majority of their development projects in Singapore will reach their TOP dates in 2022.
- For 1H22, total cash and cash equivalents was SGD 199.7m, and is insufficient to cover its current borrowings of SGD 1,699m. Oxley’s ability to repay its debt obligations largely depend on the completion of its development projects.
- We prefer the OHLSP 6.500% 28Feb2023 Corp (SGD) over the OHLSP 6.900% 08Jul2024 Corp (SGD) due to its shorter maturity and it is currently trading at an indicative yield to maturity (“YTM”) of 6.92% for about 1 year in tenor.
On 10 February 2022, Oxley Holdings Limited (“Oxley”) reported earnings for the half year ended 31st December 2021. Earnings were rather lacklustre as revenues and profits fell during the second half of last year.
On top of that, Oxley also announced the resignation of their Chief Financial Officer about a week after the release of their earning results. With borrowings of SGD 1,699m set to expire within the next twelve months, will Oxley have the ability to repay its debt obligations? This article will breakdown Oxley’s 1H22 earning results and discuss Oxley’s ability to pay down its debt obligations.
1H22 financial highlights
Revenues for Oxley for the half year ended 31 December 2021 (“1H22”) was SGD 506.4m, a 13% decrease year-on-year (“YoY”). The decrease was due to lower revenues from The Royal Wharf project in the UK as the development have already reached its Temporary Occupation Permit (“TOP”) in 2021. Revenues came from development projects in Singapore and the sale of land parcels in Australia. As a result of lower revenues, profit for the period was SGD 23.4m which was a decrease of 18% YoY.
Revenues for Oxley is expected to increase going into 2022 as a majority of their development projects in Singapore will reach their TOP dates in 2022. From Table 1, all development projects except for Parkwood Residences are expected to be completed in 2022. For projects reaching TOP in 2022, they have a remaining gross development value (“GDV”) of SGD 200m and Oxley is expected to receive future progress billings of SGD 1,532m.
Table 1: Oxley’s development projects in Singapore
|
Project |
TOP |
Effective stake (%) |
% Sold |
Total GDV |
Remaining GDV |
Future progress billings (Eff. Stake) |
Remaining GDV (Eff. Stake) |
|
1953 |
3Q22 |
100 |
68% |
118m |
38m |
50m |
38m |
|
Affinity at Serangoon |
4Q22 |
40 |
99% |
1,305m |
11m |
338m |
4m |
|
INSPACE |
2Q22 |
49 |
100% |
147m |
- |
41m |
- |
|
Kent Ridge Hill Residences |
3Q22 |
100 |
92% |
815m |
63m |
475m |
63m |
|
Mayfair Gardens |
3Q22 |
100 |
91% |
326m |
28m |
191m |
28m |
|
Mayfair Modern |
3Q22 |
100 |
82% |
273m |
50m |
139m |
50m |
|
Parkwood Residences |
2Q23 |
100 |
33% |
30m |
20m |
9m |
20m |
|
Riverfront Residences |
3Q22 |
35 |
99% |
1,525m |
10m |
298m |
4m |
|
Total |
|
|
|
4,539m |
220m |
1,541m |
207m |
| Source: Company’s presentation. | |||||||
For Oxley’s overseas development projects, Royal Wharf and Dublin Landings, which are Oxley’s highest development project in terms of GDV (SGD 2,812m and SGD 1,162m respectively) have TOP-ed in 2021. Looking ahead, overseas development projects have a remaining GDV of SGD 1,513m and future progress billings of SGD 280m. For overseas projects, most of the cash flow will be received upon the completion of the property.
Looking beyond 2022, Oxley’s future projects in their pipeline have a potential GDV of SGD 2,454m. These projects include Connolly Station in Ireland, where a mixed development with residential units, office blocks and a hotel, will be built at the busiest railway station in Dublin and Ireland. The company has a 90% stake in the development and has an estimated GDV of ~SGD 1,400m.
Liquidity and credit profile
Oxley has a weak liquidity profile as the company is highly leveraged with debt. For 1H22, total cash and cash equivalents was SGD 199.7m, and is insufficient to cover its current borrowings of SGD 1,699m. Oxley’s gearing ratio was 2.01x as at 31 December 2021, a slight reduction from 2.18x at 30 June 2021.
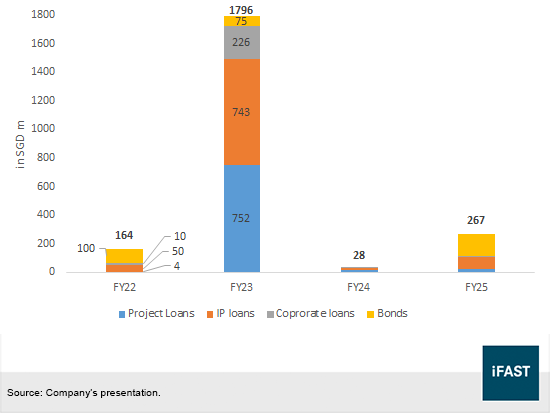
Oxley has SGD 164m of debt maturing in FY22 (Chart 1). SGD 100m of its OHLSP 5.700% 31Jan2022 Corp (SGD) have already been redeemed by the company and SGD 4m of project loans and SGD 10m of Corporate loans will be repaid by proceeds from its development projects. Oxley has also refinanced its IP loans of SGD 40m and will mature in 2027.
Taking a look at Oxley’s debt maturity profile, at first glance, Oxley’s debt maturity profile looks intimidating as a majority of its debt is set to mature in FY23. For Oxley to repay its debt in FY23, they would have to rely on cash flows from the completion of its development properties in Singapore. As mentioned above, Oxley is expecting to receive SGD 1,532m of revenue to be recognised in FY23, which can be used to pay off its debt expiring in FY23. Additionally, Oxley may look to sell some of its hotel properties free up some liquidity if needed. Some loans may be refinanced as well and we believe that Oxley will have continued access to diversified funding sources including banks and debt capital markets.
Therefore, Oxley’s ability to repay its debt obligations largely depend on the completion of its development projects. Any unexpected delay could impact the company’s cash flow and may affect their ability to repay debts when due. Construction activities on Oxley’s projects in Singapore and overseas have resumed operations though the progress is still hampered by varying degrees of manpower shortages, supply chain disruption and safe distancing measures. The company’s management is expecting to complete all the remaining Singapore development projects in the next 12 months.
Chart 1: Debt maturity profile
Recommendation
In view of its visible cash flows in the next 2 years, we continue to maintain our positive view on Oxley. We prefer the OHLSP 6.500% 28Feb2023 Corp (SGD) over the OHLSP 6.900% 08Jul2024 Corp (SGD) due to its shorter maturity and it is currently trading at an indicative yield to maturity (“YTM”) of 6.92% for about 1 year in tenor, which is just 5 basis points (“bps”) less than the YTM of the 2024 notes. Therefore, we do not think the 5 bps premium from the 2024 notes sufficiently compensates the investor for holding the bonds for an additional ~1.3 years. Investors who are interested in investing in short-term and high-yield SGD bonds may consider the OHLSP 6.500% 28Feb2023 Corp (SGD).
Table 2: OHLSP bonds
|
Bond name |
Issuer |
Maturity |
Years to maturity |
Ask price |
Yield to maturity (%) |
|
OHLSP 6.500% 28Feb2023 Corp (SGD) |
Oxley MTN Pte Ltd |
28 February 2023 |
0.99 |
99.60 |
6.92 |
|
OHLSP 6.900% 08Jul2024 Corp (SGD) |
Oxley MTN Pte Ltd |
8 July 2024 |
2.35 |
99.79 |
6.99 |
| Source: Bloomberg Finance L.P., iFAST compilations. Data as of 02 March 2022. | |||||
Business-related risks
On 16 December 2021, the Singapore government raised the additional buyer’s stamp duty for Singapore citizens, permanent residents and foreigners. The total debt servicing ratio (“TDSR”) threshold for obtaining loans was narrowed from 60% to 55%. This may affect future home sales due to the tightening of TDSR as it affects the buyers’ ability to get a loan to purchase additional property to rent or stay.
We think the impact of the property cooling measures for Oxley will be low. From Table 1, most of Oxley’s Singapore developments have already been fully sold or close to fully sold. Also, properties with higher GDV such as Affinity at Serangoon (GDV: 1,305m) and Riverfront Residences (GDV: 1,525m) are both 99% sold. Thus, we think that given most of Oxley’s property have been sold, the property cooling measures would not have a strong impact to Oxley’s revenues.
Conclusion
Although Oxley saw revenues decreasing in 1H22, the company is expected to generate future progress billings of SGD 1,532m for Singapore development projects in 2022. Barring any unforeseen delays in the completion of these projects, Oxley should have sufficient cash flows to repay its liabilities through proceeds from the development projects and also through debt refinancing. We prefer the OHLSP 6.500% 28Feb2023 Corp (SGD) over the OHLSP 6.900% 08Jul2024 Corp (SGD) due to its shorter maturity and it is currently trading at an indicative YTM of 6.92% for about 1 year in tenor.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OHLSP 6.900% 08Jul2024 Corp (SGD) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!