


Highlights:
- Road King’s contracted sales in 2021 was less influenced by the stagnant Chinese property market, with a 21% increase. The current lank bank is ample and situated in desirable locations, which could support its sales performance. Due to an improvement in average daily traffic volume, income from toll roads rallied by 38.5% in 2021, and is expected to grow at a stable rate.
- In terms of credit profile, the adjusted net gearing ratio increased to 89.2% as of 31 December 2021, while the ratio of cash to short-term debt to 1.6x. There is no significant deterioration on off-balance-sheet credit metrics, and overall credit risk is manageable.
- The pessimistic sentiment of the high-yield sector acts as a drag on the bond price recently. Given its good credit and fundamentals, investors can consider the 2023 USD bond, which is a new addition to Bond Express.
Previously, we have analysed Shui On land, which is a Hong Kong-funded Chinese property developer, based on its operation and credit profile. This week, we move on to another Hong Kong-asset-backed Chinese property developer – Road King Infrastructure Limited (“Road King” hereafter).
Company Background
Founded in 1994, Road King was listed on the Hong Kong Stock Exchange in 1996 (Stock Code 1098.HK). Its market capitalization reached HKD 5.1 billion as the market closed on 31 March 2022.
Property development is the core business of Road King. To date, the company has developed over 50 property projects across China. Besides, Road King’s another key business is toll road, it has five expressways in China and three expressways in Indonesia.
Looking into the ownership structure, as of 31 December 2021, Wai Kee Holdings Limited, a Hong Kong-based company, owned a 44.4% share of Road King. Road King’s management is mainly from Hong Kong, including chairman Zen Wei Pao. Road King hence could be considered a Hong Kong-funded company.
Contracted Sales Grows Rapidly with Ample Land Bank
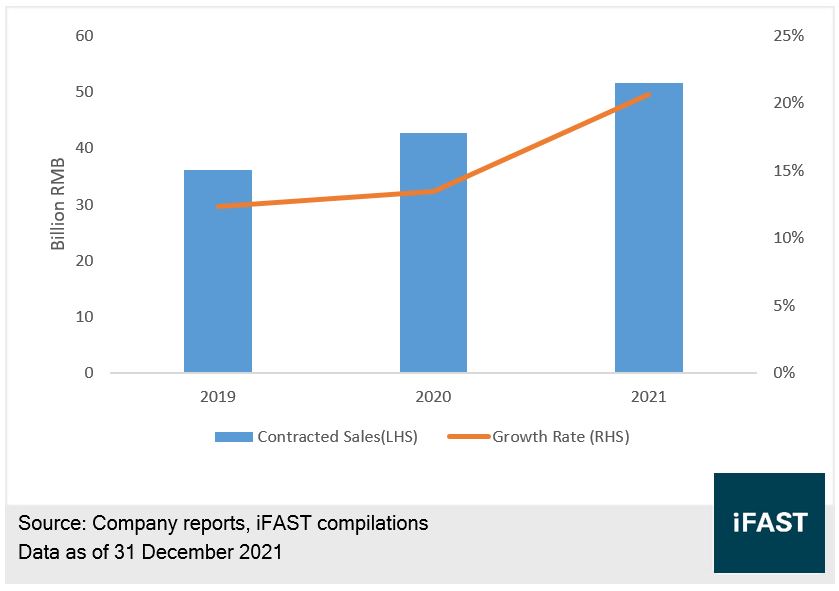
Even though most developers’ sale numbers recorded a double-digit plunge due to the stagnant Chinese property market in 2H2021, Road King seems to be less influenced. Its full-year contracted sales in 2021 jumped by approximately 20.7% to RMB 51.6 billion (Chart 1), the growth rate outstripped that in 2019 and 2020.
Chart 1: Road King’s Contracted Sales
We believe that Road King’s good sales performance should be attributed to its ample land bank in good locations. As of 31 December 2021, the total land bank owned by Road King amounted to 6.5 million square metres, equivalent to RMB 191.0 billion based on the average selling price of 29,000 per square metre in 2021. The land bank was 3.7 times bigger than the contracted sales in 2021, showing its ampleness.
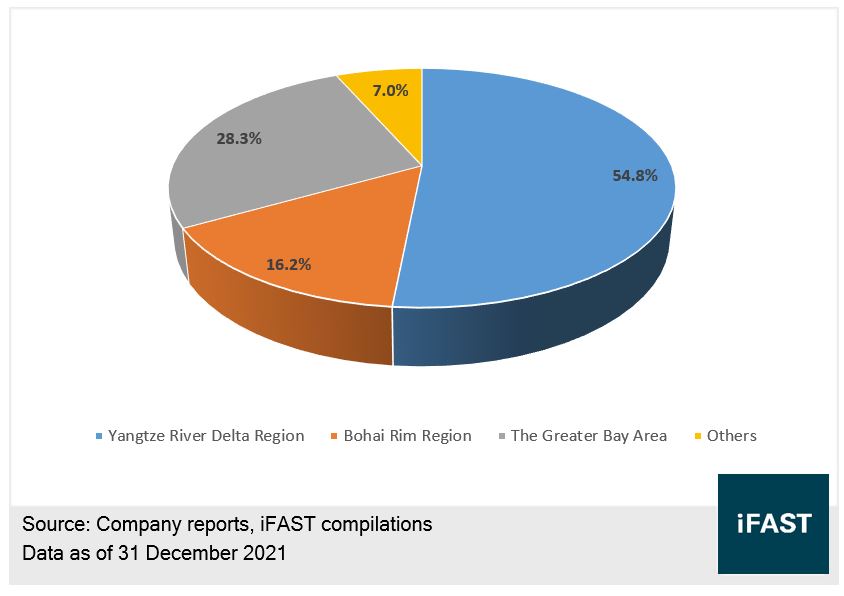
From the perspective of locations of the land bank (Chart 2), more than half of it was located in the Yangtze River Delta, a region with a relatively advanced economy. 23% of the land bank is located in Bohai Rim Region, such as Beijing and Tianjin. Overall, the current land bank could provide strong support for Road King’s development.
Chart 2: Land Bank of Road King
Toll Road has Bottomed Out, and is Expected to Grow Stably
Due to the pandemic outbreak, road tolls were suspended for a long time in 2020, resulting in a significant setback in Road King's toll road business. The related revenue was RMB 2.7 billion in 2020. However, the business has bottomed out in 2021, the revenue rallied about 38.5% to RMB 3.8 billion (see Table 1).
Table 1: Toll Road Sector
|
Location |
Income from Toll Road (Million RMB) |
|
|
Baojin Expressway |
Hebei Province, China |
890 |
|
Tangjin Expressway |
Hebei Province, China |
720 |
|
Changyi Expressway |
Hunan Province, China |
530 |
|
Longcheng Expressway |
Shanxi Province, China |
640 |
|
Machao Expressway |
Anhui Province, China |
370 |
|
SN Expressway |
East Java, Indonesia |
270 |
|
NKK Expressway |
East Java, Indonesia |
230 |
|
MKTT Expressway |
North Sumatra, Indonesia |
130 |
|
Total |
3,780 |
|
|
Sources:
Company reports, iFAST compilations |
||
Meanwhile, the average daily traffic volume improved by about 13% from 285,000 in 2020 to 322,000 in 2021. However, the great improvement was partly due to the low base in 2020. Data from the National Bureau of Statistics revealed that the highway freight traffic volume has been closed to saturation, as CAGR for the past five years stuck at 1.2%. Consequently, we expect the revenue from toll roads will slow down and maintain a single-digit growth in the future.
Credit Metrics are Slightly Weakening, but Beating Our Expectation and Meeting Regulatory Requirement
We observed that all credit metrics in 2021 weakened slightly. The net gearing ratio rose to 71.8%, and the adjusted net gearing ratio, which has taken perpetual bonds into account, stood at 89.2%, increased by 6 percentage points compared to the mid of 2021(see Table 2). However, given that many developers stepped into distress with halted refinancing channels in 2H2021, we consider that the deterioration of credit metrics of Road King is insignificant and beat our expectation.
In addition, the ratio of cash to short-term debt rose from 1.4x in the mid-2021 to 1.6 x in the end-2021, hinting an improvement in liquidity. The adjusted liability to asset ratio, which failed to meet the regulatory requirement previously, declined to 64.1% and reached the requirement in 2021. The indicators suggested that Road King has become a “Green Zone” developer.
Table 2: Credit Metrics of Road King
|
Mid-2021 |
End-2021 |
Requirement of Three Red Line |
|
|
Net Gearing Ratio |
61.7% |
71.8% |
<100% |
|
Adjusted Net Gearing Ratio |
82.5% |
89.2% |
/ |
|
Cash to Short-term Debt Ratio |
1.4 |
1.6 |
>1.0x |
|
Adjusted Liability to Asset Ratio |
66.7% |
64.1% |
<70% |
|
Source: Company
reports, iFAST compilations |
|||
Manageable Off-balance-sheet Debt
In terms of the off-balance-sheet credit metrics (see Table 3), as of 31 December 2021, the minority interest/total equity ratio was 18.2%, close to the previous year. The payable to associate/joint ventures over the total debt was around 18.0%. Both two indicators are relatively low, suggesting the associates/joint ventures are relatively small, and the reported debt amount can nearly match the real debt amount. The overall credit risk is manageable.
Table 3: Credit Metrics of Road King
|
Mid-2021 |
End-2021 |
|
|
Minority Interest/Total Equity |
15.6% |
18.2% |
|
Payable to Associate/joint Ventures over Total Debt |
14.8% |
18.1% |
|
External Guarantees (billion RMB) |
2.7 |
3.3 |
|
Source: Company
reports, iFAST compilations |
||
It is noteworthy that the number of external guarantees reported by Road King was insignificant, which was only around RMB 3.3 billion at the end of December 2021. Road King has fewer manipulations in financial statements compared to traditional Chinese property developers, which is a common characteristic of the Hong Kong-funded developers.
Perpetual Bonds Are Expected Not to Influence Liquidity
Road King has issued many perpetual bonds. So far, the company faces three outstanding perpetual bonds, with a total amount of USD 900 million (Table 4).
| Issue Date | Coupon Rate | Issue Size | First Call Date | |
| ROADKG 7.950% Perpetual Corp (USD) |
Feb-2017 | 7.95% | USD 300 Million | 17-Feb-22 |
| ROADKG 7.000% Perpetual Corp (USD) |
Jun-2017 | 7.00% | USD 300 Million | 23-Jun-22 |
| ROADKG 7.750% Perpetual Corp (USD) |
Dec-2019 | 7.75% | USD 300 Million | 18-Nov-24 |
| Source:
Company reports and Bloomberg, iFAST compilations Data as of 31 March 2022 |
||||
It is worth mentioning that the first call date for two perpetual bonds issued in 2017 will be on this year. As a result, there would be USD 600 million (about RMB 3.8 billion) cash outflow if the company chooses to redeem them this year, and Road King’s liquidity might be adversely influenced under the current market circumstance.
Generally speaking, perpetual bonds are embedded with the coupon set-up clause. It means that if the issuers do not redeem perpetual bonds at the designated call date, the coupon rate will be greatly revised upward.
Interestingly, such a clause is not included in the issuance covenant of Road King’s perpetual bonds, which means even though Road King does not redeem the bonds, the coupon rate will remain unchanged. In fact, Road King did not redeem the perpetual bond issued in Feb 2017 on 17 Feb this year, and we expect that the company will take the same action to perpetual bond that is first callable in June. As a result, it can avoid a USD 600 million cash outflow and weaken the liquidity.
Feb 2023 Bond Could Be Considered
Currently, there are six bonds issued by Road King on Bondsupermart. The credit rating is BB- by S&P, and the specification is listed below:
Table 5: Road King’s Bonds
|
Bond |
Years to Maturity |
Ask Price |
YTM |
|
0.8 |
92.2 |
18.3% |
|
|
2.5 |
84.5 |
14.3% |
|
|
2.9 |
80.1 |
14.5% |
|
|
3.4 |
81.1 |
13.0% |
|
|
3.8 |
77.6 |
12.8% |
|
|
4.3 |
77.5 |
12.0% |
|
|
Sources: Bondsupermart, data as of 31 Mar 2022 |
|||
The vast majority of bonds traded roughly at $90 before March this year, whereas plunged by over 30% owing to a selloff of Chinese property bonds, especially those issued by Country Garden, CIFI and other developers with good credit profiles. Nevertheless, we believe that the selloff principally resulted from the poor market sentiment, rather than the regulation policies, issues in credit profile or fundamental outlook. Investors still can consider Road King’s bonds.
On account of unpromising future of Chinese property market, investor could give priority to short-term bond, like ROADKG 7.875% 01Feb2023 Corp (USD), which is a new addition to Bond Express with ask price of 92.2 and YTM of 18.3%.
Corporate Risk
Investors should be aware of the following risk. Firstly, the pandemic surges again, causing the lockdown of some cities in China. Both the property development sector and toll road sector will be adversely affected, which will weaken the cash inflow and solvency as a result.
Moreover, floating-rate debt constitutes over 40% of total debt, and most of the floating-rate debt is denominated in non-CNY. The debt amount of Road King will likely be revised upward along with the interest rate hike cycle (excluding China), therefore the company will suffer from a higher debt repayment stress.
Lastly, the recent wave of default in Chinese real estate sector caused a massive loss of confidence in the market, with some high-grade bonds also being affected. If Road King’s bonds encounter another round of selloff, its refinancing ability will be severely damaged.
Conclusion
Road King’s contracted sales in 2021 was less influenced by the stagnant Chinese property market, with a 21% increase. The current lank bank is ample and situated in desirable locations, which could support its sales performance. Due to an improvement in average daily traffic volume, income from toll roads rallied by 38.5% in 2021, and is expected to grow at a stable rate.
In terms of credit profile, the adjusted net gearing ratio increased to 89.2% as of 31 December 2021, while the ratio of cash to short-term debt to 1.6x. There is no significant deterioration on off-balance-sheet credit metrics, and overall credit risk is manageable.
The pessimistic sentiment of the high-yield sector acts as a drag on the bond price recently. Given its good credit and fundamentals, investors with high-risk tolerance can consider the ROADKG 7.875% 01Feb2023 Corp (USD) 2023 USD bond , which is a new addition to Bond Express.









