


Highlights:
- Sun Hung Kai & Co. is just one step away from becoming a leading alternative investment company. The company has fair performances in financing an investment segments. The investment loss for the year should only have a temporary effect on the company.
- The company has substantial financial assets, which could be the potential liquidity source. The leverage level is good. The company’s credit position is strong.
- Investors could pay attention to the bonds due in 2024 or 2026, with a YTM of 7.0% and 8.0% respectively, which have higher attractiveness.
We have introduced Sun Hung Kai & Co.’s business and credit profile in “A New Business Driver Is Coming Soon for Sun Hung Kai & Co.” After almost a year, it is time to update on its latest development.
A Soon-to-be a Leading Alternative Investment Company with Fair Performance in Financing and Investment Segments
Sun Hung Kai & Co. has been proactively developing its fund management business since 2021. The fund management platform, “Sun Hung Kai Capital”, has launched six fund projects where two of them are self-managed and the rest are co-managed by partners. Strategies of these funds include real estate, hedge fund, long short equity, venture capitals, quantitative trading and cryptocurrency, in order to attract different types of institutional investors. The company also deployed capital into these funds, to ensure the funds have at least certain level of assets under management. The company is attempting to achieve its core goal—to become the leading alternative investment company.
As shown in Chart 1, Sun Hung Kai & Co.’s profits mainly come from two segments: financing business and investment management business. In the first half of 2022, the company’s segment profit from financing business dropped 21.9% YoY to HKD 0.72 billion, showing a fair performance. It is mainly due to economy slowdown in Hong Kong and Mainland China, a decrease in the SMEs’ demand for loans and a slight decrease in the return on loans. But the Company's total loan balance remains stable, which will allow the company to regain growth in the future.
Chart 1: Sun Hung Kai & Co.’s Segment Profits
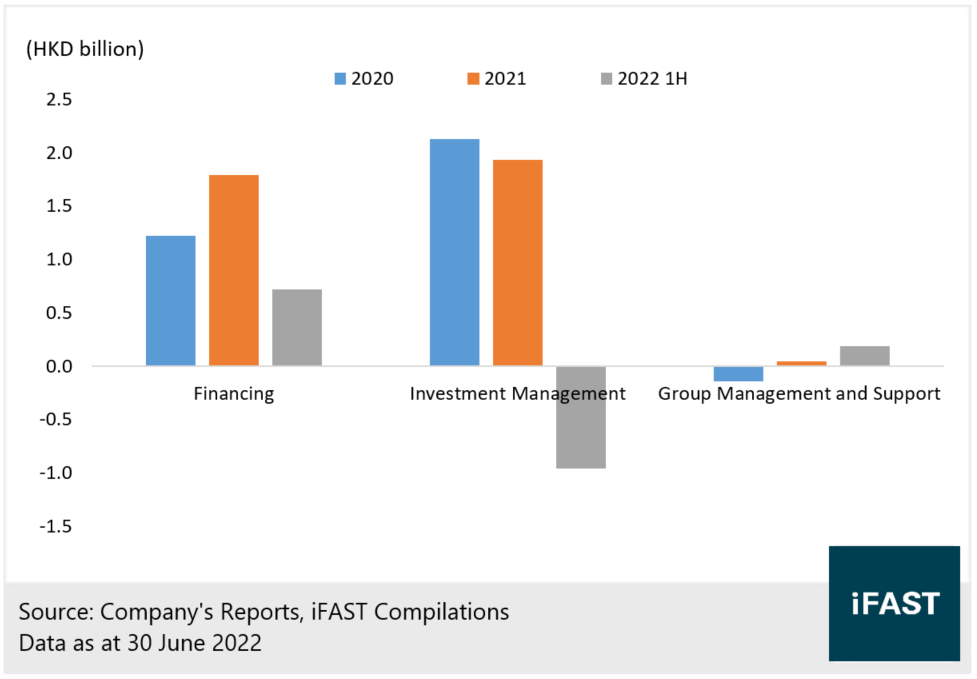
Table 1: Sun Hung Kai & Co.’s Main Operating Indicators
|
2020 |
2021 |
2022 1H |
|
|
Total Revenues (HKD billion) |
4.06 |
4.32 |
2.07 |
|
EBITDA (HKD billion) |
3.97 |
4.55 |
0.37 |
|
Total Loan Balance (HKD billion) |
16.6 |
17.7 |
16.9 |
|
Total Return on Loans (Financing Business) (%) |
26.9% |
26.9% |
26.1% |
|
Investment Portfolio Value at the end period (HKD billion) |
16.7 |
21.1 |
20.3 |
|
Return on Investment (Investment Management Business) (%) |
16.9% |
14.4% |
-2.5% |
|
Return on Equity |
11.8% |
11.8% |
N/A |
|
Sources: Company’s Reports, iFAST Compilations Data as at 30 June 2022 |
|||
The Investment Loss for the Year should only have a Temporary Effect
On the other hand, in the first half of 2022, the investment management segment turned the profit to loss, where it recorded a loss of HKD 0.96 billion, mainly due to the mark-to-market loss of financial instruments. The poor performance of the global market year-to-date along with double-digit declines in most mature markets would undoubtedly drag down the company’s short-term performance.
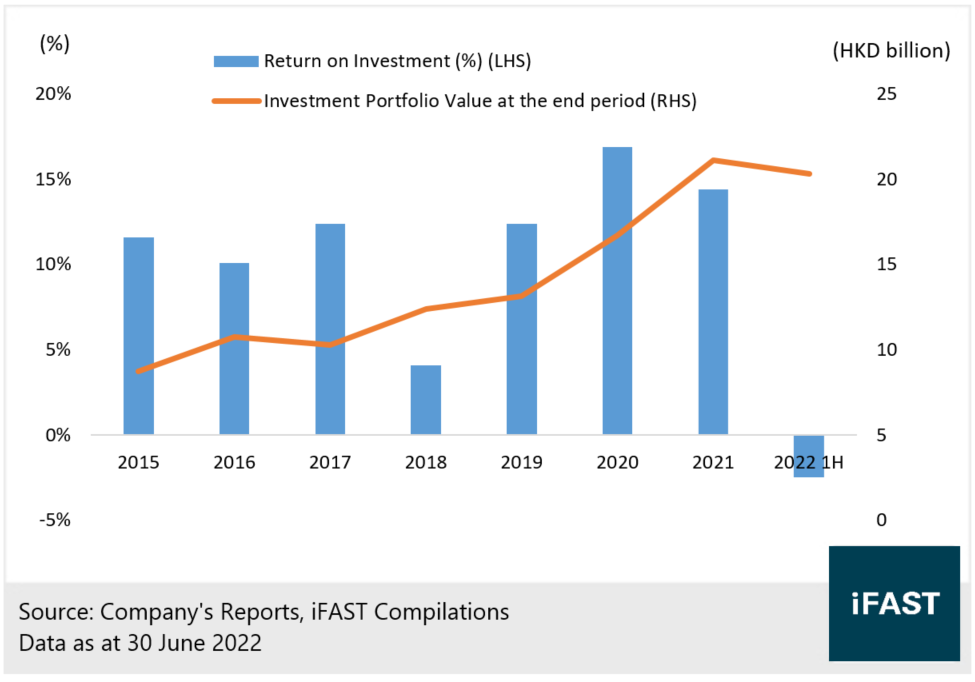
We believe that these investment losses should only have a temporary impact on the company. As shown in Figure 2, the company's investment returns all recorded 10% or above since 2015, with the exception of 2018 and the first half year of 2022, which is an impressive investment performance. Therefore, in the long run, the investment management business should continue to bring the company good profit.
Chart 2: Sun Hung Kai Co.’s Past Returns on Investment and Investment Portfolio Value
Substantial Financial Assets could be the Potential Liquidity Source; Company’s Credit Position is Strong
As of the end of June 2022, Sun Hung Kai & Co. had total debt of HKD 20.4 billion and a net gearing ratio of 45.2%, up from 44.6% at the end of 2021 (see Table 2). However, the company had financial assets of up to HKD 17.4 billion. These substantial financial assets could be a potential liquidity source for the company. If we classify these financial assets as cash and cash equivalents, the company can be considered to be in a net cash position. The company’s leverage level is good.
Taking reference of the data in 2021, the company’s interest coverage ratio was up to 6.4 times, indicating that the interest expense was not a significant pressure on the company. Its average cost of borrowing fell to 4.0%, reflecting the company's improved financing ability. All in all, the company's credit position is quite decent.
Table 2: Sun Hung Kai & Co.’s Credit Indicators
|
Dec 2021 |
Dec 2021 |
Jun 2022 |
|
|
Total Assets (HKD billion) |
44.1 |
48.8 |
49.0 |
|
Total Cash (HKD billion) |
7.3 |
6.0 |
8.2 |
|
Financial Assets (HKD billion) (Mainly equities, bonds, funds and derivatives) |
13.7 |
18.7 |
17.4 |
|
Total Debts (HKD billion) |
16.8 |
18.7 |
20.4 |
|
Net Gearing Ratio (%) |
36.7% |
44.6% |
45.2% |
|
Interest Coverage Ratio (times) |
5.0 times |
6.4 times |
N/A |
|
Average Cost of Borrowing (%) |
4.7% |
4.0% |
N/A |
|
Sources: Company’s Reports, iFAST Compilations Data as at 31 December 2021 |
|||
Investors Could Pay Attention to the bonds due in 2024 or 2026, with a YTM of 7.0% and 8.0% respectively
Neither SHK nor its bonds are rated, but this does not mean that the credit quality is poor. Currently, there are three Sun Hung Kai USD bonds available on the FSMOne platform (see Table 3).
Based on the strong credit position and the availability of financial assets for liquidation, we believe the risk of default on its medium and short maturity bonds is low.
As the September 2022 bond will mature soon, its investment value is less significant. Investors could pay attention to USD bonds due in 2024 or 2026, with attractive YTM of 7.0% and 8.0% respectively.
Table 3: Sun Hung Kai & Co.’s Bonds
|
Bond Name |
Years to Maturity |
Ask Price (Investor Buys) |
YTM |
|
0.1 |
99.2 |
/ |
|
|
2.2 |
97.5 |
7.0% |
|
|
4.1 |
89.8 |
8.0% |
|
|
Source: Bondsupermart Data as at 19 August 2022 |
|||
Related Risks
Sun Hung Kai & Co. relies heavily on the returns of its investment portfolio for earnings. If the global economy enters a severe recession, this could be detrimental to the performance of the Company's investment portfolio.
Although the interest rate hike cycle is generally beneficial to the company’s financing business, it also puts pressure on the Hong Kong economy, and the non-performing loan rates might increase.
Conclusion
Sun Hung Kai & Co. is just one step away from becoming a leading alternative investment company. The company has fair performances in financing an investment segments. The investment loss for the year should only have a temporary effect on the company.
The company has substantial financial assets, which could be the potential liquidity source. The leverage level is good. The company’s credit position is strong.
Investors could pay attention to the bonds due in 2024 or 2026, with a YTM of 7.0% and 8.0% respectively, which have higher attractiveness.
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.


