- In 2021, ZhongAn managed to achieve underwriting profitability for the first time since its incorporation.
- ZhongAn is not only an insurtech disruptor in the insurance space but also has aspects of a technology company.
- The ZHONAN 3.125% 16Jul2025 Corp (USD) and ZHONAN 3.500% 08Mar2026 Corp (USD) have a yield to maturity (“YTM”) of 6.07% and 6.20% respectively.
- We think the ZhongAn bonds are attractive given its credit drivers and solvency profile.
Zhong An Online P&C Insurance Co Ltd (“ZhongAn”) is an online-only insurance company in China. ZhongAn was founded on 6 November 2013 and listed on the Main Board of the Hong Kong Stock Exchange (HKEX: 6060) on 28 September 2017. The insurtech company was co-founded by China’s most prominent businessmen – Jack Ma (Alibaba), Pony Ma (Tencent) and Mingzhe Ma (Ping An).
ZhongAn’s 5 ecosystems
The company operates in 5 insurance ecosystems – 1) Health; 2) Digital Lifestyle; 3) Consumer finance; 4) Auto; and 5) Travel. For its health ecosystem, ZhongAn offers health insurance protection by offering dedicated group insurance products and solutions. In 2021, the health ecosystem provided health insurance and medical services to ~25.86 million insured customers and recorded approximately RMB 7,686 million in total gross written premium (“GWP”), representing a year-on-year (“yoy”) increase of approximately 16.4%.
In its Digital Lifestyle ecosystem, ZhongAn offers innovative products to serve customers’ diversified needs in digital life. Examples include insurance products for users on e-commerce platform such as Tmall, Taobao Marketplace, Xiaohongshu, Douyin and Kuaishou. ZhongAn offers a wide variety of innovative insurance products ranging from shipping return insurance to even phone screen crack insurance (65% GWP yoy growth) and pet insurance (250% GWP yoy growth).
ZhongAn’s consumer finance ecosystem provides credit insurance products to consumers and small businesses. In 2021, the GWP for its consumer finance ecosystem was RMB 4,447m, representing a 105.7% increase. Outstanding loan balance increased by 21.0% to RMB 19.4b.
Lastly, its auto ecosystem products are offered through Baobiao Auto Insurance which is a coinsurance model developed together with Ping An P&C. This means that the premiums, claim payments and other costs for auto insurance are split between ZhongAn and Ping An P&C at 50:50 ratio. Its travel ecosystem includes travel risk insurance for unexpected emergencies such as flight accident, flight delay, travel accident, flight or hotel cancellation.
On top of insurance, ZhongAn is also involved in technology and banking solutions. ZA Tech, its technology subsidiary, provides technology solutions to insurance companies and internet platforms. Graphene is ZA Tech’s insurance core system that allows customers to connect with various ecosystem partners locally and launch a variety of fragmented and scenario-based protection products. Fusion is provided for internet platform customers and offers insurance and financial solutions.
In 2021, ZA Tech became a regional technology partner of AIA Group, the largest independent listed life insurance group in the Pan-Asian region, in order to speed up their digitalisation efforts. The Graphene system from ZA Tech will allow AIA to more rapidly develop and distribute insurance products and allow AIA to issue policies in real time to each customer group based on different living scenarios. Other customers of ZA Tech include NTUC Income, Sompo Insurance, Tokio Marine Insurance Group, Grab and China Mobile. As of 31 December 2021, ZhongAn’s technology arm has served more than 600 customers and recurring income contributed to ~50% of its revenue.
ZA Bank was established in 2019 and in just 2 years, ZA Bank customers grew to more than 500,000, becoming the largest virtual bank in Hong Kong in terms of customers. Balance of deposits reached HKD 7b while loans grew to approximately HKD 2.5b. Being the only fintech company in Hong Kong with a virtual banking license and a digital-only insurer license, allows ZhongAn to leverage on the synergies of both businesses and create the first fully digital bancassurance through its ZA Bank app.
FY21 financial highlights
For its full year financial results ending 31 December 2021 (“FY21”), total gross premiums written in FY21 totaled to RMB 20.48b, representing a 22.6% increase from the year prior. Net profit attributable to owners of the parent for FY21 was RMB 1.17b, presenting a yoy increase of 110.3%. ZhongAn turned profitable in FY20 and continues to maintain and grow its profitability through its underwriting business.
In its technology segment, segment income was RMB 539.8m (yoy growth: 25.9%) while net loss for the segment was RMB 384.6m. Banking segment on the other hand also suffered net losses of RMB 463.5m. As ZhongAn’s technology and banking segments are in their growth stage, we expect both segments to be loss making in the next few quarters.
Underwriting turned profitable for the 1st time
In 2021, ZhongAn managed to achieve underwriting profitability for the first time since its incorporation. Underwriting profit was RMB 75.1m and ZhongAn had a combined ratio of 99.6% in FY21. The improvement in its underwriting business was due to an improved pricing model and prudent risk control especially in the consumer finance insurance ecosystem. Operating expenses from channel fees were reduced through cost reduction and efficiency improvements. Higher premiums from ZhongAn’s proprietary channels helped to drive down channel costs in its health ecosystem.
Figure 1: Performance of ZhongAn’s underwriting business
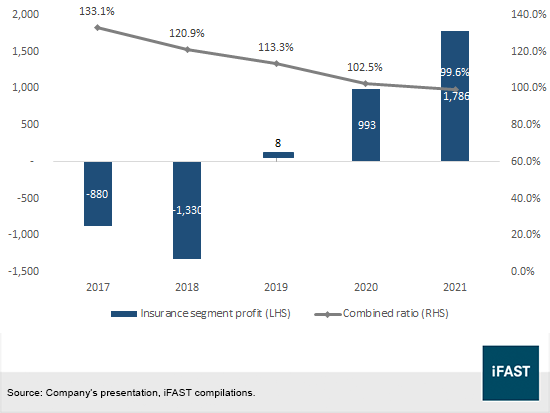
We expect ZhongAn to maintain underwriting profitability as the company continues to grow its proprietary channels and continue to reduce cost through more efficient pricing models. Premiums from proprietary channels was RMB 3.61b in FY21, a yoy increase of 66.4% and contributed about 18% of total GWP. Cross-selling of ZhongAn is expected to continue growing as the company focuses on serving the entire life cycle of its users. Cross-selling rate of its proprietary channels reached ~33% as ZhongAn expanded its products and services through their proprietary channels. As more and more users of ZhongAn’s insurance ecosystem, this improves economies of scale and improve profitability.
More than just an online insurance company
ZhongAn disrupts the traditional insurance space by offering products online without the need of agents. On top of that, ZhongAn is not only an insurtech disruptor in the insurance space but also has aspects of a technology company. ZhongAn offers its technology solutions to not just insurance companies but digital solutions to other online companies such as Klook. In November 2021, ZhongAn partnered with Klook, a travel booking platform, to create an ecosystem to onboard travel insurance products on their platform. Klook will be able to use ZA Tech’s proprietary solution, Fusion, to gain customer insights in order to increase insurance penetration.
ZA Tech also exports its technology to other insurance companies to help digitalise the insurance space. Customers are able to leverage on ZA Tech’s solutions to efficiently market and gain analysis on its users and products. Operations can be fully digitalised through ZA Tech’s business production series as they provide solutions to online policy issuance, claim settlements and other functions.
Instead of keeping its proprietary platforms and solutions to itself, ZhongAn exports the technology out to other insurance players. This is a good move by ZhongAn as other insurance players look to digitalise their product offerings as another means of distribution, ZhongAn is able to leverage on this demand and gain recurring income for its services. In FY21, net loss margin for this segment narrowed and recurring income makes up 50% of this segment’s revenue. We likened this aspect of its business to other technology companies offering software-as-a-service (“SaaS”) solutions. As this segment continues to grow, we expect ZhongAn to benefit from the economies of scale and expect high margins to come in from this segment in the future.
Figure 2: Technology export revenue

Source: Company's presentation
Credit and solvency profile
ZhongAn remains well-capitalised in FY21. Its core capital and actual capital were RMB 16.78b in FY21, resulting in both core solvency margin ratio and comprehensive solvency margin ratio to be 472%. We expect both of its core solvency margin and comprehensive solvency margin ratio to fall due to the implementation of the China Risk Oriented Solvency System (“C-ROSS”) Phase 2. The C-ROSS phase 2 seeks to improve the quality of capital of Chinese insurers and to accurately measure and reflect risks.
Chinese Insurers are required to adhere to these changes starting from 1Q22 onwards. It is expected that most Chinese insurers’ solvency ratios to fall following the implementation of these changes, including ZhongAn. However, we still expect ZhongAn’s solvency ratios to be above regulatory requirements and above its peers, following the implementation of C-ROSS phase 2.
ZhongAn issued 2 USD notes in 2020 – 1) ZHONAN 3.125% 16Jul2025 Corp (USD) and 2) ZHONAN 3.500% 08Mar2026 Corp (USD). Both bonds are rated Baa2 (Stable) by Moodys’ and is considered investment grade quality by Moodys’.
Recommendation
Yields of USD corporate bonds have risen due to interest rate hikes by the US Federal Reserve. The ZHONAN 3.125% 16Jul2025 Corp (USD) and ZHONAN 3.500% 08Mar2026 Corp (USD) have a yield to maturity (“YTM”) of 6.07% and 6.20% respectively. We prefer the ZHONAN 3.125% 16Jul2025 Corp (USD) over the ZHONAN 3.500% 08Mar2026 Corp (USD) due to the shorter duration of the 2025 notes.
We think the ZhongAn bonds are attractive given its credit drivers and solvency profile. ZhongAn has a diversified business profile, engaging in not only insurance but technology and banking segments. We expect its technology and banking segments to turn profitable within the coming years. We expect ZhongAn to continue to show strong operating performance, maintaining its underwriting profitability while lowering its net loss margin from its technology segment through economies of scale. Given the credit drivers and strong solvency profile, at its current YTM of 6.07%, we think it is an attractive level for investors to consider.
Table 1: Recommendations
|
Bond name |
Issuer |
Maturity |
Years to maturity |
Ask price |
Yield to maturity (%) |
| ZHONAN 3.125% 16Jul2025 Corp (USD) | ZhongAn Online P&C Insurance Company Limited |
16 Jul 2025 |
3.06 |
91.90 |
6.07 |
| ZHONAN 3.500% 08Mar2026 Corp (USD) | ZhongAn Online P&C Insurance Co., Ltd. |
08 Mar 2026 |
3.71 |
91.20 |
6.20 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 23 June 2022. |
|||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!