- Heeton reported revenues of SGD 17.53m for their first half financial results ended 30 June 2021 (“1H21”).
- The share of results from associated companies and joint venture companies increased by 158.4% to SGD 5.77m due to higher profits recognised for development projects as a result of the resumption in construction work in Singapore.
- Heeton has cash and cash equivalents (including fixed deposits) of SGD 88.06m in 1H21, up from SGD 58.57m in 1H20.
- After redemption of its 2021 notes, Heeton should be able to manage its cash flows going forward. Our estimated current ratio for the company after refinancing of its 2021 notes is approximately ~1.91x.
Following the exchange offer exercise on 14 October 2020, Heeton Holdings Limited (“Heeton”) completed the redemption of the outstanding SGD 117.75m of HTONSP 6.080% 19July2021 Corp (SGD).
Looking forward to its remaining outstanding notes due 2023, we continue to hold a positive credit outlook on Heeton. As the construction and hospitality sectors continue to pick up, the recovery will be beneficial to Heeton especially in the hospitality sector. We will highlight Heeton’s first half financial results and the recommendations for Heeton’s notes in this article.
1H21 Financial Results
Heeton reported revenues of SGD 17.53m for their first half financial results ended 30 June 2021 (“1H21”). Property development and hospitality saw a huge decline in 2020 due to the impact of Covid-19. In 2021, the sector has slightly rebounded, although not to pre-pandemic levels. Nevertheless, it is still a healthy sign to see recovery in these industries.
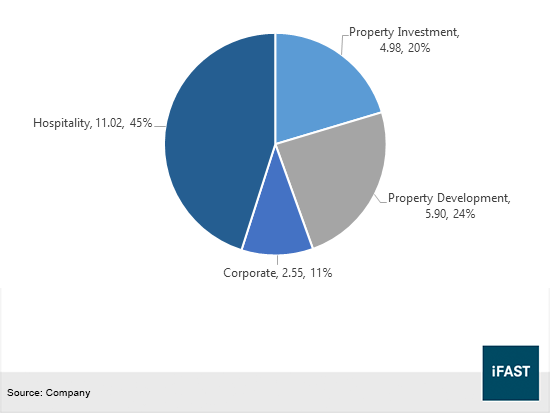
For Heeton, the property development segment saw revenues of SGD 5.90m while the hospitality segment saw revenues of SGD 11.02m. Bottom line profits for the company also improved: In 1H20, the company saw a net loss before tax of SGD 8.93m and in 1H21, bottom line profits increased to a net profit before tax of SGD 0.51m.
For property developers, it is imperative that the company does not halt any construction work as it relies on the completion of the development projects for its cash flows. 2020 saw the halt of construction due to Covid-19 related lockdowns imposed in Singapore. In 1H21, the share of results from associated companies and joint venture companies increased by 158.4% to SGD 5.77m. This was due to an increase in rental profits and also higher profits recognised for development projects as a result of the resumption in construction work in Singapore.
Heeton is currently developing three residential development projects in Singapore that are expected to complete by 3Q 2022. As of 1Q21, sales in Park Colonial rose to 99.25%, Affinity@Serangoon to 87.32% and Rezi24 to 99.20%. Completion of these projects will provide positive cash flows for the company.
As seen from Figure 1, hospitality segment for Heaton comprised of 45% of its total revenue. Heeton has 15 hospitality properties providing SGD 11.02m in revenue in 1H21. Most of Heeton’s hospitality properties are located in the United Kingdom.
On 24 June 2021, Heeton announced the opening of DoubleTree by Hilton London Kensington under a franchise agreement with Hilton. The property was formerly known as the Crowne Plaza London Kensington and was acquired in 2019 by a consortium led by Heeton together with KSH Holdings Limited and Ho Lee Group Pte Ltd.
Heeton has further 2 more hotels currently under development. The company has a 70% stake in a hotel and residential property in New York Road, Leeds with an approximate gross floor area of 77,749 sqm. Among its investment properties, Heeton has a 75% stake in a hotel property in Manchester, United Kingdom and 74% stake in a hotel in Bhutan.
Prior to the pandemic, Heeton made SGD 39.98m of revenue from the hospitality segment in FY2019. Although its current hospitality revenue is still far off from pre-pandemic levels, following the normalisation of economic activity and travel especially in the UK, we expect Heeton’s hospitality numbers to improve.
Figure 1: Heeton’s 1H21 revenue by business segment (in SGD m)
Liquidity and credit profile
Heeton has cash and cash equivalents (including fixed deposits) of SGD 88.06m in 1H21, up from SGD 58.57m in 1H20. The increase in cash and cash equivalents was mainly due to cash inflows from the net proceeds from a SGD 34.78m bank loan.
Heeton redeemed HTONSP 6.080% 19July2021 Corp (SGD) on the date of maturity and has only one outstanding bond issuance being HTONSP 6.800% 13Nov2023 Corp (SGD). After excluding the redemption of its SGD 60.75m 2021 notes, total borrowings for the company was SGD 449.47m in 1H21, consisting of bank term loans of SGD 379.17m and SGD 70.3m of bonds due November 2023.
Comparing the ratios with other high-yielding property developers in Singapore in Table 1, Heeton is more highly leveraged as compared to its peers. Adjusted EBIT to interest expense was 0.95x, however, after repayment of its 2021 notes, finance expense will be reduced.
Furthermore, Heeton had SGD 395.29m of fixed assets in 1H21, most of which are made up of hotel properties. These fixed assets also account for 37% of the company’s total assets. According to our estimates, the current ratio for the company after repayment of its 2021 notes was approximately 1.91x.
After repayment of its 2021 notes, Heeton should have sufficient liquidity going forward to manage its debt. The company may dispose some of its assets to free up liquidity and refinance some of its bank loans.
Table 1: Estimated credit ratios of SGD high yield property bond issuers
|
As of 1H21 |
Net debt/equity (x) |
Adjusted
EBIT/ |
|
Heeton Holdings Ltd |
1.03 |
0.95 |
|
Oxley Holdings Limited |
2.31 |
1.38 |
|
Koh Brothers Group Ltd |
0.70 |
0.37 |
|
Tuan Sing Holdings Ltd |
0.79 |
1.42 |
| Source: Respective companies’ financial statements, iFAST estimates | ||
Relative Valuation
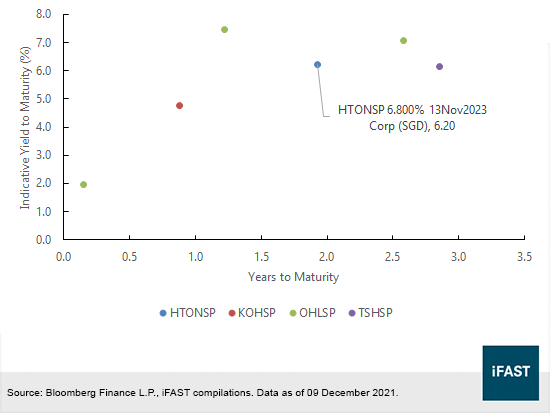
We remain positive on our views on Heeton and its ability to pay its short term debt obligations. Taking a look at the relative valuation of its notes among other high yield property developers in Singapore, HTONSP 6.800% 13Nov2023 Corp (SGD) has a yield to maturity (“YTM”) of 6.20% with slightly less than 2 years to maturity.
The HTONSP 6.800% 13Nov2023 Corp (SGD) has a condition that Heeton will redeem the notes in 3 payments: 10% of the outstanding principal amount will be redeemed on 13 November 2022, 10% of the outstanding principal amount on 13 May 2023 and the remaining outstanding principal amount on 13 November 2023. This will provide Heeton with more flexibility in managing cashflow and leeway in redeeming its outstanding notes.
Figure 2: Relative valuation among high yield SGD bonds
After redemption of its 2021 notes, Heeton should be able to manage its cash flows going forward. With an estimated current ratio for the company after repayment of its 2021 notes being approximately 1.91x, the company may dispose some of its assets to free up liquidity if needed.
All in all, we think Heeton’s business segments will continue to pick up and rebound from the impact of Covid-19. Construction and hospitality will pick back up and this will contribute positive cash flow to Heeton to manage its debt going forward.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OHLSP 6.900% 08Jul2024 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!