


Highlights:
Jubilant Pharma is an India-based, North America-focused integrated pharmaceutical company. Although its profit margin has declined recently, the specialty pharmaceutical business could serve as a good protection.
The company has ample short-term liquidity, with gradual improvements in leverage over the years. Despite the weakened profitability, the overall risks are still manageable.
The yield of the USD bond due in March 2024 is around 5.8%, which is more attractive compared to the peers’ and investors can consider about it. This bond will be on Bond Express soon.
The COVID-19 gave rise to pharmaceutical
stocks. The companies such as Pfizer, Eli Lilly and Fosun Pharma enjoyed a surge of fame and
became the favorites of many investors.
Apart from the industry giants in the US and China, there are still many pharmaceutical companies in other markets. Next, we will take a look into the bond issued by Jubilant Pharma Limited (“Jubilant Pharma”), a wholly-owned subsidiary of the Indian company Jubilant Pharmova. We believe it should be attractive to investors who like the medical sector.
An Integrated Pharmaceutical Company Based in India and Focused in North America
Jubilant Pharma was established in 2005, with company registration in Singapore. Its parent Jubilant Pharmova is headquartered in Noida of India, and is listed on National Stock Exchange of India (NSE: JUBLPHARMA). The current market capitalization is around USD 920 million.
As an integrated pharmaceutical company, the business of Jubilant Pharma covers over 85 countries, with a team of over 450 R&D professionals, and a total of six manufacturing facilities in India and North America. Although the company is based in India, its key focus is essentially the North America market, which has contributed to over 80% of total revenue for many years.
Jubilant Pharma manufactured a wide range of products, including Radiopharma products, contract manufacturing of sterile injectable, active pharmaceutical ingredients, allergy therapy products and other generic dosage forms.
Jubilant Pharma has a leading position in several major products. According to the official website, the company is the third-largest radiopharmaceutical manufacturer in the US nuclear medicine industry based on revenue. It is also one of the top three players in the allergenic extract market in the US. However, although the company has certain market shares in specific specialty products, its competitiveness in the global generic medicine market (e.g. respiratory medicines and pain relievers) should be limited because of its relatively small size.
Profit Margin Has Declined; but Specialty Pharmaceutical Business Could Serve as a Good Protection
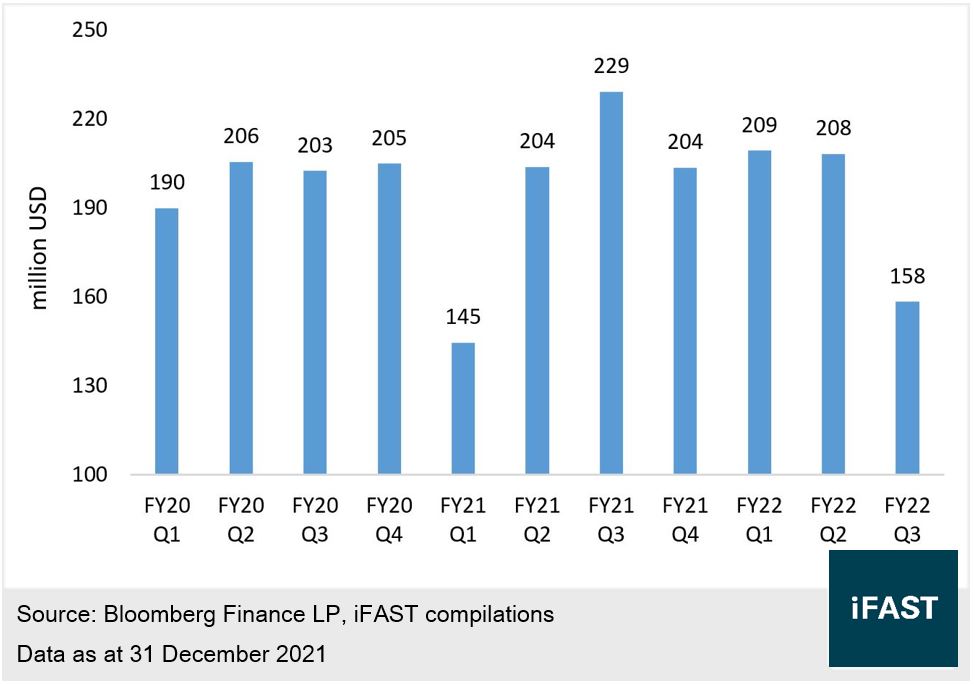
In the first nine months of Financial Year 2022 (“FY22”, March to December), Jubilant Pharma recorded a USD 578 million revenue from operations, up 0.3% YoY. Meanwhile, the increase in several expense items caused the net profit to drop 22% YoY to USD 40.5 million.
Quarterly performance-wise, its revenue from operations in FY22 Q3 (September to December) dropped by 24% QoQ (see Chart 1). However, it is mainly because of the demerger of a subsidiary from Jubilant Pharma, which the subsidiary is responsible for active pharmaceutical ingredients business.
Chart 1: Quarterly Revenue from Operations of Jubilant Pharma
We noticed that the company’s gross margin in Q3 did not change much, but the overall profit margin has declined due to the consistently high R&D and employee expenses. There seems no sign of any strong catalyst that can trigger a recovery at this point. Fortunately, the company has focused on specialty products and services such as Radiopharma products and contract manufacturing operations, which offer a greater pricing power for the company given to their niche markets. These could serve as good protection for profit margin, and we expect the net margin to not deteriorate further.
Ample Short Term Liquidity; Leverage is Gradually Improving over Years
In mid-February, Fitch lowered the outlook of Jubilant Pharma from stable to negative, with credit rating affirmed at BB. One reason for the downgrade is because of the pressured profit margin, it could lead to a spike in expected net debt to EBITDA to 3.9x in FY23 (FY21: 1.8x). Despite the worsening ratio, we believe the number is still moderately healthy. Additionally, as the company is able to maintain positive free cash flows over the last few years, the overall risks are still manageable.
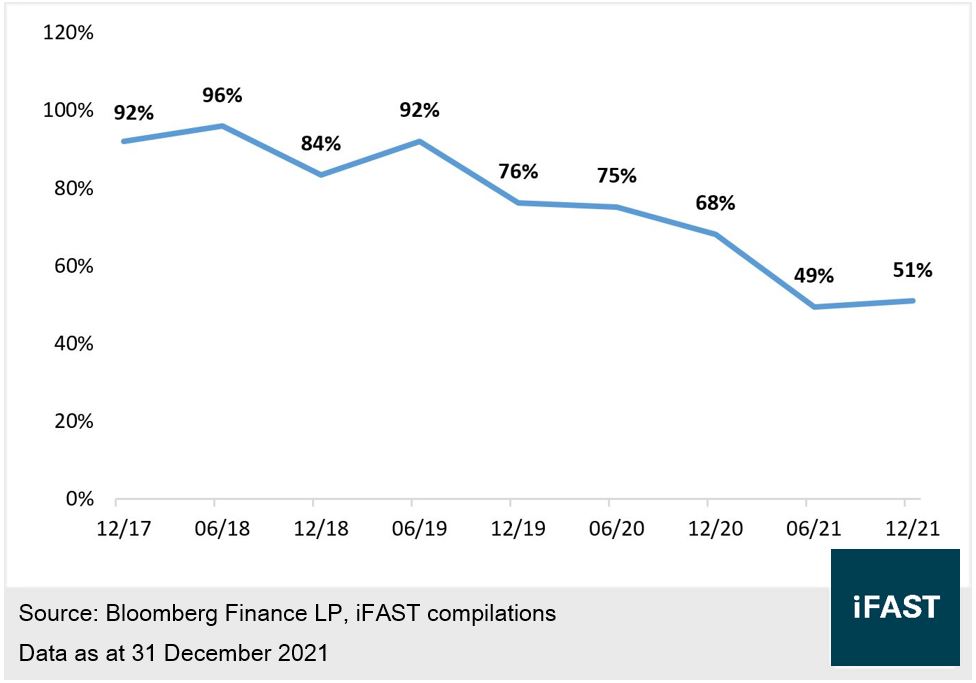
On the other hand, the total debt and cash balance of the company as of end-December last year were USD 404 million and USD 115 million. The amount of net debt has decreased. The credit performance is decent given to its 51% net gearing ratio, which has gradual improvements over the years (see Chart 2).
Chart 2: Net Gearing Ratio of Jubilant Pharma
The largest debt of the company is the USD 200 million bond due in March 2024. In the short term, it only has to face a USD 150 million term loan that has six equal quarterly instalments beginning October this year. Therefore, we think the company still has ample short term liquidity.
With reference to the distribution of long-term and short-term debts over the last few years, we believe the company may start to prepare for the repayment of the 2024 bond and refinance it in the next twelve months. A successful bond issuance could further lower the risk of this existing bond, and it is even possible for the issuer to exercise the redemption early.
2024 Bond is More Attractive than Peers’ as the Yield is around 5.8%
Jubilant Pharma’s sole USD bond JUBPSG 6.000% 05Mar2024 Corp (USD) is now offering a yield to maturity of 5.8%, with 1.9 years to maturity.
Jubilant Pharma is smaller in size compared to another Indian company Glenmark Pharmaceuticals, but Jubilant Pharma faces relatively less fierce competition with its focus on specialty products market. Therefore, both of them have a credit rating of BB / BB (S&P / Fitch).
Since there is no similar USD bond issued by Glenmark, we will use Teva Pharmaceutical, an Israeli company for comparison (see Chart 2). We can see that Jubilant Pharma’s bond is more attractive and investors can consider investing in it.
This bond will be on Bond Express soon, which allows investors to purchase with a lower cost.
Table 1: Bond Comparison
|
|
Issuer / Guarantor |
Credit Rating (S&P / Fitch) |
Years to Maturity |
Yield to Maturity |
|
Jubilant Pharma |
BB / BB |
1.9 |
5.8% |
|
|
Teva Pharmaceutical |
BB- / BB- |
2.0 |
4.3% |
|
|
Source: BSM Data as at 25 March 2022 |
||||
Corporate Risks
Jubilant Pharma only has one USD bond, and its outstanding amount accounted for half of the total debt. Given the concentrated debt distribution, the company may face a capital shortfall if they cannot refinance the bond as a result of the deteriorated credit condition.
In addition, the company has launched two corporate reorganizations recently. It demerged Jubilant Life Sciences Ltd (life science business) and Jubilant Generics Ltd (active pharmaceutical ingredients business) from Jubilant Pharma in February and August 2021 respectively, and transferred them to its parent company Jubilant Pharmova. Although it has legitimate reasons, the frequent reorganisation actions could bring concerns to the governance issue. As the actions required bondholders’ approval, it may also give a bad impression to the investors.
Conclusion
Jubilant Pharma is an India-based, North America-focused integrated pharmaceutical company. Although its profit margin has declined recently, the specialty pharmaceutical business could serve as a good protection.
The company has ample short-term liquidity, with gradual improvements in leverage over the years. Despite the weakened profitability, the overall risks are still manageable.
The yield of the USD bond due in March 2024 is around 5.8%, which is more attractive compared to the peers’ and investors can consider about it. This bond is available on Bond Express.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds positions in JUBPSG 6.000% 05Mar2024 Corp (USD), and the analyst who produced this report holds a NIL position in the abovementioned securities.









