


The COVID-19 pandemic has brought about major disruptions in businesses especially in retail and other commercial property segments as governments impose further lockdowns and social distancing restrictions due to the emergence of new waves of COVID-19 variants. Mapletree North Asia Commercial Trust (“MNACT”) reported its FY20/21 financial results on 22 Apr 2021 and has reported strong growth despite of virus headwinds.
About the issuer
MNACT is Singapore’s first real estate investment trust (“REIT”) that invest in properties situated in prime locations in China, Hong Kong SAR and Japan. Mapletree North Asia Commercial Trust Management Ltd., the manager of MNACT is a wholly-owned subsidiary of the Sponsor - Mapletree Investments Pte Ltd. Temasek Holdings is the ultimate parent of the company.
MNACT is expected to benefit from the Sponsor Right of First Refusal to MNACT, which under certain conditions, provides the REIT with access to potential future acquisitions and other income-generating commercial properties located in the North Asia region.
As of 22 Jun 2021, MNACT has a market capitalisation of approximately SGD 3.66 billion. Its property portfolio comprises of properties in Hong Kong, China, Japan and South Korea.
FY 20/21 Financial results
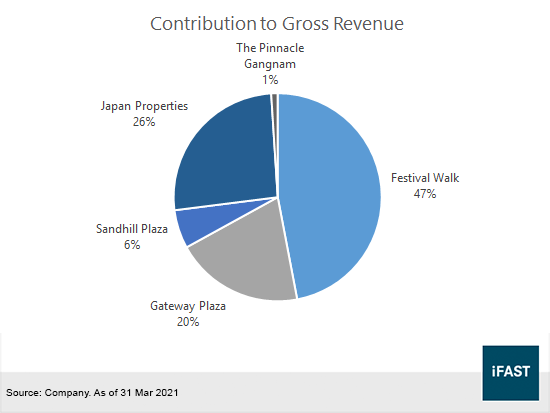
MNACT reported gross revenue of SGD 391.4m in the one year period ended 31 Mar 2021 (“FY20/21”), a 10.4% increase from the preceding financial year. Net Property Income (“NPI”) increased by 5.2% to SGD 292.0m as compared to FY19/20. Its portfolio consists of retail malls such as the Festival Walk in Hong Kong, Sandhill Plaza in Shanghai, Gateway Plaza in Beijing, Japan Properties in Tokyo and The Pinnacle Gangnam in South Korea.
Figure 1: FY20/21 contribution to gross revenue by property
Gross Revenue for Japan Properties and Sandhill Plaza increased from SGD 53.0m to SGD 101.3m and SGD 25.2m to SGD 25.8m respectively. NPI for Japan Properties and Sandhill Plaza increased by 66.1% and 2.6%, to SGD 66.3m and SGD 24.0m respectively. The increase in NPI in Japan Properties is largely due to full-year contributions from mBay Point Makuhari Building and Omori while the increase in NPI for Sandhill Plaza is largely due to a higher average rental and occupancy rate.
Gross revenue and NPI for Japan Properties is expected to continue growing following the acquisition of the single tenanted freehold office building in Japan – also known as the “Hewlett-Packard Japan Headquarters” at 2-1, Ojima 2-chome, Tokyo.
Figure 2: Portfolio Breakdown by Asset
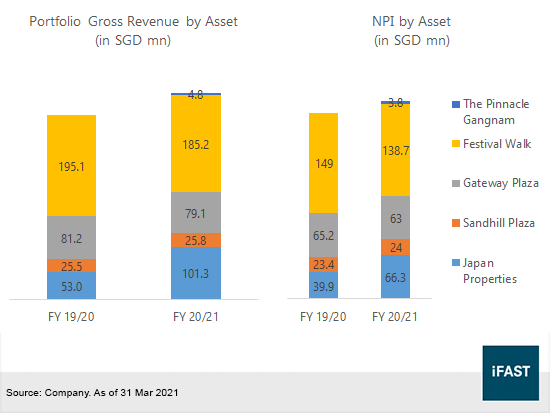
Gross revenue for Festival Walk and Gateway Plaza declined 5.1% and 2.5% respectively. NPI for Festival Walk declined by 6.9%, from SGD 149.0m to SGD 138.7m while NPI for Gateway Plaza declined by 3.4%, from SGD 65.2m to SGD 63.0m. The decline in NPI is largely due to lower average rental and occupancy rate from both properties.
Additionally, the loss in NPI for Festival Walk was also due its temporary closure from 13 Nov 2019 to 15 Jan 2020. Insurance claims were filed for the loss of revenue due to business interruption and property damages. The finalisation of the claims still remains in progress and the insurance proceeds will be recorded as non-operating income in MNACT’s financial statements. The insurance claims will mitigate losses from the temporary closure of Festival Walk.
As of 31 Mar 2021, MNACT has a portfolio occupancy rate of 97.0% despite of COVID-19 disruptions and restrictions. Moving forward, the management expects a high occupancy rate in all its properties. In April 2021, about 80% of the office community has since returned to office.
Acquisition of Freehold Building in Greater Tokyo, Japan
On 28 May 2021, MNACT acquired a freehold single-tenanted office building in Greater Tokyo, Japan, known as “Hewlett-Packard Japan Headquarters”. This acquisition is deemed to be accretive to earnings as this acquisition is expected to diversify MNACT’s property portfolio and bolster its current Japan Properties portfolio. Pro-forma aggregate leverage as at 31 Mar 2021 is projected to increase from 41.5% before the acquisition to 41.9% post-acquisition.
The property is leased to Hewlett-Packard Japan, which is the only tenant of the property. They have been the sole tenant of the property since its completion and Hewlett-Packard Japan still has a balance lease term of 8.8 years on the property. This acquisition is expected to provide MNACT a stable income stream and resilience to MNACT’s portfolio.
With this acquisition, assets under management (AUM) of the Enlarged Portfolio will expand to SGD 8.4b, contributing to 6.0% increase from the Existing Portfolio of SGD 7.9b. NPI contribution from Japan Properties will increase from 22.4% to 26.7%, bolstering the already growing NPI of Japan Properties, which saw an increase of NPI of 66.1% in FY20/21.
Liquidity Profile
Total borrowings added to SGD 3.28b in FY20/21, a 3% decrease from FY19/20. We are comfortable with MNACT’s liquidity, with cash and cash equivalents of SGD 252.2m, SGD 207.4m of current borrowings and cash flows from operations of SGD 342.6m. Interest coverage ratio increased from 3.5x to 3.7x as compared to the prior year. Aggregate leverage ratio for MNACT is 41.5%, which puts it below the regulatory limit of 50%. With MNACT’s healthy liquidity and reasonable financial leverage, we expect MNACT to be able to pay off its short-term debts.
Figure 3: Debt Maturity Profile of MNACT
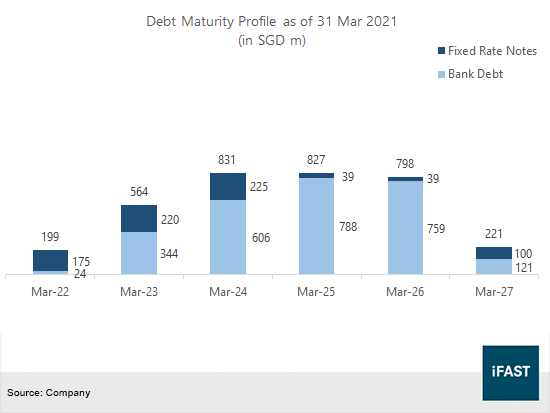
MNACT has a healthy liquidity position of committed and uncommitted undrawn credit facilities of SGD 513.8m and cash and cash equivalents of SGD 252.2m. The average term of maturity of MNACT’s debt profile is 3.12 years. MNACT’s healthy liquidity position and well-spread debt maturity profile puts it in a favourable position to tide through any short-term economic disruptions.
Bond recommendations
MNACT issued SGD 250m MAGIC 3.500% Perpetual Corp (SGD) on 31 May 2021 under MNACT’s USD 1.5b Euro Medium Term Securities Programme and will bear an initial rate of distribution of 3.50% per annum for the first five years. The issuance will provide funding for MNACT for general corporate purposes, including funding the above mentioned acquisition of a freehold building in Japan.
We compare the newly issued perpetual securities (“perp”) with other comparable REITs such as Suntec REIT MTN Pte. Ltd. (“SUNSP”) and Capitaland Retail China Trust (“CRCTSP”).
Table 1: Credit Ratios of other REITs
|
MNACT |
SUNSP |
CRCTSP |
|
|
Interest Coverage Ratio |
3.7x |
2.6x^ |
4.1x |
|
Aggregate Leverage Ratio |
41.5% |
44.3%^ |
35.1% |
|
Net Debt/Equity |
68.8% |
75.2%^ |
48.9%^ |
| Source: Company, iFast estimates. Data as of 31 March 2021, ^Data as of 31 December 2021. Note: Interest coverage is measured as trailing twelve month EBITDA/interest expense while aggregate leverage ratio is debt/total deposited property value. | |||
By comparing the key credit metrics of other REIT peers, we see that MNACT has a high interest coverage ratio of 3.7x, only losing out to CRCTSP. Aggregate leverage ratio for MNACT is higher than its peers, with CRCTSP having a lower gearing than MNACT. However, all companies mentioned above are well below the regulatory limit of 50%.
Figure 4: Perpetual SGD notes issued by MNACT and other REITs
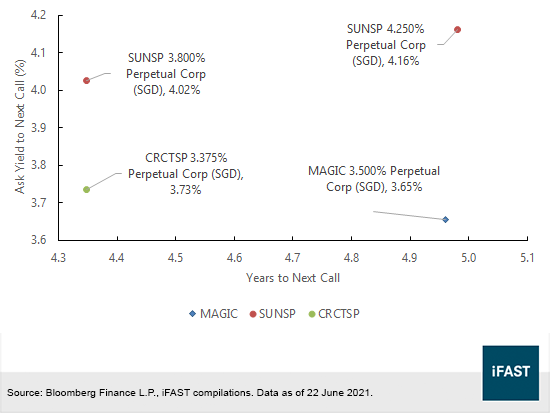
From Figure 4, when compared to other perps with similar years to next call (“YTC”), we can see that the MAGIC 3.500% Perpetual Corp (SGD), which is issued by MNACT, compares relatively well with other similar SGD REITs such as CRCTSP and SUNSP. The MAGIC 3.500% perp as of 22 June 2021, have a YTC of 3.65%. Investors looking into purchasing perps may also consider perps such CRCTSP 3.375% Perpetual Corp (SGD) or SUNSP 3.800% Perpetual Corp (SGD) as the perps offer a higher YTC as compared to MAGIC 3.500% Perpetual Corp (SGD) and the companies have similar or better credit ratios than MNACT.
Figure 5: Fixed rate SGD notes issued by MNACT and other REITs
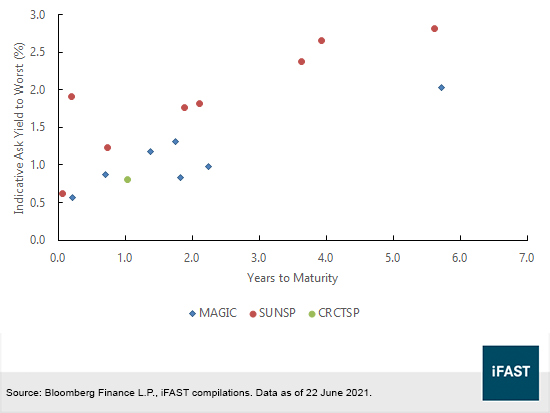
From Figure 5, when compared to other fixed rate notes from the same peers, we see that MNACT offers relatively lower ask yield to worst (“YTW”) than its peers.
All in all, MNACT’s prudent management of its balance sheet and liquidity allows the company to tide through any short term business disruption. Looking forward, its recent acquisition will bolster its current portfolio’s resilience and provide regional diversification to its portfolio. We think that given its strong credit fundamentals, MNACT will be able to tide through the pandemic and benefit from higher retail shopper traffic after the pandemic.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position SUNSP 3.800% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









