


Highlights:
- Mirae has delivered standout results over the past 18 months, with segments like trading, brokerage and wealth management also achieving double-digit growth. The company’s strategic global expansion—driven by targeted acquisitions—has significantly boosted overseas brokerage revenue and subsidiary profits. This has led to a notable improvement in overall profitability.
- As one of Korea’s largest securities firms by capital, Mirae has seen a marked rise in its net capital risk coverage ratio, thanks to growing profits from overseas operations. The ratio remains among the highest in the industry, and the firm maintains solid liquidity, reflecting a healthy credit position.
- Given its strong operational performance and stable credit fundamentals, we view Mirae’s bonds as relatively low-risk investments. For those interested in Korean corporate bonds, the 2029 bond presents an attractive opportunity.
Over the past year, South Korea’s political and economic landscape has faced growing uncertainty. President Yoon Suk-yeol’s hardline policies, combined with U.S. tariffs targeting semiconductors and electric vehicles, have added pressure to the region. Despite these headwinds, South Korea’s stock market later staged a strong 28% rebound in Q2 2025. Against this backdrop, we take a closer look at how Mirae Asset Securities (referred to as "Mirae")—the country’s largest financial firm—has leveraged its overseas operations to thrive through market turbulence.
Double-Digit Growth in Brokerage and Wealth Management, Exceptional Trading Performance
Mirae’s business is structured around four key segments: trading income, brokerage, wealth management, and investment banking—all of which are sensitive to market sentiment. Among them, trading and brokerage are the company’s core revenue drivers, accounting for approximately 49% and 31% of total operating revenue in 2024, respectively (see Table 1).
Table 1: Mirae’s Revenue and Profit Breakdown
| (KRW Billion) | 2024 | YoY Change | 1H25 | YoY Change | |
| Revenue | Brokerage | 704.9 | +28% | 415.0 | +18% |
| Wealth Management | 281.8 | +15% | 154.0 | +10% | |
| Investment Banking | 185.8 | -7% | 83.9 | -5% | |
| Trading Income | 1,111.0 | +36% | 801.9 | +36% | |
| Total Revenue | 2,283.5 | +24% | 1,454.8 | +24% | |
| Profits | Operating profit | 924.2 | +83% | 599.0 | +16% |
| Net profit | 921.6 | +186% | 662.0 | +82% | |
| Source: Company reports, iFAST Compilations Data as of 30 June 2025 | |||||
Among the four core business segments, brokerage and wealth management are relatively stable. Brokerage benefits from consistent commission revenue tied to trading activity, while wealth management generates recurring income from a solid base of assets under administration and stable fee structures. The two segments exhibit relatively low volatility and provide dependable cash flow, serving as the company’s financial backbone.
In contrast, trading income is inherently more volatile, driven by proprietary trading performance. However, Mirae demonstrated strong execution and disciplined risk management, with trading income rising 36% year-on-year in both 2024 and the first half of 2025.
Although investment banking faced a slight decline due to cyclical market conditions and broader uncertainty, the resilience of core businesses—particularly brokerage and wealth management—was evident in their double-digit growth. This reflects the firm’s robust operating foundation and strong client retention in a competitive domestic landscape.
As a result, net profit attributable to shareholders surged to KRW 921.6 billion in 2024, marking a 186% year-on-year increase, and continued to grow by another 82% in the first half of 2025, reaching KRW 662 billion.
Overseas Expansion: The Catalyst for Breakout Growth
A deeper look into the company’s brokerage business reveals Mirae’s dominant position as one of South Korea’s largest securities firms, with about 11% market share by trading volume. Despite a challenging 2024—characterized by weak semiconductor earnings and political instability under President Yoon Suk-yeol, which dragged the KOSPI down by approximately 10%—the firm’s domestic brokerage revenue remained resilient at KRW 421.8 billion, nearly flat compared to the previous year.
In 2025, market sentiment rebounded sharply. Semiconductor leaders such as Samsung Electronics and SK Hynix posted stronger earnings, the US temporarily suspended its proposed 25% export tariffs on Korean goods in April, and newly elected President Lee Jae-myung introduced policies aimed at stabilizing governance and stimulating investment. These developments fueled a rally in the KOSPI, which surged from around 2,400 points at the beginning of the year to over 3,000 by mid-Q2, representing a gain of more than 28% (see Chart 1).
Chart 1: KOSPI Performance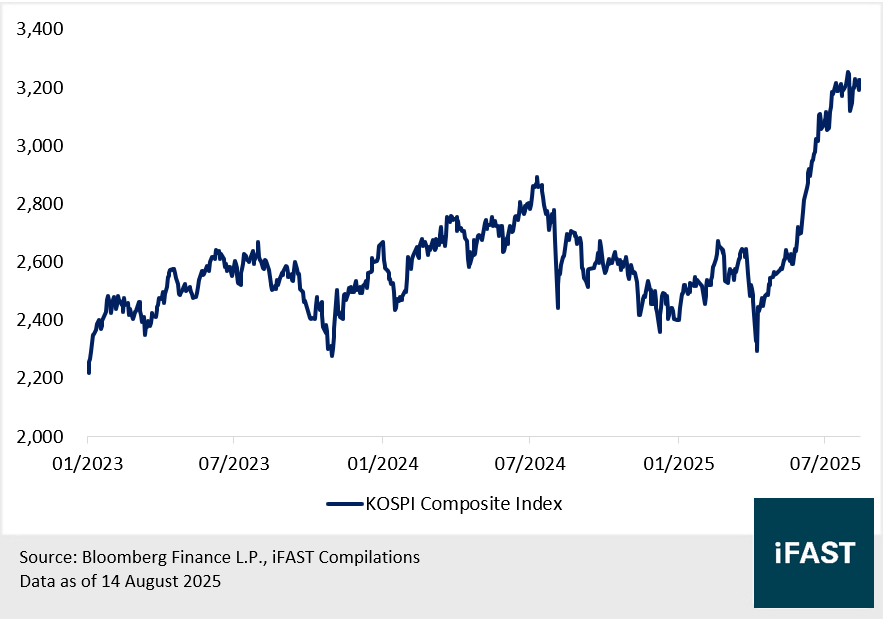
Benefiting from the rebound in South Korea’s equity market and strong global performance, particularly in the U.S. and the technology and healthcare sectors, Mirae’s domestic business saw a notable recovery in the second quarter of 2025. Domestic brokerage revenue rose 23% quarter-on-quarter and 8% year-on-year to KRW 119.8 billion, marking one of the strongest quarterly performances in recent years.
However, the real catalyst behind the company’s earnings breakthrough lies in the robust expansion of its overseas business. In recent years, Mirae has aggressively expanded its global footprint through strategic acquisitions. A key milestone includes the December 2023 acquisition of Sharekhan, India’s tenth-largest brokerage, which helped lift the proportion of overseas brokerage revenue from 31% in 2022 to nearly 50% by the first half of 2025 (See Chart 2).
Chart 2: Mirae’s Brokerage Revenue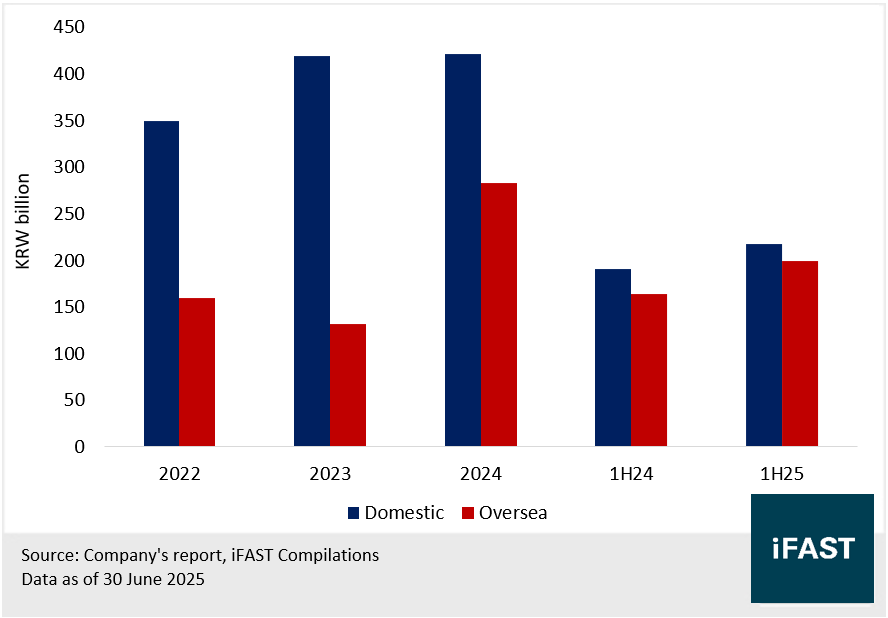
Despite temporary market volatility in early 2025—triggered by tariff proposals from U.S. President Donald Trump—uncertainty gradually subsided. Leveraging the benefits of its acquisitions and expansion, Mirae’s overseas stock balance surged from KRW 237 trillion at the end of 2023 to KRW 396 trillion by mid-2025. This drove overseas brokerage revenue up 110% year-on-year to KRW 283.1 billion in 2024, with a further 22% increase in the first half of 2025. Crucially, the average commission rate for overseas business stood at approximately 0.13%, significantly higher than the domestic rate of 0.029%. This uplift in margin contributed meaningfully to overall profitability, making overseas operations the core driver of earnings growth.
In the first half of 2025, Mirae Securities reported pre-tax profit of KRW 866.3 billion, with overseas subsidiaries contributing approximately 26% of the total. Their average quarterly pre-tax profit rose sharply to KRW 112.1 billion, well above the KRW 41.5 billion recorded in 2024, marking record highs for two consecutive quarters.
As the world’s twelfth-largest ETF provider and its Global X series gaining strong recognition across the industry, Mirae has continued to expand its ETF business in recent years. A key strategic move was the mid-2023 acquisition of UK-based ETF market maker GHCO, which further reinforced the firm’s competitive edge in developed markets such as the U.S., Hong Kong, and Europe.
In emerging markets, Mirae has actively promoted digital wealth management, focusing on high-growth regions including India, Indonesia, Brazil, and Vietnam. Looking ahead, overseas operations are expected to remain a key growth driver for the company.
Strong Capital Adequacy and Healthy Credit Profile
Just as capital adequacy is essential for commercial banks, it is equally critical for securities firms. In South Korea, the Net Capital Risk Coverage Ratio is a key regulatory indicator used to assess a firm’s ability to absorb market and operational risks. Calculated as risk-weighted net capital divided by capital requirements, the ratio ensures firms maintain sufficient buffers to navigate volatility.
As one of the largest securities firms in South Korea by capital base, Mirae Securities has seen a notable uplift in its Net Capital Risk Coverage Ratio in recent years, supported by strong earnings from overseas operations. In the first half of 2025, the ratio reached a robust 2,929%—not only far above the 100% regulatory threshold, but also significantly ahead of peers such as Samsung Securities, which stood at approximately 1,685% (see Chart 3), reinforcing Mirae’s leading position in the industry.
This strong capital position not only reflects Mirae’s solid financial foundation, but also enables greater flexibility in executing strategic initiatives—such as overseas acquisitions, launching new products like ETFs and digital asset platforms, and taking a more proactive approach in proprietary trading to pursue higher returns.
Chart 3: Mirae's Net Capital Risk Coverage Ratio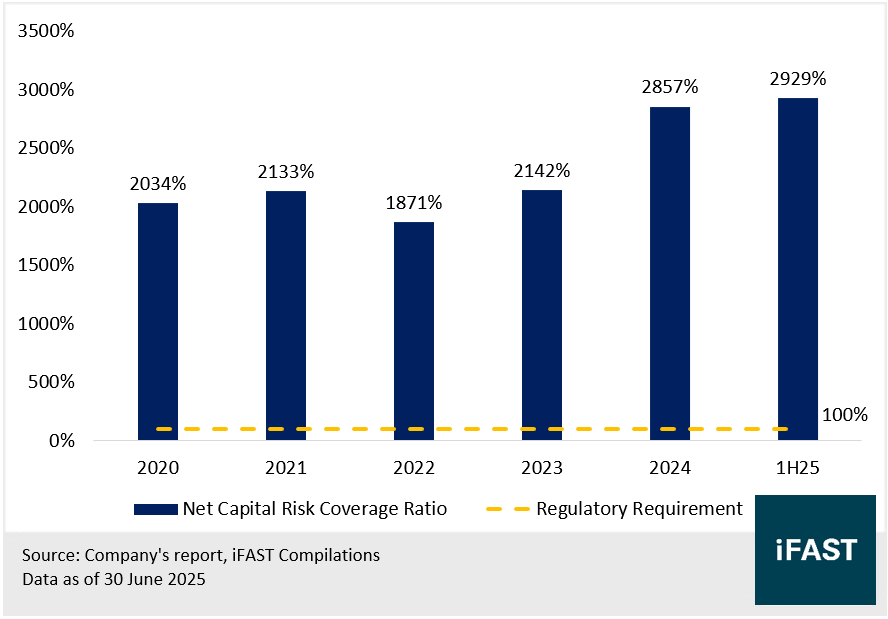
In parallel, the company’s liquidity position remains solid. The company’s cash and other financial assets have shown a steady upward trend in recent years, reaching KRW 1,324 trillion (see Chart 4). Its self-owned debt stood at KRW 815 trillion, with the liquidity coverage ratio (cash and other financial assets/ total debt)—remaining stable at around 160%. This reflects a sound liquidity position and a healthy overall credit profile.
Chart 4: Mirae’s Liquidity Metric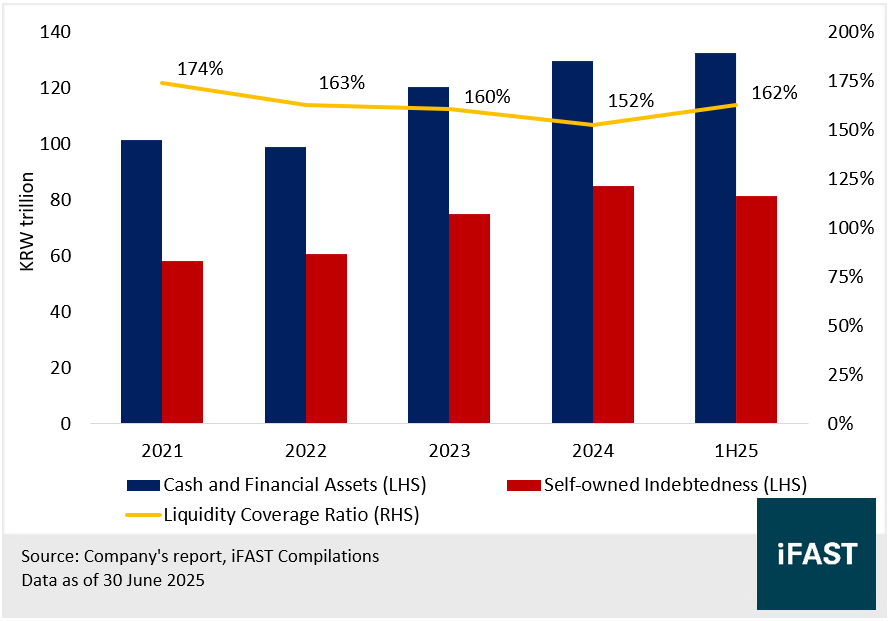
Bond Investment
There are currently four Mirae-issued bonds available on our platform. Both the issuer and the bonds carry a BBB rating from S&P, with yields to maturity ranging between 4.3% and 4.4% (see Table 2).
Given the company’s solid operating performance and stable credit profile, we view the investment risk as relatively low. For investors interested in Korean corporate bonds, the 2029 bond stands out as a rather attractive option.
Table 2: Mirae’s Bond Information
| Bond | Tenor (years) | Yield to Maturity |
| DAESEC 6.875% 26Jul2026 Corp (USD) | 0.9 | 4.3% |
| DAESEC 5.875% 26Jan2027 Corp (USD) | 1.4 | 4.3% |
| DAESEC 5.500% 31Jul2027 Corp (USD) | 1.9 | 4.3% |
| DAESEC 6.000% 26Jan2029 Corp (USD) | 3.4 | 4.4% |
| Source: Bondsupermart Data as of 8 September 2025 | ||
Related Risks
Mirae’s business is sensitive to market sentiment and economic cycles. A downturn in equity markets or broader economic conditions could negatively impact its core revenue streams and weigh on its credit performance.
In recent years, the company has made sizable investments in emerging markets such as Indonesia, Vietnam, India, and Brazil. Should these economies experience a slowdown, it may affect the firm’s cash flow and operational stability.
Additionally, Mirae has exposure to commercial real estate. If market conditions deteriorate or risk exposures are not properly managed, potential losses from property investments could impair asset quality and erode profitability.
Conclusion
Mirae has delivered standout results over the past 18 months, with segments like trading, brokerage and wealth management also achieving double-digit growth. The company’s strategic global expansion—driven by targeted acquisitions—has significantly boosted overseas brokerage revenue and subsidiary profits. This has led to a notable improvement in overall profitability.
As one of Korea’s largest securities firms by capital, Mirae has seen a marked rise in its net capital risk coverage ratio, thanks to growing profits from overseas operations. The ratio remains among the highest in the industry, and the firm maintains solid liquidity, reflecting a healthy credit position.
Given its strong operational performance and stable credit fundamentals, we view Mirae’s bonds as relatively low-risk investments. For those interested in Korean corporate bonds, the 2029 bond presents an attractive opportunity.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report holds a NIL position in the abovementioned securities.


