- Oxley is inviting bondholders of its 2023 bonds to extend the maturity for an additional 6 months, to be extended from 28 Feb 23 to 24 Aug 23
- The interest rate on the bond will also be raised from 6.50% to 7.50%
- The deadline for the exchange offer will be on 17 Feb 23, 12:00pm (SGT)
- We think the exchange offer from Oxley is likely due to the delays from the TOP of these projects which led the company to extend the maturity for just 6 months
- We think bondholders of the OHLSP 6.500% 2023 bonds should accept this exchange offer
Oxley Holdings Limited (“Oxley”) announced on 6 February 2023 that they will be launching an exchange offer for their OHLSP 6.500% 28Feb2023 Corp (SGD) bonds. Oxley is inviting bondholders of its 2023 bonds to extend the maturity for an additional 6 months, to be extended from 28 Feb 23 to 24 Aug 23. The interest rate on the bond will also be raised from 6.50% to 7.50%. The deadline for the exchange offer will be on 17 Feb 23, 12:00pm (SGT).
1H23 Financial Results
For its full year financial results ending 31 December 2022 (“1H23”), Oxley reported total revenue of SGD 438.4m, a 13% decrease from 1H22. The fall in revenue was mainly due to lack the sale of land parcel in Australia executed in 1H22 which boosted its revenue during that time. Pre-tax profit also fell to SGD 4.6m due to higher financing costs.
In 1H23, Oxley had cash and cash equivalents of SGD 152.9 while maintaining a positive cash flow from operations of SGD 195.1m. Total loans and borrowings amounted to SGD 2.1b, resulting in its gearing ratio to be 1.89x.
Figure 1: Debt Maturity Profile of Oxley
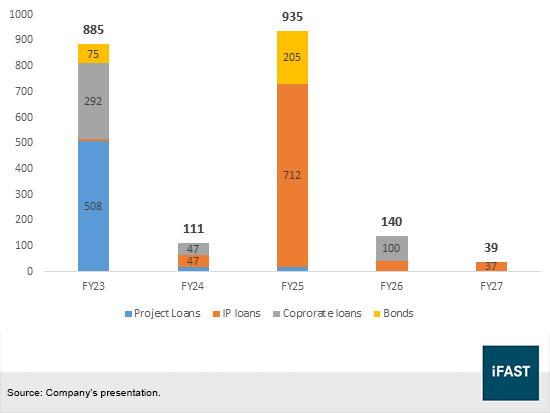
In Figure 1, Oxley has SGD 885m of debt maturing in FY23 while only having SGD 195.1m of cash. While the amount owed by Oxley may seem large, Oxley intends to repay their maturing loans through proceeds from their development properties. Oxley has 6 development properties scheduled to attain their Temporary Occupancy Permit (“TOP”) in Singapore (Table 1). This accounts for SGD 1,046b of billings expected to be recognised when the properties reach their TOP.
Table 1: 5 properties from Oxley is expected to reach TOP in 2023
|
Development |
TOP |
Future progress billings (SGD m) |
|
Affinity @ Serangoon |
2Q23 |
249 |
|
1953 |
1Q23 |
19 |
|
Kent Ridge Hill Residences |
1Q23 |
393 |
|
Mayfair Gardens |
1Q23 |
129 |
|
Parkwood Residences |
1Q23 |
13 |
|
Riverfront Residences |
1Q23 |
243 |
|
Total: |
1,046 |
|
|
Source: Company Presentation. |
||
We think the exchange offer from Oxley is likely due to the delays from the TOP of these projects which led the company to extend the maturity for just 6 months. Most projects listed in Table 1 were projected to attain TOP from 2Q22 to 4Q22. While Oxley have sufficient cash to redeem the 2023 notes in full, we think Oxley is maintaining some headroom and flexibility to also repay some of its bank loans that will be maturing in 2023. Maturities for Oxley’s borrowings are concentrated between 1Q23 to 2Q23 (Table 2). Extending the 2023 bonds by another 6 months will allow Oxley some flexibility and headroom to repay all of its borrowings in the event where there will be further delays in TOP from its projects.
Table 2: Some of Oxley’s borrowings due in 2023 - 2024
|
Borrower |
Lender/ Facility Agent |
Maturity |
Outstanding amount (m) |
|
Oxley Holdings Limited |
Credit Suisse AG, Singapore Branch as agent |
9 April 2023 and 16 April 2023 |
SGD 205 |
|
Oxley Spinel Pte. Ltd. |
Oversea-Chinese Banking Corporation Limited as facility agent |
Earliest of 25 July 2023, 6 months from the TOP Date and 30 September 2023 |
SGD 179 |
|
Oxley Gem Pte. Ltd. |
The Hongkong and Shanghai Banking Corporation Limited, Singapore Branch as facility agent |
31 October 2024 |
SGD 540 |
|
Oxley Holdings Limited |
Dragons 619 Limited as lender |
31 March 2023 |
USD 85.97 |
|
Oxley Holdings Limited |
United Overseas Bank Limited |
30 December 2023 |
SGD 100 |
|
Source: Oxley’s Euro Medium Term Note Programme Offering Circular |
|||
What should you do if you hold the 2023 bonds?
For the Oxley 2023 bondholders, the exchange offer is rather enticing as it offers a step up on the bond’s interest rate to 7.50% while only extending the bond maturity by 6 months. We think bondholders of the OHLSP 6.500% 2023 bonds should accept this exchange offer.
We do not think there are major credit issues with Oxley and likely the extension of the 2023 bonds is due to the delays in TOP of its projects that have resulted in Oxley receiving cash flows from its projects later than expected. The cash flows needed to repay Oxley’s maturing borrowings is visible. Most of the units reaching TOP in 2023 have mostly been fully sold and once it reaches TOP, Oxley can recognise the revenues from these properties. The additional 1% step up on its coupon provides a good incentive for bondholders as they earn additional interest for extending the bond for a short 6 months tenor.
Oxley 2024 bondholders
Oxley’s debt maturing in FY25 increased from SGD 267m to SGD 935 mainly due to the refinancing of its IP loans from FY23 to FY25. For Oxley to repay the 2024 bonds, cash flows would need to come from its property developments projects due in 2024. Within Oxley’s pipeline of development projects, Riverscape (in the UK) and Oxley Towers KLCC (in Malaysia) are expected to be completed in 2024 with effective gross development values of SGD 341m and SGD 880m respectively. For the rest of its borrowings in FY25, Dublin Arch in Ireland is expected to gross an effective SGD SGD 1.26m of development value to Oxley, which should be sufficient to cover its maturing borrowings in FY25.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OHLSP 6.900% 08Jul2024 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!