Standard Chartered PLC (“StanChart”) has launched a consent solicitation exercise (“CSE”) to modify the terms of the STANLN 7.500% Perpetual Corp (USD), STANLN 7.750% Perpetual Corp (USD) and STANLN 5.375% Perpetual Corp (SGD).
What are the relevant securities under the CSE?
Table 1: StanChart USD and SGD perpetual notes under the CSE
|
|
Next call date |
Moody’s |
S&P |
Fitch |
|
2 April 2022 |
Ba1 |
BB- |
BBB- |
|
|
2 April 2023 |
Ba1 |
BB- |
BBB- |
|
|
3 October 2024 |
Ba1 |
BB- |
BBB- |
|
| Source: Bloomberg Finance L.P., Company. As of 6 October 2021 | ||||
Table 2: Examples of recently issued Additional Tier 1 securities (for reference)
|
|
Next call date |
Pricing date |
|
STANLN 6.000% Perpetual Corp (USD) |
26 July 2025 |
17 June 2020 |
|
STANLN 4.300% Perpetual Corp (USD) |
19 August 2028 |
10 August 2021 |
|
STANLN 4.750% Perpetual Corp (USD) |
14 January 2031 |
5 January 2021 |
| Source: Bloomberg Finance L.P., Company. As of 6 October 2021 | ||
Background and issuer's proposal
The issuer, Standard Chartered PLC, is seeking to align the conditions of the abovementioned perps (collectively the “old AT1s”) in Table 1 with those of recently issued AT1s (“new AT1s”) with new Subordination Provisions in Table 2. Currently, the old AT1s have differing subordination provisions as compared to the new AT1s.
StanChart has a number of outstanding Preference Shares, which presently qualify as AT1 capital. Together with the AT1s, the existing Preference Shares and AT1s rank pari passu with each other.
However, these Preference Shares only qualify as AT1 Capital by virtue of grandfathering provisions which apply for the Transitional Period (CRD IV Regulation transitional period ending 31 December 2021). Therefore, given the end of the Transitional Period, existing Preference Shares will no longer qualify as AT1 capital and may instead be recognised as Tier 2 Capital.
Under the terms of the new AT1s, the issuer is allowed to subordinate the new AT1s to Preference Shares or any Pari Passu securities in its sole discretion. According to our interpretation, existing Preference Shares and other Pari Passu Preference Shares securities, will be senior to the AT1s, if the issuer determines that the AT1s would not be included in Additional Tier 1 Capital unless the AT1s are already ranked senior at the point of determination.
Therefore, StanChart is proposing to change the provision of the old AT1s to be in line with the recent issues so that the issuer will be able to retain such securities as AT1 Capital after the end of the Transitional Period.
More specifically, the issuer aims to change the terms of “Senior Creditors”, Condition 4(a) (Conditions to Payment), and Condition 4(b) (Winding-up prior to a Conversion Trigger Event) as well as the definition of “Parity Securities” upon the passing of the CSE resolutions.
What is the credit rating impact?
It is the issuer’s expectation that the amendment of the terms will NOT result in the downgrade, qualification or withdrawal of current credit ratings assigned to any of the old AT1s.
What are the existing Preference Shares?
The GBP denominated preference shares are the 8.25% non-cumulative irredeemable preference shares that have an aggregate paid up amount of GBP 99,250,000 (ISIN: GB0008399700); and (ii) 7.375% non-cumulative irredeemable preference shares with an aggregate paid up capital of GBP 96,035,000 (ISIN: GB0008401324).
USD denominated Preference Shares refer to the 6.409% non-cumulative redeemable preference shares (aggregate paid up amount: USD 750,000,000) and 7.014% non-cumulative redeemable preference shares (with an aggregate paid up amount of USD 750,000,000).
Noteholders are entitled to early consent fees
Noteholders who register their vote in favour of the Extraordinary Resolution on or before 19 October 2021, 5pm, New York Time will be eligible to receive an early consent fee. With respect of the STANLN 7.500% Perpetual Corp (USD) and STANLN 7.750% Perpetual Corp (USD), noteholders will receive USD 500 for every USD 200,000 of holdings. In respect of the STANLN 5.375% Perpetual Corp (SGD), noteholders will be paid SGD 625 for every SGD 250,000 of the securities.
However, those who register their vote in favour of the Extraordinary Resolution after 19 October 2021, 5pm, New York Time but before 26 October 2021, 9.30am (London Time) will be entitled to receive a late consent fee. Pertaining to the STANLN 7.5% and 7.75% perps, noteholders will receive USD 200 for every USD 200,000 of principal amount of the securities, and SGD 250 per SGD 250,000 principal amount of the STANLN 5.375% perps.
Recommended action
We advise noteholders to vote in favour of the Extraordinary Resolution before 19 October 2021, 5pm, New York Time so that they may receive the early consent fee. According to the issuer, there is no expected credit rating impact to the perps. At this juncture, we also think that the issuer will still call the perps on their respective call dates in view of their comfortable funding profile and recent credit performance, which is reported below.
As mentioned, the new subordination clause will allow the issuer to include the old AT1s as part of AT1 capital after December 2021. Even though the perps will be ranked below preference shares in a liquidation or winding up event, there is no need to consider this for now as we believe that the issuer is healthy and there is still a good chance that the perps will be redeemed on its call dates.
Result announcement
Various virtual meetings will be held on 28 October 2021, from 9.30am (London Time) to pass the relevant Extraordinary Resolutions. A majority of not less than 75% of the votes cast is required to pass the Extraordinary Resolution. If the relevant Extraordinary Resolution is passed, the outcome shall be binding on all holders of the relevant securities.
Financial performance
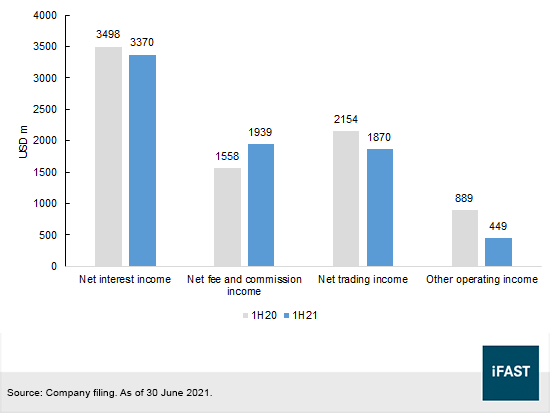
On 3 August 2021, Standard Chartered PLC reported financial results for the 6 month period ended 30 June 2021 (“1H21”). Operating income, which is mainly made up of net interest income, fee and commission income and net trading income, declined by USD 471m between 1H20 and 1H21. As seen in Figure 1, StanChart recognised lower net interest and trading income, but saw higher fee and commission income. Interest income would have been lower had it not been for a positive USD 73m interest income catch-up adjustment.
Overall operating income was lifted by a record performance in wealth management and a 6% growth in customer loans. The bank witnessed a strong sales performance in FX, equities, and structured notes and this was underpinned by its digital investments and asset management growth. Geographically, profits in Asia climbed 41% on the back of lower credit impairments offset by lower income and higher expenses. Profits in Africa & Middle East increased five-fold to USD 475m, thereby representing the best earnings performance in the past five years.
Figure 1: Operating income breakdown in 1H21 vs 1H20
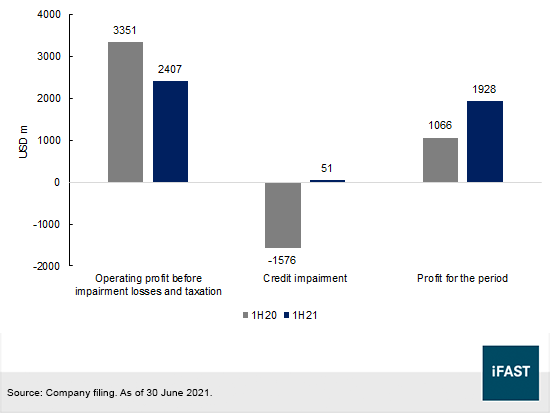
Moving on to its bottom-line, group net profit jumped USD 862m to USD 1.93b at 1H21. This was largely driven by a big reversal in credit impairments (see Figure 2). Operating profit before impairments and taxation declined by USD 944m to USD 2.41b. Credit impairments fell because of additional collateral and guarantees that were provided to the bank, coupled with a significant USD 841m drop in stage 3 impairments.
Figure 2: Net profit in 1H21 and 1H20
Bank capital and liquidity positions are strong. Liquidity coverage ratio (“LCR”) remained around 146% in 1H21 (up from 143% at 2H20) with a USD 167.8b liquidity buffer (2H20: USD 175.9b). LCR was supported by lower net outflows and better liability quality. Bank funding is decent as the ratio of Current Account Savings Accounts to Total Customer Deposits stayed around 66% in 1H21.
Capital adequacy measured by CET1 ratio was 14.1% in June, this is a healthy level as it is well above the 9.9% MDA (Maximum Distributable Amount) threshold and above its 13-14% target. As we understand, StanChart has USD 3.2b of senior notes due in 2021 and USD 8.5b of debt due in 2022 (including USD 2.0b of AT1s). This year, the issuer exercised its right to redeem the SGD 700m STANLN 4.400% 23Jan2026 Corp (SGD) that was callable in January 2021. On 23 March 2021, they issued EUR 1.2b of 1.2% fixed rate reset dated subordinated notes due 2031.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!