Tuan Sing Holdings Ltd (“Tuan Sing”) has announced a 4NC3 unsecured SGD bond at a final price guidance (FPG) of 7.50% (coupons paid semi-annually), available only for accredited and institutional investors. This new issuance will have a settlement date of 2 November 2023 and a maturity date of 2 November 2027. It also comes with an issuer call option at 102% of principal, callable (in whole and not in part) at any time on or after 2 November 2026.
The issuer Tuan Sing is currently unrated, while this new bond issuance is also unrated. The bond will be issued under Tuan Sing’s existing SGD 900m MTN programme. This new issuance will be used to (i) finance the ongoing tender offer for Tuan Sing’s 2024 bonds announced last week; (ii) the repayment and/or refinancing of indebtedness; and (iii) for general corporate purposes.
For our take on the recently-announced tender offer, as well as some financial highlights for Tuan Sing, check out this article: Tuan Sing announces tender offer for its SGD 6.90% notes due 2024.
Financial highlights
In the half year ended 30 June 2023 (1H23), Tuan Sing delivered a relatively resilient performance (Chart 1). Total revenues jumped +30% HoH and +27% YoY to SGD 144.7m in 1H23, helped by a large increase in the Real Estate Development segment of +58% YoY to SGD 42.1m in 1H23. The Hospitality segment also contributed to positive revenue growth following some normalisation from the COVID era.
Despite this, adjusted EBIT saw a decline of -9% YoY to SGD 30.0m in 1H23, though this was nonetheless a sizeable increase (+50% HoH) from that in 2H22. Despite the solid revenue performances in Real Estate Development and Hospitality described above, Tuan Sing saw adjusted EBIT declines (YoY) in both segments in 1H23. The Real Estate Development segment suffered from margin pressures arising from higher construction costs, while the Hospitality segment suffered from a weaker performance from hotel operations in Perth, partly due to disruptions from ongoing asset enhancement initiatives (AEIs).
In terms of Tuan Sing’s credit profile, we recently showed that several key credit ratios for Tuan Sing have recently shown signs of stabilising (Table 1). Nonetheless, investors should still note that its cash position has fallen from SGD 372.0m in 1H22 to SGD 236.2m in 1H23, though this was mainly due to its repayment of bank loans.
Chart 1: Tuan Sing’s revenues increased in 1H23, though adjusted EBIT declined
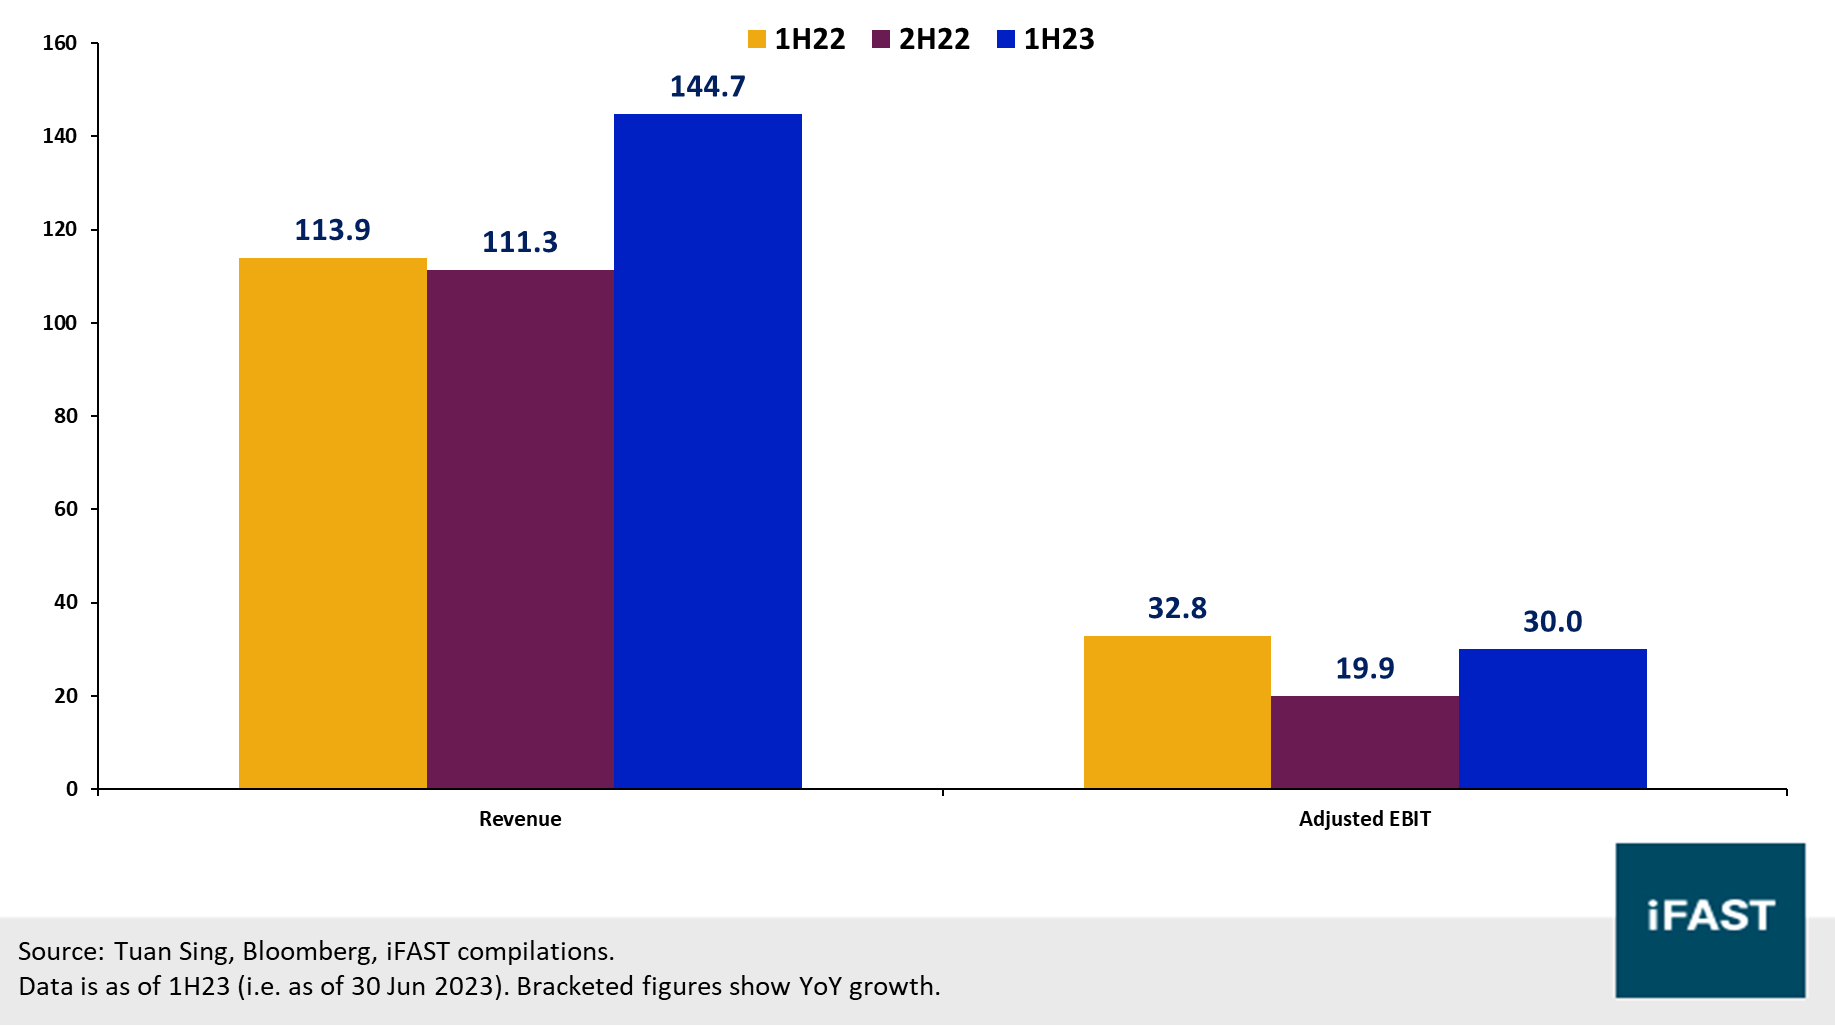
Table 1: Credit metrics of Tuan Sing
| Tuan Sing's Credit Metrics | 1H22 | 2H22 | 1H23 |
| Total Debt (SGD m) [A] | 1,334.8 | 1,278.2 | 1,217.1 |
| Total Assets (SGD m) [B] | 2,742.6 | 2,657.0 | 2,596.3 |
| Total Debt / Total Assets (%) [A/B] | 48.7% | 48.1% | 46.9% |
| Cash (SGD m) [C] | 372.0 | 252.0 | 236.2 |
| Net Debt (SGD m) [D = A - C] | 962.8 | 1,026.2 | 980.9 |
| Total Equity (SGD m) [E] | 1,264.2 | 1,224.8 | 1,233.0 |
| Gearing, or Net Debt / Equity (%) [D/E] | 76.2% | 83.8% | 79.6% |
| LTM Adjusted EBIT (SGD m) (F) | 38.6 | 52.7 | 49.9 |
| Net Debt / LTM Adjusted EBIT (X) [D/F] | 24.96 | 19.46 | 19.68 |
| Source: Tuan Sing, Bloomberg, iFAST compilations, iFAST estimates. Data as of 1H23. | |||
Outlook
Tuan Sing recently hosted a roadshow for this new issuance, where they also discussed the company’s outlook ahead. Management continued to strike a positive tone in this roadshow for several reasons – we highlight some below:
- Following ongoing AEIs in Perth, tenants of the first phase are expected to start moving in from 4Q23 to 1Q24.
- Of Tuan Sing’s existing 1.25 million sqm land bank in Batam, management estimates the first phase already completed in May 2023 (approximately 0.2 million sqm) has a potential gross development value of SGD 200m, with significant growth potential in the remaining 1.05 million sqm.
- Tuan Sing sees Link@896 as another opportunity given its geographical location, and believes it will be able to transform the building into a retail/lifestyle destination.
When we enquired about Tuan Sing’s debt profile, it mentioned that it had over SGD 500m in debt maturing in 2024 itself. This includes the SGD 141.75m bond which management is refinancing with this very tender offer/new issuance. It also includes secured loans (which account for a majority of its borrowings) which management has displayed confidence in refinancing, not only given their 100% refinancing track record but also because many of the company’s secured loans have relatively low loan-to-value ratios.
We generally agree that there continue to be multiple decent growth opportunities for Tuan Sing. Its debt levels also remain manageable for now given that its credit ratios appear to already be stabilising. However, we also reiterate that Tuan Sing continues to be a higher-risk-higher-reward issuer (compared to larger and more well-established developers).
About the new 4NC3 bond
This new 4NC3 bond (with a 7.50% coupon) is relatively similar in structure to the existing TSHSP 6.900% 18Oct2024 Corp (SGD) which was a 3NC2 bond, both of which are unsecured bonds with an issuer call option at 102% of principal (in whole).
However, investors should note that the interest rate environment has changed significantly since the issuance of the existing 2024 bond (in 2021). From 18 October 2021 to 20 October 2023 (about 2 years), the 3y SORA has increased by about 260 bps while the 4y SORA has increased by about 241 bps. Meanwhile, this new issuance’s coupon of 7.50% is just 60 bps higher than the existing 2024 bond’s 6.90%, less than the spreads compared to the previous issuance. Nonetheless, we also note that while credit metrics like net-debt-to-equity remain fairly similar to that in 2021, Tuan Sing’s profit outlook appears to be more optimistic than it was in 2021 given the multiple growth drivers management has highlighted above (especially given the improvement of Hospitality post-COVID as well).
For our take on the existing 2024 bond at the time of issuance, check out this article: Tuan Sing launches new 3NC2 SGD bond at a FPG of 6.90%.
We also consider this bond against its property developer issuer peers, like Oxley Holdings, Koh Brothers, and Heeton Holdings (Table 2). As a whole, we observe that these bonds generally have significantly different yields (to worst), and we believe this could be due to the divergence in issuer credit qualities.
In all, we think this new issue is fairly priced. Investors looking into this new issue should once again consider the credit risks related to Tuan Sing as an issuer. Those looking to tender their existing 2024 bonds and subscribe for the new issue should also consider the additional maturity and duration risks involved.
Table 2: Comparison against peers
| Bond Name | Maturity Date (Years to Maturity) |
Ask Price | Current Yield (%) | Ask Yield to Worst (%) |
| TSHSP 7.500% 02Nov2027 Corp (SGD)* | 02 Nov 2027 (4.0) |
100.000 | 7.50% | 7.50% |
| OHLSP 6.900% 08Jul2024 Corp (SGD) |
08 Jul 2024 (0.7) |
96.500 | 7.15% | 12.57% |
| KOHSP 6.500% 17Apr2026 Corp (SGD) |
17 Apr 2026 (2.5) |
103.917 | 6.25% | 4.80% |
| HTONSP 7.000% 03Nov2026 Corp (SGD) |
03 Nov 2026 (3.0) |
103.315 | 6.78% | 5.79% |
| Source: Bloomberg, Bondsupermart, iFAST
compilations. Data as of 20 Oct 2023. *Note: Not yet issued. |
||||
What should you do?
With this new issue going on at the same time as the previously announced tender offer, Tuan Sing has expressed an intention to “give priority” to existing bondholders who wish to participate in both the tender offer and new issuance. Only investors who participate in both can potentially get priority to both – in contrast, participating in only one of them does not give priority.
Investors who are willing to undertake the credit risks involved with Tuan Sing as well as the accompanying maturity and duration risks can consider participating in this new issuance. Coupled with our positive view on the tender offer, here are steps and timelines that investors should consider:
- Existing wholesale accredited and institutional investors who wish to participate in both the tender offer and new issuance should indicate this clearly to iFAST (or their advisors) by today (23 October – Monday).
- New wholesale investors who wish to participate in just the new issuance should also indicate this to iFAST (or their advisors) by today (23 October – Monday).
- Existing wholesale investors who wish to participate in just the tender offer should indicate this to iFAST (or their advisors) by 31 October latest.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in TSHSP 6.900% 18Oct2024 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!