- Tuan Sing has announced a tender offer for holders of its existing TSHSP 6.900% 18Oct2024 Corp (SGD) bonds.
- We think this tender offer is attractive, but investors should note Tuan Sing may not fully redeem the full outstanding amount of SGD 141.75m.
- Wholesale investors do not need to take concrete action today if they wish to participate in the tender offer. The critical date will be the "New Issue Pricing Date", which will likely be on 23 October (Monday).
Tuan Sing Holdings Ltd (“Tuan Sing”) has announced a tender offer for holders of its existing TSHSP 6.900% 18Oct2024 Corp (SGD) bonds. The tender price is 102% of the principal amount, which translates to SGD 255,000 in cash for every SGD 250,000 in principal amount. This tender offer is part of Tuan Sing’s strategy to actively manage its debt capital structure by improving its debt maturity profile and optimising financing costs.
For our take on Tuan Sing’s previous tender offer in Nov 2022, check out this article: Tuan Sing Tender Offer for its SGD 6.90% notes due 2024. For a credit update on Tuan Sing in 1H22, check out this article: Idea of the Week: This real estate developer might see a cash problem.
Financial highlights
Tuan Sing continued to display a relatively resilient performance in the half year ended 30 June 2023 (1H23) (Chart 1). Total revenues jumped +30% HoH and +27% YoY to SGD 144.7m in 1H23, due to broad increases across its three core segments (Real Estate Investment / Real Estate Development / Hospitality). Among these segments, Real Estate Development saw the largest revenue increase of +58% YoY to SGD 42.1m in 1H23, helped by higher progressive revenue recognition from Peak Residences. The Hospitality segment also saw higher revenues following the easing of COVID-related measures.
Despite this strong revenue showing, adjusted EBIT still marked a (small) decline of -9% YoY to SGD 30.0m in 1H23, though this nonetheless marked a decent improvement from that in 2H22 (+50% HoH). The Real Estate Development segment saw a slight decline in adjusted EBIT from SGD -0.1m in 1H22 to SGD -0.5m in 1H23 despite the strong revenue showing, as higher construction costs in Singapore hurt its margins. In addition, the Hospitality segment also saw a sharp -19% YoY decline in adjusted EBIT due to weaker performance from hotel operations in Perth.
As for Tuan Sing’s credit profile, we previously expressed some concern over Tuan Sing’s cash position. Since then, their cash position has fallen slightly from 2H22 to SGD 236.2m in 1H23, though we note that this was primarily due to the repayment of bank loans (totalling SGD 59.1m) rather than significant operating cash outflows. In addition, we observe that some other key ratios (e.g. total debt to total assets, net debt to equity, net debt to adjusted EBIT) have stabilised or improved somewhat over the past 6 months and 1 year.
Chart 1: Tuan Sing’s revenues increased in 1H23, though adjusted EBIT declined
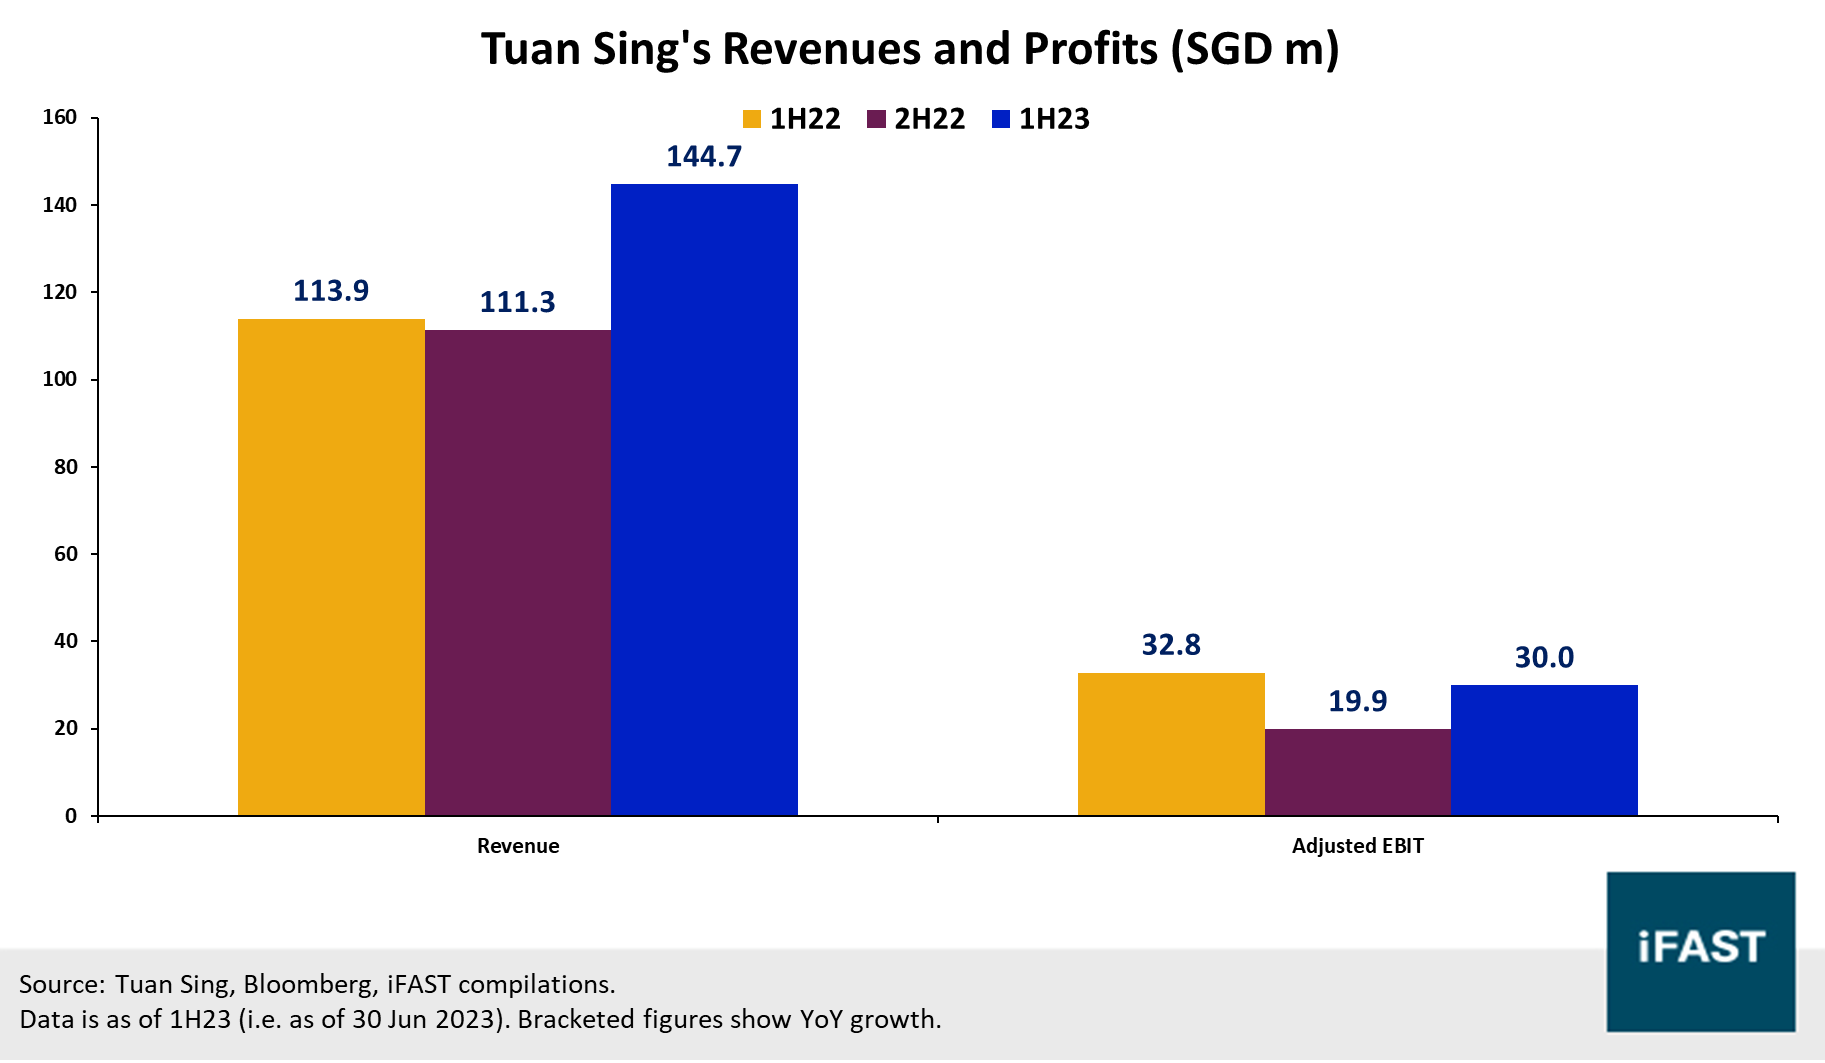
Table 1: Credit metrics of Tuan Sing
| Tuan Sing's Credit Metrics | 1H22 | 2H22 | 1H23 |
| Total Debt (SGD m) [A] | 1,334.8 | 1,278.2 | 1,217.1 |
| Total Assets (SGD m) [B] | 2,742.6 | 2,657.0 | 2,596.3 |
| Total Debt / Total Assets (%) [A/B] | 48.7% | 48.1% | 46.9% |
| Cash (SGD m) [C] | 372.0 | 252.0 | 236.2 |
| Net Debt (SGD m) [D = A - C] | 962.8 | 1,026.2 | 980.9 |
| Total Equity (SGD m) [E] | 1,264.2 | 1,224.8 | 1,233.0 |
| Gearing, or Net Debt / Equity (%) [D/E] | 76.2% | 83.8% | 79.6% |
| LTM Adjusted EBIT (SGD m) (F) | 38.6 | 52.7 | 49.9 |
| Net Debt / LTM Adjusted EBIT (X) [D/F] | 24.96 | 19.46 | 19.68 |
| Source: Tuan Sing, Bloomberg, iFAST compilations, iFAST estimates. Data as of 1H23. | |||
Peer comparison
While there are several high-yield property issuers with outstanding SGD bonds, we think the closest peer to TSHSP 6.900% 18Oct2024 Corp (SGD) bonds are likely Oxley Holding’s OHLSP 6.900% 08Jul2024 Corp (SGD) bonds. A quick comparison indicates that Tuan Sing’s bonds have significantly lower yields (despite the same 6.9% coupon) compared to their Oxley counterparts, though we attribute this large difference to the divergence in issuer credit qualities (Table 2).
Table 2: Comparison with other high-yield SG property bonds
| Bond Name | Maturity Date (Years to Maturity) |
Ask Price | Current Yield (%) | Ask Yield to Worst (%) |
| TSHSP 6.900% 18Oct2024 Corp (SGD) |
18 Oct 2024 (1.0) |
102.000 | 6.76% | 4.82%* |
| OHLSP 6.900% 08Jul2024 Corp (SGD) |
08 Jul 2024 (0.7) |
96.500 | 7.15% | 12.10% |
| Source: Bloomberg, Bondsupermart, iFAST
compilations. Data as of 17 Oct 2023. *4.82% is the yield from today, while our 4.98% estimate is the yield from expected settlement. |
||||
Is this tender offer attractive?
As a whole, while Tuan Sing’s recent performance did improve over previous financial periods, we emphasise that it continues to be a higher-risk-higher-reward option for investors (rather than a safer option). Taken in this context, investors should expect to be rewarded appropriately (i) not only for taking on credit risks but also (ii) with consideration to the higher interest rate environment (compared to the time of bond issuance).
Using a simple estimation of 0.96 years from expected settlement to maturity, with existing information on this bond, we estimate the yield for holding onto these bonds to be about 4.98% (Table 3). We think the estimated yield for holding on to maturity (4.98%) may be insufficient considering the two factors above regarding credit risks and the different interest rate environment.
Therefore, we think this tender offer is attractive (compared to the alternative of holding on to maturity). Investors should nonetheless note that Tuan Sing may not fully redeem the full outstanding amount of SGD 141.75m, and acceptance of their tender offers is at Tuan Sing’s discretion (see section below).
Table 3: Estimated yield for holding on to Tuan Sing’s bonds
| Tuan Sing | Figures |
| Time from Settlement to Maturity (years) [A] | 0.96 years |
| Tender Price [B] | 102 |
| Coupon (%) [C] | 6.90% |
| Redemption Amount on Maturity [D] | 100 |
| Estimated Yield for Holding (%) [((D*(1 + C)/B) - 1)/A] | 4.98% |
| Source:
Tuan Sing, iFAST compilations, iFAST estimates. Data as of 17 Oct 2023. Estimated using expected settlement date of 1 Nov 2023 and maturity date of 18 Oct 2024. |
|
What should you do?
In the same SGX announcement as the tender offer, Tuan Sing also announced its intention to issue new SGD-denominated fixed-rate notes. Tuan Sing has expressed an intention to “give priority” to existing bondholders who wish to participate in both the tender offer and the new issuance. In simple terms, only investors who participate in both the tender offer and new issuance can potentially get priority to both (participating in only one of them does not give priority). Because Tuan Sing may not fully redeem the full outstanding amount, investors who participate in the tender offer are not guaranteed to have their tender accepted.
In terms of timelines, wholesale investors (those who hold full lots of SGD 250,000 nominal value each) do not need to take concrete action today as the “New Issue Pricing Date” will be most critical – likely on 23 October (Monday) (Table 4).
- If they wish to participate in the tender offer and the new issuance, they should indicate this to iFAST (or their advisors) by this New Issue Pricing Date (likely on 23 October).
- If they wish to participate in only the tender offer but not the new issuance, they can indicate this to iFAST (or their advisors) by 31 October (based on their indicative timeline).
Our Research Team will also be publishing our recommendations on this new issue when more details become available – likely on the pricing date itself.
Table 4: Indicative timeline by Tuan Sing
| Date | Event |
| 23 October 2023 | New Issue Pricing Date |
| On or following New Issue Pricing Date | New Note Allocation / Provision of Net Note Allocation Identifier |
| 31 October 2023 | Deadline for submitting Tender Application |
| 01 November 2023 | Settlement Date for Tender |
| 02 November 2023 | Issuance Date for New Issuance |
| Source: Tuan Sing, iFAST compilations. Data as of 17 Oct 2023. | |
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in TSHSP 6.900% 18Oct2024 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!