


Highlights:
- Fosun International’s cash proceeds from asset disposal ensure the Group’s liquidity and on time debt repayment. The Group already repaid more than ten onshore or offshore bonds. Its peak debt repayment period already passed.
- Fosun International’s operating performance was fair. Its annual dividend income from its subsidiaries amounted to around RMB 7 billion, which will provide the Group with a decent cash flow.
- In view of the Group having diversified business locations, diversified businesses, wider sources of financing, regular dividend income and a large number of listed companies' shareholdings and assets for sale, the Group’s default risk should be manageable. We believe that the Group will be able to repay the offshore bonds on time.
Cash Proceeds from Asset Disposal ensures Liquidity and Repayment on Time
We mentioned that Fosun International (“Fosun”) could handle the difficulty through the asset disposal in Fosun International — A Victim of Weakening Market Confidence.
Since 2022, Fosun suggested the “Weight-loss” actions (asset optmisation). This concept underpins its development strategy. The Group continued to liquidate its subsidiaries stake and assets (See Table 1), with a total of RMB 56.6 billion cash proceeds. The core asset disposal includes Nanjing Nangang, Jianlong Shares, Shanghai PANASIA Shipping Co. and Ameritrust Group. These proceeds ensure the Group’s liquidity and on time repayment of the offshore bonds (see Table 2), with a total principal amount of USD 3.48 billion.
Besides, Shanghai Forte Land, Fosun’s subsidiary (accounting for around 22% of Fosun), also successfully repaid the onshore bonds of RMB 8.9 billion in 2022 and 2023.
Table 1: Fosun International’s Asset Disposal Since the Second Half of 2022*
|
Announcement Date |
Asset Name |
Form of Disposal |
Industry |
Company's Primary Location |
Buyers |
Total Consideration |
|
Feb 24 |
Guide Investimentos SA Corretora de Valores |
Transfer |
Investment Management |
Brazil |
Banco Safra |
Undisclosed |
|
Jan 24 |
1.7 million shares of New China Life Insurance |
Public Market Sale |
Insurance |
China |
/ |
HKD 22.78 million |
|
Jan 24 |
846 million shares of BANCO COMERCIAL PORTUGUÊS (BCP) |
Public Market Sale |
Bank |
Portugal |
/ |
EUR 430 million |
|
1H23 |
Around 9% Equity Stake in Shanghai PANASIA Shipping Co. |
Transfer |
Shipping |
China |
Undisclosed |
Undisclosed |
|
May 23 |
Guangzhou Southern Headquarters Building |
Transfer |
Real Estate |
China |
China-Singapore Guangzhou Knowledge City |
Undisclosed |
|
Mar 23 |
Around 60% Stake in Nanjing Nangang |
Transfer |
Steel |
China |
CITIC Limited |
RMB 13.6 billion |
|
Jan 23 |
25.7% Equity Interest in Tianjin
Jianlong |
Transfer |
Steel |
China |
Beijing Jianlong Heavy Industry Group Co. and Camdragon Investment |
RMB 6.7 billion |
|
Jan 23 |
Ameritrust Group |
Transfer |
Insurance |
US |
Accident Fund Holdings |
USD 740 million |
|
Dec 22 |
Roc Oil Company Pty |
Transfer |
Energy |
China and Australia |
Hainan Mining Co. |
USD 163 million |
|
Dec 22 |
Lanvin Group |
IPO Public Listing |
Apparel |
Global |
/ |
Valuation at around USD 1 billion |
|
Dec 22 |
8% Equity Stake in Zhongshan Public Utilities Group Co. |
Transfer |
Public Utility |
China |
China Huarong |
RMB 770 million |
|
2H22 |
5% Equity Stake in Zhongshan Public Utilities Group Co. |
Public Market Sale |
Public Utility |
China |
/ |
RMB 230 million |
|
Dec 22 |
6% Equity Stake in Qing Dao Kutesmart |
Public Market Sale |
Apparel |
China |
/ |
RMB 150 million |
|
Nov 11 |
3% Equity Stake in Hainan Mining Co. |
Undisclosed |
Energy |
China |
/ |
RMB 400 million |
|
Oct 22 |
5% Equity Stake in Shanghai Yuyuan Tourist Mart (Group) Co. |
Transfer |
Retail |
China |
Zhejiang Qingzhan Industrial Co. |
RMB 1.25 billion |
|
Sep 22 |
26% Equity Interest in Yong An Insurance Co. |
Transfer |
Insurance |
China |
Shaanxi Finance Investment Management Co. and Shaanxi. Bond Insurance Investment Co. |
RMB 1.45 billion |
|
Sep 22 |
6% Equity Stake in COFCO Technology |
Public Market Sale |
Professional Scientific & Technical Services |
China |
/ |
RMB 460 million |
|
Sep 22 |
2% Equity Stake in Beijing Sanyuan Foods Co. |
Public Market Sale |
Livestock and Poultry Farming |
China |
/ |
RMB 124 million |
|
Sep 22 |
3% Equity Stake in Fosun Pharma |
Public Market Sale |
Pharmaceutical |
China |
/ |
RMB 3.2 billion |
|
Sep 22 |
2.2% Equity Stake in Fosun Tourism Group |
Public Market Sale |
Entertainment |
China |
/ |
HKD 240 million |
|
Sep 22 |
26.1595 million shares of New China Life Insurance |
Public Market Sale |
Insurance |
China |
/ |
HKD 447 million |
|
Jun 22 |
4.9% Equity Stake in Tsingtao Brewery |
Share Placement |
Food and Beverage |
China |
/ |
HKD 4.14 billion |
|
*Only recorded the cash proceeds from asset disposal transferable to the Fosun’s parent level Sources: Internet Sources, Bloomberg Finance L.P., Company’s Announcements, iFAST Compilations Data as of 23 February 2024 |
||||||
Table 2: Offshore Bond Repayment Record
|
Date |
Repurchase / Repayment |
Bond Name |
Principal Amount |
|
23 March 2022 |
Repayment |
FOSUNI 5.250% 23Mar2022 Corp (USD) |
Around USD 650 million |
|
20 June 2022 |
Repurchase through Tender Offer |
FOSUNI 3.300% 09Oct2022 Corp (EUR) |
Around EUR 384 million |
|
20 June 2022 |
Repurchase through Tender Offer |
FOSUNI 5.500% 17Aug2023 Corp (USD) |
Around USD 380 million |
|
17 August 2022 |
Repayment (Put Option Exercised) |
FOSUNI 5.500% 17Aug2023 Corp (USD) |
Around USD 76.89 million |
|
23 September 2022 |
Open Market Repurchase |
FOSUNI 3.300% 09Oct2022 Corp (EUR) |
Around EUR 110 million |
|
9 October 2022 |
Repayment |
FOSUNI 3.300% 09Oct2022 Corp (EUR) |
Around EUR 270 million |
|
29 January 2023 |
Repayment |
FOSUNI 5.950% 29Jan2023 Corp (USD) |
USD 450 million |
|
6 May 2023 |
Repayment |
FOSUNI 4.350% 06May2023 Corp (EUR) |
Around EUR 350 million |
|
2 July 2023 |
Repayment |
FOSUNI 6.750% 02Jul2023 Corp (USD) |
USD 700 million |
|
17 August 2023 |
Repayment |
FOSUNI 5.500% 17Aug2023 Corp (USD) |
Around USD 11.6 million |
|
Total |
Around USD 3.48 billion |
||
|
Sources: Bloomberg Finance L.P., Company’s Announcements, iFAST Compilations Data as of 9 April 2024 |
|||
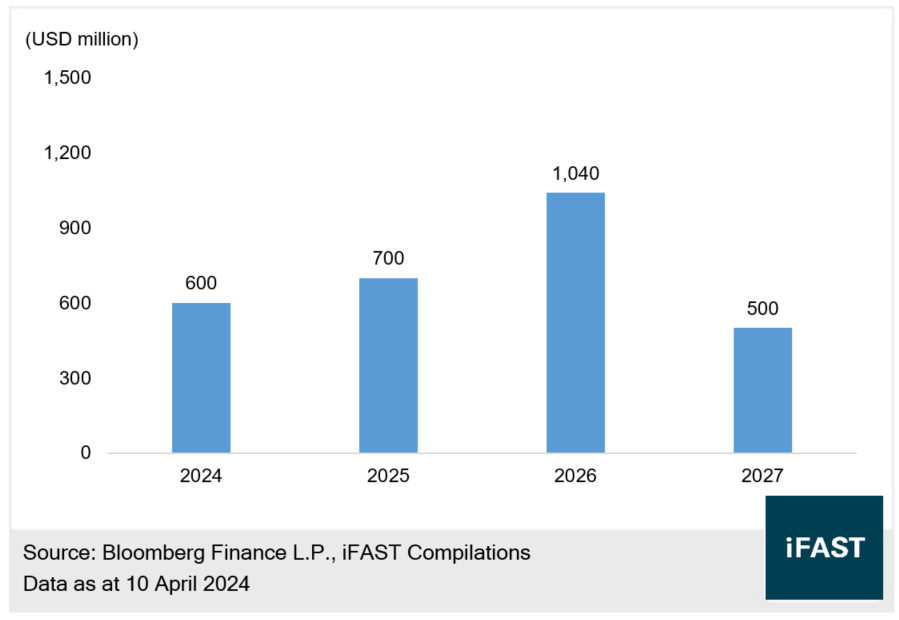
Table 3: Fosun International’s Equity Value of its Listed Subsidiaries
| Company Name | Market Capitalisation | Group’s Ownership* (%) | Equity Value (USD million) |
| Fosun Pharma | RMB 55.6 billion | 36% | 2,760 |
| Shanghai Yuyuan Tourist Mart (Group) Co. | RMB 24.6 billion | 62% | 2,100 |
| Hainan Mining Co. | RMB 14.6 billion | 46% | 920 |
| Fosun Tourism Group | HKD 4.7 billion | 78% | 460 |
| Banco Comercial Português (BCP) | EUR 4.7 billion | 20% | 1,010 |
| Beijing Sanyuan Foods Company | RMB 6.5 billion | 18% | 160 |
| Babytree Group | HKD 440 million | 30% | 2 |
| Lanvin Group | USD 220 million | 60% | 140 |
| PAREF SA | EUR 64.94 million | 59% | 4 |
| ZheJiang Wansheng Co., | RMB 5.68 billion | 30% | 230 |
| Ageas | EUR 8.02 billion | 9% | 780 |
| Total | 8,640 | ||
*Only Fosun International’s direct shareholding is counted Sources: Company Announcements, Bloomberg Finance L.P, iFAST Compilations Data as at 9 April 2024 | |||
Overall Operating Performance was Fair, with Annual Dividend Income from its Subsidiaries for Debt Repayment
In terms of operating performance, Fosun's total revenue amounted to around RMB 198.2 billion, representing a YoY increase of 8.7%. The net profit attributable to shareholders amounted to approximately RMB 1.4 billion, a turnaround from a loss to a profit, which was mainly benefited from the turnaround of the insurance business to a profit and the significant reduction of loss in the asset management business (See Table 4 for segment results). The overall operating performance was fair.
At the group level, Fosun's annual dividend income from its subsidiaries amounted to around RMB 7 billion, which will provide the Group with a decent cash flow for debt repayment.
Table 4: Fosun’s Segment Results (Based on Contribution of the Net Profit to Shareholders)
|
(RMB million) |
2023 |
2022 |
YoY |
Key Subsidiaries |
|
Health |
580 |
1,350 |
-57% |
Fosun Pharma |
|
Happiness |
-260 |
1,560 |
/ |
Shanghai Yuyuan Tourist Mart (Group) Co. Fosun Tourism Group Lanvin Group |
|
Insurance |
790 |
-2,970 |
/ |
Fidelidade Peak Reinsurance Company Limited Pramerica Fosun Life Insurance Co. |
|
Asset Management (Including Banking and Real Estate Investment) |
-550 |
-1,910 |
/ |
Hauck Aufhäuser Lampe Privatbank AG (HAL) BANCO COMERCIAL PORTUGUÊS (BCP) Shanghai Forte Land’s real estate segment |
|
Intelligent Manufacturing |
930 |
1,200 |
-22.3% |
Hainan Mining Co. ZheJiang Wansheng Co., |
|
Sources: Company Results, iFAST Compilations Data as at 31 December 2023 |
||||
With Manageable Default Risk, the Group will be able to Repay Offshore Bonds on time
As of the end 2023, Fosun’s debt in the parent level was RMB 88.8 billion, down 9.3% YoY. The “weight-loss” actions are effective to deleverage the position. At the moment, Fosun still has assets held for sale of around RMB 70 billion to RMB 80 billion and targets to lower the debt to RMB 50 billion level in the next 1-2 years.
Considering Fosun's assets located in different countries, its subsidiaries or investments being well-diversified, with about half of its revenue and assets being located outside of China. Despite being unable to issue offshore bonds, the Group has a wide range of financing channels, such as offshore or onshore bank loans, equity financing, introducing strategic investors for its subsidiaries, gradual listing of its unlisted businesses or private subsidiaries and issuance of asset-backed securities (ABS) or medium-term notes. We believe that the Group's overall default risk is manageable.
Currently, Fosun’s bonds have a yield to maturity of around 10% to 12% (see Table 4), which should price in the ripple effect and systemic risk coming from the Chinese real estate debt crisis.
In view of the Group having diversified business locations, diversified businesses, wider sources of financing, regular dividend income and a large number of listed companies' shareholdings and assets for sale, we believe that the Group will be able to repay the offshore bonds on time and resolve its debt crisis.
Table 4: Fosun’s Offshore Bonds
|
Bond Name |
Years To Maturity |
Outstanding Amount |
Ask Price (Investors Buy) |
YTM |
|
FOSUNI 6.850% 02Jul2024 Corp (USD) (Bond Express Member) |
0.2 |
USD 600 million |
99.0 |
10.2% |
| FOSUNI 5.950% 19Oct2025 Corp (USD) | 1.5 |
USD 700 million |
92.3 |
11.7% |
|
2.1 |
USD 500 million |
87.0 |
12.4% |
|
|
FOSUNI 3.950% 02Oct2026 Corp (EUR) |
2.5 |
EUR 500 million |
82.4 |
12.4% |
| FOSUNI 5.050% 27Jan2027 Corp (USD) | 2.8 |
USD 500 million |
82.5 |
12.9% |
|
Source: Bondsupermart Data as of 10 April 2024 |
||||
Last but not least, Fosun Group is also one of the "Chinese issuers with More International Background" that we have mentioned, please refer to this article for more details:
An Article about Bond Selection - Are Asian High Yields All Traps? Not Really!
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) hold a position in FOSUNI 6.850% 02Jul2024 Corp (USD) and the analyst who produced this report hold a NIL position in the abovementioned securities.










