


Highlights:
- Henderson's revenue remained stable. Although net profit declined slightly due to a high base effect last year, its robust leasing business and substantial agricultural land reserves in the New Territories provide the Group with core growth momentum for the next few decades.
- Henderson has actively reduced its debt, with net debt decreasing continuously in recent years. Borrowings from the Lee family trust and convertible bonds issued by the Group have effectively contained financial pressure and refinancing risks in a high-interest-rate environment.
- The Group's US dollar bonds maturing in 2029 have a net yield to maturity of approximately 4.7%, providing a cost-effective option for investors seeking stable returns.
Henderson Land Development Company Limited (“Henderson”), established in 1973, is one of Hong Kong’s leading property developers. Listed on the Hong Kong Stock Exchange (stock code: 12.HK), Henderson currently has a market capitalization of approximately HKD 146.4 billion and is primarily held by a family trust established by the late former chairman, Mr. Li Shau-Kee, representing approximately 72.8% of the shares.
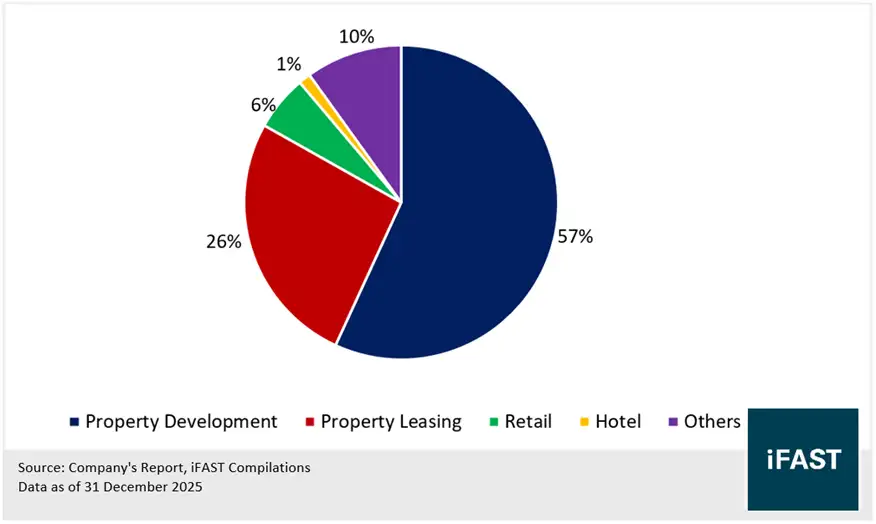
Henderson’s business is diversified, with property development (57%) and property leasing (26%) accounting for the largest share. It also includes hotel and retail businesses (Chart 1). Henderson also indirectly engages in gas supply and department store businesses through its joint ventures, Hong Kong and China Gas (stock code: 3.HK) (“Hong Kong and China Gas”) and Henderson Development (stock code: 97.HK) and holds shares in some listed companies.
Chart 1: Distribution of Henderson’s businesses
Given that the Group’s main business is still property, the following analysis will focus on property development and leasing.
Henderson is at a critical juncture in the transformation and normalisation of profit structure
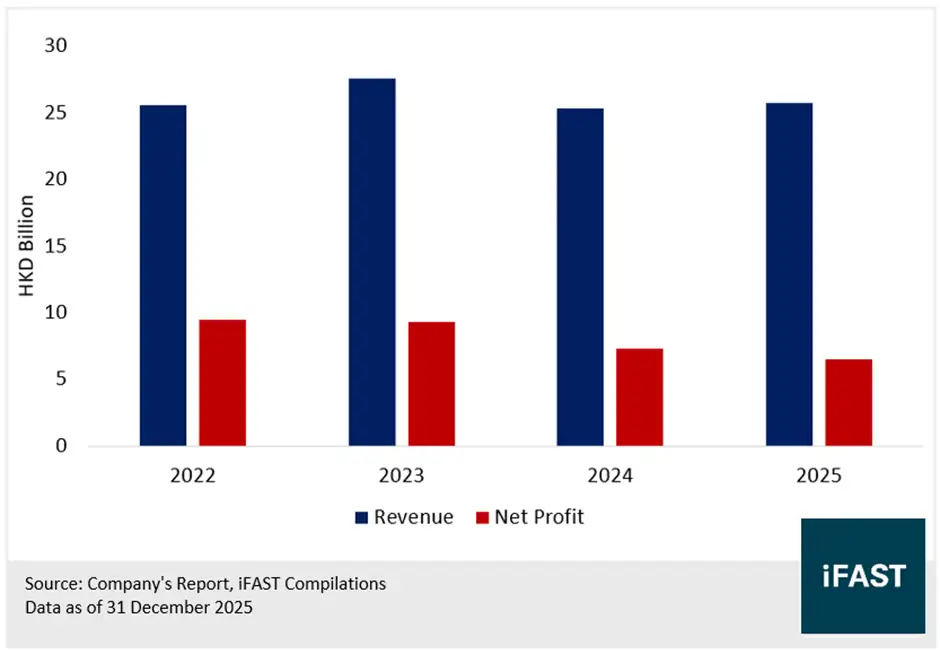
In terms of operational performance, Henderson's total revenue for the full year of 2025 was HKD 25.7 billion, showing a stable performance. Although net profit for 2025 was HKD 6.5 billion, a year-on-year decrease of 10.4% (Chart 2), this was mainly due to the high base in the same period of 2024, when the Group recorded a one-off gain of HKD 4.8 billion, including the government's repossession of land in new development areas (for infrastructure construction such as the Northern Link Rail and the Ha Tsuen New Development Area). Excluding these non-recurring factors, the operational performance of the Group’s core businesses remains resilient.
Chart 2: Henderson’s Revenue and Net Profit
Henderson's Property leasing business is performing well
Despite volatile market interest rates, Henderson's revenue from property leasing reached HKD 6.8 billion in 2025, a slight decrease of 3.4% year-on-year, with an operating profit margin of 70.5%, largely unchanged from previous years. The Group stated that its main rental properties achieved an average occupancy rate of 93% by the end of 2025, a commendable performance.
The flagship project, The Henderson, boasts an occupancy rate of 90%, with its high-quality tenant mix (such as Point 72 and Christie's) providing a stable source of income for Henderson. Several years ago, the Group acquired the prime Central Harbourfront Site 3, developing it into another large-scale commercial project, Central Yards, which has attracted significant market attention. According to the Group's disclosure, the first phase of the project is nearing completion, with the second phase scheduled for completion in 2032. The project primarily comprises office and shopping mall spaces and has already secured leasing agreements with tenants such as Jane Street, achieving an occupancy rate exceeding 70%, which is expected to generate substantial revenue for Henderson. Currently, the Group has no other projects of this scale under construction.
Encouragingly, the leased area of Jane Street and Point 72 has become the second and sixth highest in Hong Kong in 2025, respectively, indicating that the Group is preparing to convert its recent investment in project construction into actual rental income.
Property development is constrained by projects in mainland China, but recovery is expected
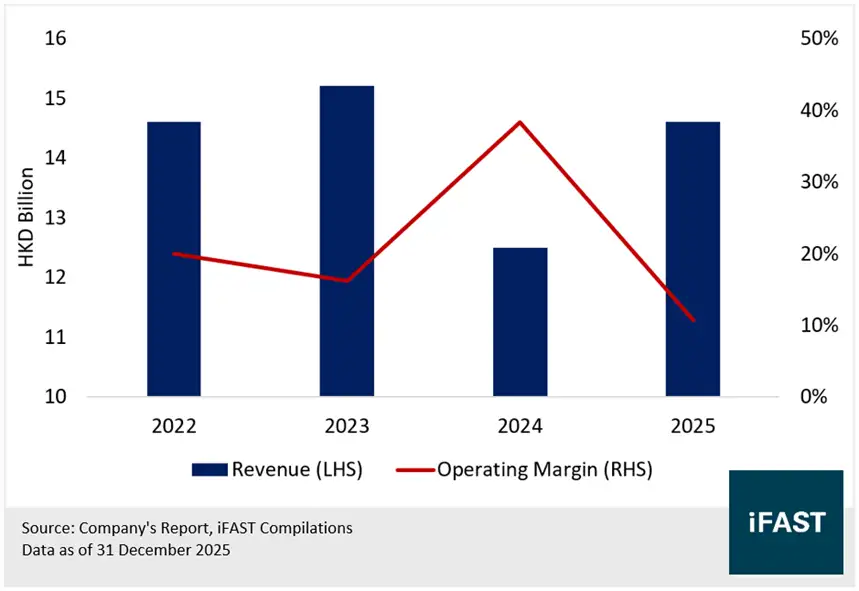
In 2025, Henderson’s property development revenue is approximately HKD 14.6 billion, a year-on-year increase of 16.8%. However, operating profit plummeted by 67.3% year-on-year to HKD 1.6 billion, with a profit margin of only 10.7% (Chart 3).
We found that the sharp drop in profit was mainly due to the large gains recorded in the same period of 2024 from the government's repossession of land in new development areas, resulting in an unusually high base in previous years. At the same time, Henderson's commercial and residential projects in Xi'an, Changsha, Guangzhou, and Beijing incurred a loss of HKD 250 million.
However, Henderson's mainland China property development projects account for less than one-tenth of the total, and the sales of new properties in Hong Kong in 2025 are quite ideal. Projects such as Eight Southpark and Square Mile in urban areas are almost sold out. With market expectations of up to 12% growth in Hong Kong property prices and the government's complete abolition of stamp duty, we expect the profitability of property development to gradually recover and return to normal growth.
Chart 3: Henderson’s Property Development Segment Revenue and Operating Margin
The Group has ample land reserves, Becoming an engine for Expansion
In addition to completed and under-construction projects, Henderson's vast agricultural land reserves are a core advantage for its long-term development. Currently, Henderson Land holds 40.5 million square feet of agricultural land in New Territories, Hong Kong, remaining the largest agricultural land holder in the city and accounting for nearly half of the Group's total land reserves (Chart 4). Notably, 90% of these agricultural land reserves are located within the "Northern Metropolitan Area" development zone. As the government continues to promote this plan, we believe the Group will have more land reclaimed in the future, thus generating more revenue.
Chart 4: Henderson Land Reserve Distributions (Million sqft.)
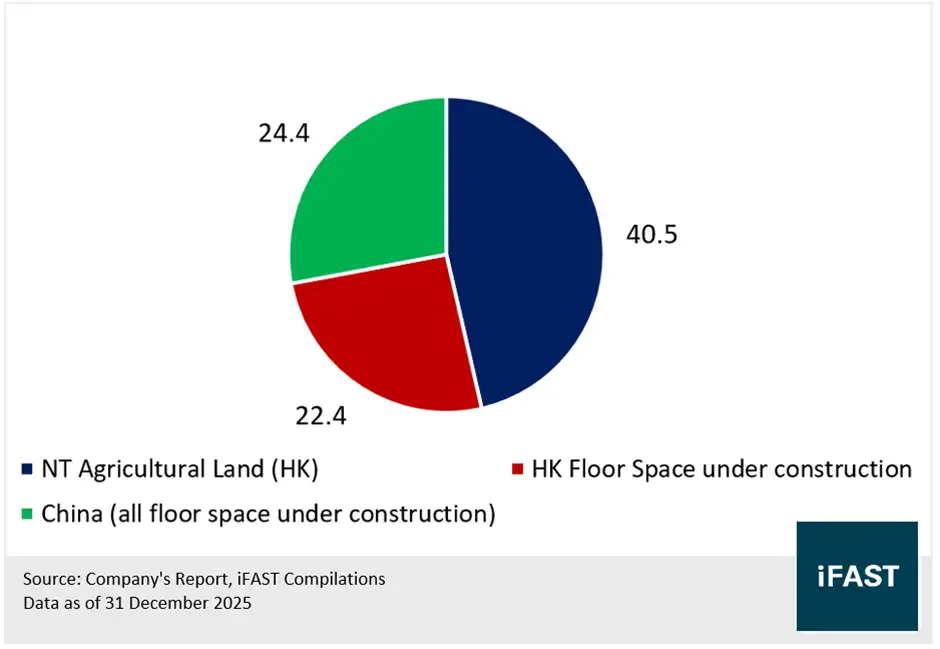
The Group also has 22.4 million square feet of floor space under construction in Hong Kong, mainly located in urban areas of Hong Kong Island and Kowloon. Based on the projected saleable floor area of 2.3 million square feet by 2026, these properties will be a significant driver of sales for at least the next few years.
Deleveraging Measures and Excellent Debt Structure Provide Stable Credit Outlook
In terms of credit and finance, Henderson demonstrated its robust and highly resilient credit quality. As of the end of 2025, the Group's net debt decreased by 11.0% year-on-year to HKD 60.2 billion, bringing its net gearing down from 21.1% in 2024 to 18.7%, a low level in the industry (Table 1). Meanwhile, Henderson Land's cash and deposits also increased by 24.0% year-on-year to HKD 22.2 billion. Although the interest coverage ratio fell to 3.0 times in 2025, the Group actively implemented debt reduction measures, including issuing HKD 8.0 billion in convertible bonds (with an annual interest rate of only 0.5%) in July 2025, to suppress debt and interest expenses, keeping overall credit risk under control.
The most unique and powerful advantage of Henderson's credit structure lies in its backing by its major shareholder. The balance sheet shows that a substantial amount of HKD 80.6 billion is owed to the Lee family trust fund, the major shareholder, for the acquisition of land related to Central Yards. These loans do not have fixed repayment periods, which can be seen as a capital buffer for the group, reducing its financial pressure and refinancing risks in an environment of rising interest rates.
Table 1: Henderson Credit Metrics
2023 | 2024 | 2025 | |
Net Debt (HKD Billion) | 73.9 | 68.0 | 60.2 |
Cash Reserve (HKD Billion) | 21.6 | 17.9 | 22.2 |
EBITDA (HKD Billion) | 8.5 | 9.0 | 6.1 |
Interest Expense (HKD Billion) | 1.3 | 1.9 | 2.0 |
Interest Coverage Ratio (x) | 6.4 | 4.8 | 3.0 |
Net Gearing (x)* | 22.6 | 21.1 | 18.4 |
*Excluding the borrowing from Li family trust fund Data Source: Company’s Report, iFAST Compilations Data as of 26 March 2026 | |||
Bond Investment
Although Henderson does not have a credit rating, given the group's good credit quality, large land bank and stable rental business, we believe investors should pay attention to its bonds maturing in 2029 (Table 2). The current net yield to maturity of the bonds is 4.7%, which has certain investment value for investors seeking a balance between risk and safety.
Table 2: USD Bond Issued by Henderson on FSMOne
Bond | Tenor | Net YTM (%) |
2.9 | 4.7 | |
Data Source: FSMOne Data as of 26 March 2026 | ||
Looking back, Henderson's bonds have performed steadily in the secondary market. Compared with the dollar bonds of blue-chip developers such as Sun Hung Kai, Henderson's USD bonds offer the most stable and attractive returns with higher credit quality, making them a better investment (Table 3).
Table 3: Comparison of USD Bonds Issued by Hong Kong Property Developers
Bond | Issuer / Guarantor | Issuer / Guarantor Credit Rating (S&P / Fitch) | Tenor | Net YTM (%) |
Sun Hung Kai | A+ / N.R. | 3.8 | 4.0 | |
New World Development | N.R. / N.R. | 3.3 | 10.1 | |
Hysan | N.R. / N.R. | 1.2 | 3.0 | |
Data Source: FSMOne Data as of 26 March 2026 | ||||
Related Risks
As Henderson's business is heavily reliant on real estate, market volatility poses a direct threat to the Group's profitability, particularly in its mainland development and asset revaluation operations.
The Group faces financial pressure from a high-interest-rate environment, especially the drain on cash flow from interest expenses. Although the Group has optimized its debt structure through loans from its major shareholder, it will still take time to improve its interest expense situation.
While the Group continues to supply office space, the structural oversupply and weak demand in both the Hong Kong and mainland office markets raise questions about whether demand can recover in the future, making a rebound in rental income more challenging.
Summary
Henderson's revenue remained stable. Although net profit declined slightly due to a high base effect last year, its robust leasing business and substantial agricultural land reserves in the New Territories provide the Group with core growth momentum for the next few decades.
Henderson has actively reduced its debt, with net debt decreasing continuously in recent years. Borrowings from the Li family trust and convertible bonds issued by the Group have effectively controlled financial pressure and refinancing risks in a high-interest-rate environment.
The Group's US dollar bonds maturing in 2029 have a net yield to maturity of approximately 4.7%, providing a cost-effective option for investors seeking stable returns.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold NIL positions in the abovementioned securities. This research report was prepared with the assistance of artificial intelligence (AI) tools. iFAST Financial Pte Ltd does not rely exclusively on AI for content generation; the content of this report – including all investment theses, ratings, price targets and conclusions – has been independently reviewed and verified by the research analyst(s) to ensure accuracy and professional integrity.


