On 2 January, Zhenro Properties (“Zhenro”) announced a restructuring plan of its offshore debts. The proposal focuses on the offshore debts and does not include onshore debts. The company said the major creditors holding about 27% of the outstanding principal of the bonds have participated in the restructuring support agreement. The deadline for participating in the restructuring support agreement is 24 January 2024.
Because of the large amount of information in the announcement, this article will consolidate the key details only, while some of them cannot be fully covered.
(The following information is for reference only and the details are subject to the original announcement.)
Operating and Debt Overview
As of June 2023, Zhenro had total debts of around RMB 60.7 billion, including offshore debts of about USD 3.9 billion. According to CRIC, in the first ten months of this year, the company’s total contracted sales were around RMB 13.7 billion, with the average monthly contracted sales of around RMB 137 million.
From 2023 to 2027, Zhenro expects its sellable resources of around RMB 110 billion to RMB 120 billion and expects to generate the unlevered free cash flows from projects of around RMB 50 billion to RMB 60 billion. During the period, the company expects to gradually sell its investment properties to boost its funds of around RMB 5 billion to RMB 8 billion.
Based on the above-mentioned debt status and projected cash flows, Zhenro has come up with the following proposed restructuring plan.
Restructuring Plan
The restructuring plan set forth in the term sheet will cover 16 offshore bonds (with principal amount of around USD 930 million). The company will be able to include other guaranteed debts in the plan at its sole discretion (if they do so, the principal amount of new bonds will be adjusted upward on a pro rata basis).
Table 1: Zhenro’s Existing Bonds
Bond Name | ISIN | Outstanding Principal Amount (USD million) | Outstanding Principal Amount and Accrued Interest* (USD million) |
ZHPRHK 5.950% 06Mar2022 Corp (USD) | XS2308085112 | 7 | 8 |
ZHPRHK 5.980% 13Apr2022 Corp (USD) | XS2329241447 | 23 | 26 |
ZHPRHK 7.125% 30Jun2022 Corp (CNH) | XS2358480155 | 1 | 2 |
ZHPRHK 8.700% 03Aug2022 Corp (USD) | XS2050860308 | 30 | 35 |
ZHPRHK 6.500% 01Sep2022 Corp (USD) | XS2383329237 | 31 | 36 |
ZHPRHK 8.000% 06Mar2023 Corp (USD) | XS2449192942 | 729 | 833 |
ZHPRHK 8.000% 06Mar2023 Corp (CNH) | XS2449193320 | 217 | 248 |
ZHPRHK 9.150% 06May2023 Corp (USD) | XS2076026983 | 300 | 364 |
ZHPRHK 8.300% 15Sep2023 Corp (USD) | XS2185842924 | 200 | 239 |
ZHPRHK 8.350% 10Mar2024 Corp (USD) | XS2152219973 | 200 | 239 |
ZHPRHK 7.875% 14Apr2024 Corp (USD) | XS2099413093 | 290 | 341 |
ZHPRHK 7.100% 10Sep2024 Corp (USD) | XS2346158822 | 340 | 396 |
ZHPRHK 7.350% 05Feb2025 Corp (USD) | XS2226898216 | 350 | 399 |
ZHPRHK 6.630% 07Jan2026 Corp (USD) | XS2279711779 | 400 | 453 |
ZHPRHK 6.700% 04Aug2026 Corp (USD) | XS2293750670 | 300 | 339 |
ZHPRHK 14.724% Perpetual Corp (USD) | XS2013512608 | 200 | 240 |
Total | 3,620 | 4,200 | |
*Estimated amount Sources: Company’s Announcements, Bloomberg Finance L.P., iFAST compilations Data as of 2 January 2024 | |||
The bondholders who vote for the scheme will receive a consent fee of 0.15% of the bond's face value (paid in cash) and a share of an additional USD 95 million of Zhenro’s New Bond Tranche A (see Table 2).
As it is not an exchange offer but a restructuring plan through the courts, it should be binding on all bondholders if the scheme is passed. The company expects the restructuring plan to be effective not late than 30 June 2024.
According to the bondholders’ claim amount (equal to the sum of Outstanding Principal Amount and Accrued / Defaulted Interest), they will receive four new bonds with different tenors (see Table 2):
Table 2: Details of Four New Bonds
New Bond | Issue Size (million USD) | Coupon Rate | Maturity Date (Tenor) | For every $100 of claim amount, holders will receive |
Tranche A | 237 | 5% (Paid in Cash) / 6% (Paid in Kind) | 4 years | $5.6 principal amount* ($3.36 principal amount if excluding the consent fee) |
Tranche B | 853 | 5% (Paid in Cash) / 6% (Paid in Kind) | 5 years | $20.15 principal amount |
Tranche C | 1,279 | 5.5% (Paid in Cash) / 6.5% (Paid in Kind) | 6 years | $30.22 principal amount |
Tranche D | 1,863 | 6% (Paid in Cash) / 7% (Paid in Kind) | 7 years | $44.04 principal amount |
*Included consent fee and assumed all bondholders agree with the proposal Sources: Company’s Announcements, iFAST compilations Data as of 2 January 2024 | ||||
The details of New Bonds are listed below:
The company could pay the coupon in cash or in kind in the first three years.
In the second half of the second year, at least 0.5% principal amount of the coupon shall be paid in cash. In the third year, at least 3% principal amount of the coupon (1.5% principal amount in the first half and second half respectively) shall be paid in cash. If the total contracted sales in the last 12 months before the coupon payment date reach RMB 35.0 billion, then the minimum cash payment amount will be double.
- For every following year, all coupon shall be paid in cash.
- The cash coupon has 90-day grace period.
- The company has the right to call the bonds before the maturity date with the principal amount plus accrued interest. The priority will be based on the tenor of the new bonds.
- The issuer could further amend key clauses, such as waivers of defaults, coupon rates and/or the maturity date if over 75% of bondholders accept the amendment (“consent solicitation”).
- The credit enhancements could refer to Table 3, Mandatory Redemption Events. Upon the occurrence of the mandatory redemption events, the company should redeem the new notes using the partial or all proceeds.
Table 3: Mandatory Redemption Events
Mandatory Redemption Events | Redemption Amount | Redemption Methods |
Specified Asset Disposal (The list is yet to be disclosed) | 75% of the net consideration derived from such Specified Asset Disposal | Within 45 business days, the company has to redeem the new bonds (the priority will be based on the tenor), by either repurchasing the new bonds through open-market tender offer or reverse Dutch auction, or exercising the call option to redeem the bond with the principal amount plus accrued interest. |
Receivables Repayment | 100% of the net proceeds of receivables | |
New Project Sale | 20% of the net consideration derived from such New Project Sale | |
Sources: Company’s Announcements, iFAST compilations Data as of 2 January 2024 | ||
Short Commentary on Restructuring Plan
Zhenro’s restructuring plan is simple and straight-forward. It only involves debt maturity extension and no haircut on the bonds (2% principal haircut if excluding the consent fee). The restructuring method is quite different from others’ defaulted developers.
We believe that the plan could give the time to the company, in order to resume project operations, property sales and gradually dispose of assets on hand at a better price in a few years, so that the company could gradually repay the offshore debts.
Under the poor sentiment in the Chinese real estate industry, the company has greater chances that it cannot reach the target about cash flows from sales. Especially, the company has to pay the coupon in cash and repay a large amount of principal in the fifth year. This puts greater pressure on its cash flow. It also means that the company might default again, or might use consent solicitation to delay principal payments or cash interest payments. As such, it is unlikely that investors will be able to recover their principal as expected.
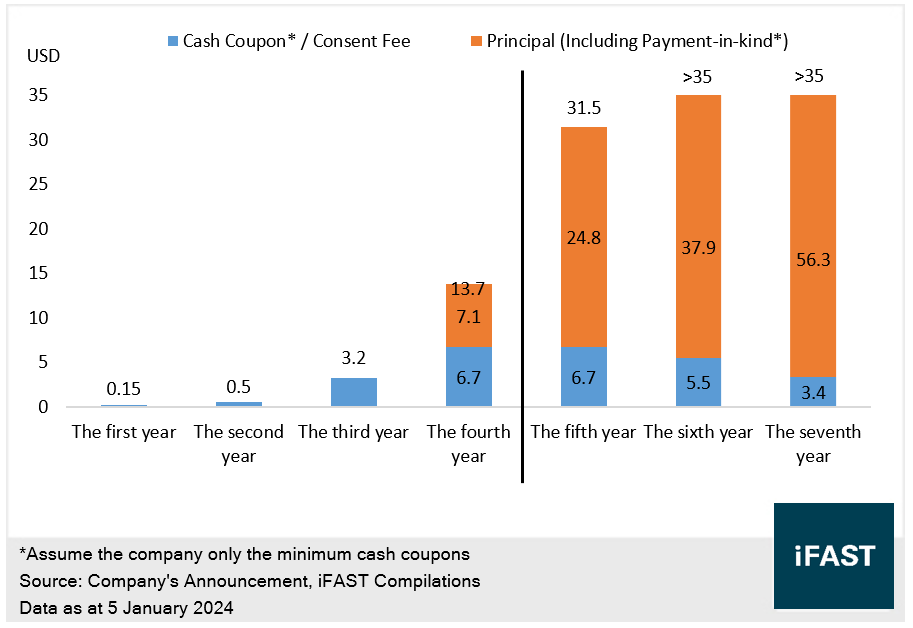
However, if Zhenro successfully makes repayment in the first four years, the bondholders will be able to get back about 18% of the principal (see Chart 1), which is already much higher than the bond price and the liquidation value. Therefore, we believe that accepting the plan will be a better option.
Chart 1: Given Zhenro’s Successful Repayment, For Every $100 of Claim Amount, the Cash Amount Received by Holders
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.