Important Events
Last Thursday, the European Central Bank (“ECB”) maintained rates on the main refinancing operations, marginal lending facility and deposit facility at 0.00%, 0.25% and -0.50% respectively. The ECB will continue net asset purchases under the pandemic emergency purchase program (“PEPP”) at least until the end of March 2022. As a matter of fact, purchases under the PEPP for the next quarter is expected to be much higher than the pace in the first few months of this year. Meanwhile, banks may still access the targeted longer-term refinancing operations (TLTRO III) as a source of funding in order to continue lending to households and companies.
Real GDP in the euro area declined by 0.7 percent in the fourth quarter after staging a strong rebound in the third quarter. Economic surveys and high frequency data suggest that the euro economy is likely to contract in the first quarter of 2021. In spite of the fiscal support to household and companies, consumer spending remained depressed in view of the pandemic and weak employment outlook. Generally speaking, the economic uncertainty has coincided with weaker corporate balance sheets and subdued business capital expenditures.
Last week, the Bank of Canada held the overnight rate target at 0.25%, and kept the Bank Rate at 0.5% and deposit rate at 0.25% respectively. Purchases under its Quantitative Easing program will be maintained at its pace of at least CAD 4 billion per week. The central bank expects to hold interest rates at its current level until the 2 percent inflation target is reached, which will happen in 2023.
The Canadian economy is recovering at a better than expected pace. GDP expanded by 9.6% in the final quarter of 2020 and the central bank has upgraded its outlook for the first quarter of 2021. Housing market activity has been much stronger than expected and consumers have started to adapt to containment measures. In addition, export demand has improved on the back of higher commodity prices and business investments have increased.
Asian High Yield Bond Index
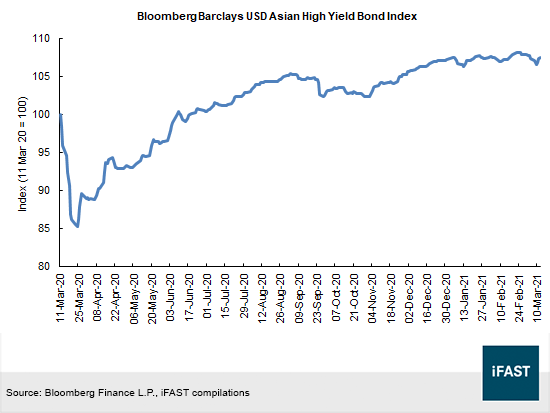
Last week, the Bloomberg Barclays USD Asian High Yield (“HY”) Bond Index gained 0.1% with modest movements in the underlying benchmark constituents.
After posting a series of losses in recent weeks, Sri Lankan government bonds were among the top gainers in the index. The SRILAN 5.750% 18Jan2022 Govt (USD) was up by more than 4% while the SRILAN 5.750% 18Apr2023 Govt (USD) climbed by 2%. The price improvements came as China approved a USD 1.5 billion currency swap line with the country. Sri Lanka had been in talks with foreign trading partners on debt financings.
In the meantime, Asian high yield bonds experienced a heavy risk-off sentiment this week. There was intense selling in Chinese highly leveraged HY names. The yield level of B-graded real estate bonds have spiked up to the same level in June 2020. Almost every B and BB-graded bond witnessed an increase in yield over the last two weeks, mainly because of the fear of tightening controls in the housing market and the aftermath of the China Fortune Land event.
The price of bonds issued by China's LGFV was also down significantly, as local governments felt the strain on public finances as fiscal support dialled down. The recent Chongqing Energy's default has flagged provincial risks, while the central government signalled in 'Two Sessions' that it will not bail out local governments for their own debt problem.
On Tuesday, China Aoyuan signed agreements for secured dual-currency term loan facilities of HKD 1.6 billion and USD 20 million. Previously the company announced that the contracted sales in February was up 305% YoY to CNY 18.0 billion.
On Wednesday, Country Garden proposed to offer up to CNY 2 billion five-year corporate bonds to repay existing debts. The company's attributable contracted sales in February was up 123% YoY to CNY 46.6 billion.
Interest Rates and Currencies
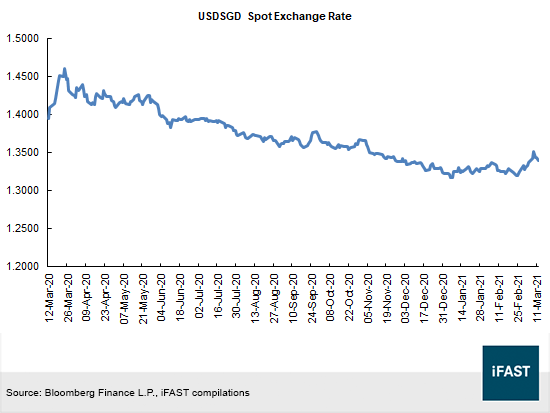
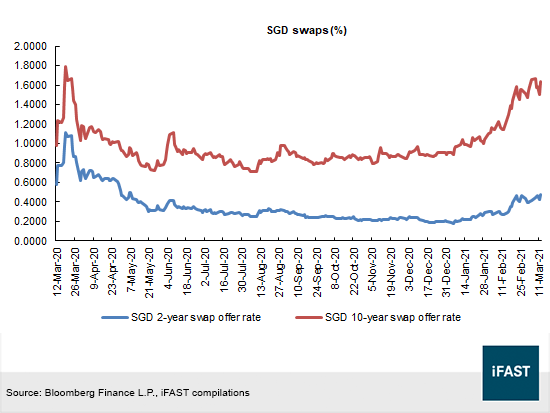
The US dollar strengthened by 0.2% against the Singapore dollar last week. The USD/SGD pair ended the week nearly unchanged at 1.3395. Singapore swap offer rates steepened at the short end. The two-year SGD Swap Offer Rate (“SOR”) increased by 7bps to 0.4800% but the ten-year SOR dropped by 2bps to 1.6350%.
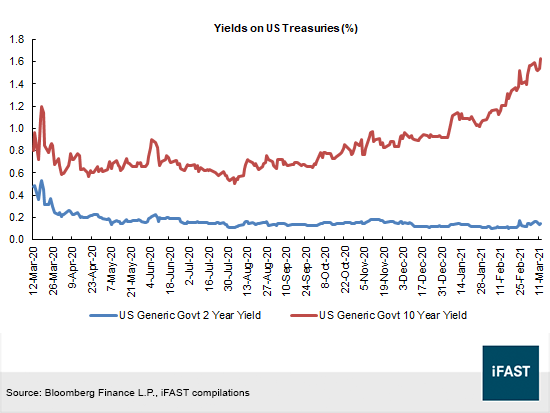
The Treasury market continued to slide last week especially at the longer end of the curve. The two-year US Treasury yield increased 1bps to 0.1470% and the ten-year Treasury yield climbed by 6bps to 1.6247%. Overall, the ten-year Treasury yield had risen to its highest level since February 2020.
US consumer prices increased 0.4% in February and 0.3% in January. However, core CPI, which excludes food and energy prices, only expanded by 0.1%. According to the OECD, the United States coronavirus aid package will add approximately one percentage point to global economic growth in 2021. The OECD also increased its economic growth forecast for America from 3.2% to 6.5%.
Corporate Updates and New Issues
The manager of ESR-REIT informed the exchange last Monday that it has obtained a SGD 320m unsecured loan facility with various lenders. Proceeds from the facilities will be used to refinance existing indebtedness, asset enhancement initiatives and other general working capital purposes. Made up of two tranches, the final maturity for the SGD 160m term loan facility will be 60 months from its first utilization date while the maturity date for the SGD 160m revolving loan facility will be 48 months from its first utilization date.
On Monday, Astrea VI Pte Ltd priced three tranches of bonds that are backed by cash flows from private equity funds. Class A-1 SGD notes were priced at 3%, tightening from its initial price guidance (“IPG”) of 3.25%. Concurrently, Class A-2 USD and Class B USD notes were priced at 3.25% (IPG: 3.625%) and 4.35% (IPG: 4.65%) respectively.
Oxley Holding Limited announced on Tuesday that it had purchased USD 12,048,000 in principal of the OHLSP 6.375% 21Apr2021 Corp (USD) for a consideration of USD 11,870,324. The notes were issued under the USD 1 billion guaranteed Euro Medium Term Note Programme established on 7 Apr 17.
On Tuesday, Hatten Land Limited informed the Singapore Exchange that Mr Chong Heng Loong has ceased to be the company’s Chief Financial Officer with effect from 24 Mar 21. Mr Chong was in charge of all of Hatten Land’s financial activities including capital management and investor relations. In the interim, the Board has approved Ms Tammy Tam as Financial Controller of the company.
Mapletree Logistics Trust Management (“MLTM”) notified the exchange that two of MLT’s subsidiaries have entered into a green loan facility agreement. Under the terms of the loan facility, a mandatory prepayment is required if Mapletree Logistics Trust Management is no longer the manager of MLT, or if MLTM is no longer majority owned or a wholly-owned subsidiary of Mapletree Investments Pte Ltd.
Last Tuesday, Yanlord Land Group Limited uploaded a notification from Moody’s Investors Service, informing that the credit rating agency had changed its outlook on the company from negative to stable, while keeping its Ba2 corporate family rating and Ba3 senior unsecured rating on the bonds issued by Yanlord Land (HK) Co., Limited. Moody’s cited the Yanlord’s healthy liquidity position and expects the group’s ratio of revenue to adjusted debt to increase to 65%-72% over the following 12-18 months.
Last Thursday, Aspial Corporation Limited (“Aspial”) made an announcement to acquire its remaining shares in World Class Global Limited (“WCG”) by way of a scheme of arrangement. World Class Global Limited is an 81.1% subsidiary of the company involved primarily in the property development business in Australia and Malaysia. Under the scheme, Aspial will pay SGD 0.21 for each WCG share, which will be satisfied though the issuance of new Aspial shares at an issue price of SGD 0.19.
However, the scheme is subject to shareholder approval and is part of a restructuring exercise to delist WCG from the exchange. After the scheme becomes effective, Aspial could re-deploy the fixed assets of WCG and introduce major changes to the company. To illustrate the pro-forma financial effects of the proposed acquisition, the net tangible asset per share for Aspial, had the transaction been completed on 31 Dec 20 would fall from SGD 18.86 per share to SGD 18.27 per share.
Last Friday, City Developments Limited launched a 5-year senior SGD bond at an initial price guidance of 2.3%, which represented a credit spread of 130bps over the 5-year SOR. The issue size of the bond is SGD 235m and will be issued on 23 Mar 21.
In a clarification statement to the exchange, City Development Limited stated that it has a joint controlling equity stake in the Sincere Property Group and not a controlling shareholder in the Chinese developer. Both companies are joint shareholders of Sincere Property Holding Limited - a joint venture firm controlled by founders of Sincere Property Group. CDL has been working with Deloitte China to improve the liquidity of the joint venture firm but progress has been slow. The group has been trying to restructure the debt and CDL has recognized an impairment loss of SGD 1.78 billion on its investment in Sincere Property. The impairment charge is the largest contributing factor to its worst financial performance in its operating history.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!