


Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Highlights:
- Road King's contracted sales slumped by over 34% in 2023, and underperformed the industry average. The continuous default cases of Chinese real estate led to a massive impairment loss on receivables and amounts due from joint ventures, and dropping house prices triggered an inventory write-down for the first time, resulting in a struggling performance.
- Amid a depressed market sentiment, Road King’s credit metrics deteriorated significantly, with liquidity approaching distress.
- In view of the fact that the "Estimated Material Date" of MORI, the property project Road King is developing, lies on or around 30 June 2024. It is expected that the balance payment of sold projects (assuming that 90% is received for the delivery of the property by using the " Stage Payment Plan”), together with the cash flow generated from sales of toll roads in China and sales of the Southland project, will be sufficient to repay the USD bond due in September this year.
- The regular interest payment of perpetual bonds indicates a high willingness to repay the bonds, but it is believed that the company will not redeem a perpetual bond in November this year. The ability to make regular interest payments is an important indicator in determining a company's liquidity.
- Regarding the longer-term bonds, if the sales performance remains sluggish, even under the optimistic financing environment, the likelihood of default on bonds is significant.
Sales Underperformed the Average, with Massive Asset Impairment Losses
As the demand for housing continues to be depressed, Road King cut prices to stimulate sales, with the average selling price reducing from RMB 24,000 per square meter in 2022 to RMB 21,000 in 2023, but the full-year contracted sales further crashed by 34.2% from one year ago to RMB 27.7 billion, which underperformed average of Top 100 developers (-16.5%).
Chart 1: Road King’s Contracted Sales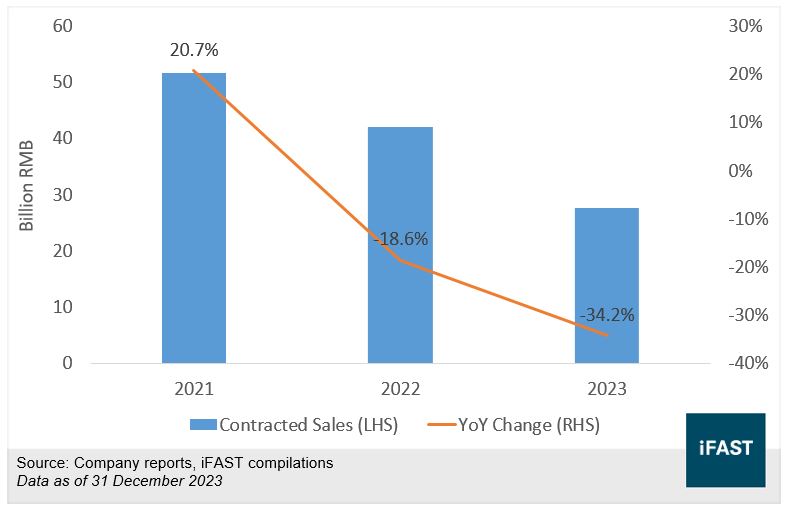 Diving into the revenue, due to the
impacts of price reduction, the gross margin slipped to 2%. It is noteworthy
that the price cuts also drove the fair value of inventories below the carrying
value on the balance sheet, the company thus recorded the first inventory
impairment of HKD 890 million in 2023, and the adjusted gross margin amounted
to -5% if taking into account the inventory impairment.
Speaking of asset impairment, aside from the inventory impairment, Road King reported a massive impairment loss on receivables and amounts due from joint ventures, which totaled HKD 1.3 billion in 2023, far beyond the level of 2022 (Table 1). We believe that these impairment losses are principally associated with the downturn of CRE whereby joint ventures experienced difficulty in operating, rendering it challenging for Road King to collect the related receivables.
Table 1: Asset Impairment Loss
|
(Million HKD) |
2022 |
2023 |
|
Impairment Loss on Receivables |
300.0 |
700.0 |
|
Impairment Loss on Amounts Due from Joint Ventures |
0.0 |
610.0 |
|
Inventory Impairment |
0.0 |
890.0 |
|
Sources: Company’s reports, iFAST compilations Data as of 31 December 2023 |
||
Owing to unfavorable factors such as gross margin decline and asset impairments, Road King delivered poor results as expected, with a net loss of HKD 3.8 billion, in contrast to a net profit of HKD 460 million in 2022.
Toll Road: Farewell to China, Indonesia is the Next Major Market
Looking into the toll road sector, Road King owns toll collection rights for five expressways in China. in 2023, following the cancellation of Pandemic prevention and control, the average daily traffic volume gained by 20%, but surprisingly, the revenue from toll roads saw a 13% decrease YoY to RMB 2.3 billion. We think the core reason for the large deviation between traffic volume and toll revenue is mainly due to the economic slowdown, which led to a decrease in the traffic volume of trucks, the key contributor to toll revenue. By contrast, the company's four toll roads in Indonesia performed well, with toll revenue reaching RMB 1.5 billion in 2023, a 58% year-on-year surge.
In light of the poor outlook for toll roads in China, Road King entered into an agreement with China Merchants Expressway Network & Technology Holdings Co Ltd (001965. SZ) to sell all of its interests in expressways in China to the latter at a price of RMB 4.4 billion. The sale has been approved at the general meeting and is expected to be completed in 1H2024. Upon completion of the transaction, Road King will part with the toll road business in China and shift its focus to Indonesia. Based on the robust results of Indonesian business, we are confident that the company's toll road sector will continue to have good growth potential.
Credit Quality Deteriorated with Tight Liquidity
In terms of credit metrics, Road King’s net gearing ratio stood at 64% ending 31 December 2023, a 10 percentage points drop from one year ago, while the adjusted number would soar to 119% if we reclassify three perpetual bonds from equity into debt, suggesting that the company is highly leveraged.
Surely, liquidity is the most important credit indicator in the current environment. As of 31 December 2023, the total debt of Road King amounted to HKD 22.6 billion, down 30% YoY, with both short-term and long-term debt declining to varying degrees. However, we attribute the decrease of debt to a greater difficulty in fundraising, instead of an active deleverage by the company. Meanwhile, after repaying a total of HKD 11.1 billion of debt last year, the cash and cash equivalents plunged by 33.7% to HKD 5.5 billion, leading to a cash-to-short-term debt ratio of 0.6x, indicating that the company's liquidity is in a more precarious position, and it would be impossible to meet the requirement for repayment of the maturing debt if without external refinancing.
Table 2: Credit Indicators of Road King
|
(Billion HKD) |
2022 |
2023 |
YoY Change |
|
Short-term Debt |
10.3 |
9.9 |
-3.9% |
|
Long-term Debt |
21.9 |
12.8 |
-41.8% |
|
Total Debt |
32.2 |
22.6 |
-29.7% |
|
Cash and Cash Equivalents |
8.3 |
5.5 |
-33.7% |
|
Cash to Short-term Debt Ratio |
0.8 |
0.6 |
-31.0% |
|
Net Gearing Ratio |
72.9% |
63.0% |
-9.9 percentage points |
|
Adjusted Net Gearing Ratio |
119.6% |
119.0% |
-0.6percentage points |
|
Sources: Company’s reports, iFAST compilations Data as of 31 December 2023 |
|||
Our Thoughts on Outstanding USD Bonds
As a result of tight liquidity, the company's solvency will inevitably weaken, and it is believed that creditors should be very concerned about whether Road Kong could be able to repay bonds and what measures to take for the current holding of USD bonds. Here are some of our views.
1. Bond due in September 2024 is expected to be repaid as scheduled
Based on the funding gap, the company needs additional funding of HKD 4.4 billion to repay short-term debt. Considering that Road King's debt is mainly made up of USD bonds as well as offshore syndicated bank loans, which could be renewed easily, we thus prioritize our analysis on the company's USD bonds.
From Table 3, we can see that the total amount of offshore bonds the company should pay within this year hit USD 540 million (about HKD 4.2 billion). The biggest challenge is the payment of USD 372 million in principal and interest to "ROADKG 6.700% 30Sep2024 Corp (USD)" on 30 Sep. Although the company owns a cash balance of over HKD 5 billion, which is enough to cover the payment, the company has to reserve funds for internal operations and other types of payments, making it impossible to use all of the cash to repay the USD bond. It suggests that the company needs additional cash flow to support the bond repayment.
Table 3: Payment Schedule on Bond Principal and Interest During This Year
|
Date |
Principal or Interest |
Amount (Million USD) |
|
12-Jan |
Interest |
13 |
|
16-Jan |
Interest |
13 |
|
17-Feb |
Interest |
12 |
|
4-Mar |
Interest |
9 |
|
5-Mar |
Interest |
7 |
|
30-Mar |
Interest |
12 |
|
18-May |
Interest |
12 |
|
23-Jun |
Interest |
11 |
|
12-Jul |
Interest |
13 |
|
16-Jul |
Interest |
13 |
|
17-Aug |
Interest |
12 |
|
4-Sep |
Interest |
9 |
|
5-Sep |
Interest |
7 |
|
30-Sep |
Principal and Interest |
372 |
|
18-Nov |
Interest |
12 |
|
23-Dec |
Interest |
11 |
|
Total |
536 (around HKD 4.2 billion*) |
|
|
Sources: Company’s reports, iFAST compilations Data as of 31 December 2023 *HKD/USD: 7.8 |
||
Mercifully, the company will certainly have some cash inflow in recent, including the sales of China's toll road business and collection of balance payment of MORI, a Hong Kong-based property project owned by Road King, after the "Estimated Material Date" around 30 June 2024, as well as cash collection of sales of Road King’s Southland project.
Specifically, the sale of China's toll road business is expected to generate an after-tax cash flow of about HKD 4.9 billion (Table 4), leaving a net proceeds of HKD 4.0 billion after deducting the project loan of HKD 830 million. According to the company's planning, Road King expects to apply 80% to 90% of the remainder to repay debt, translating into a cash inflow of HKD 3.2 billion to HKD 3.6 billion. Regarding the Mori project, 45 units have been sold since the commencement of pre-sale in 4Q2023, totaling contracted sales of over HKD 210 million, and the company is expected to collect a balance payment of roughly HKD 200 million around "Estimated Material Date" (assuming that 90% is received for the delivery of the property by using the " Stage Payment Plan". For more information, please refer to our research article “Bond Focus: After Scrapping All Tightening Measures, Can it Save HK Developers?”), and based on the 50% stake Road King owns in that project, the company is anticipated to collect a cash flow of HKD 100 million. Furthermore, with Hong Kong scrapping all tightening measures for the real estate market, the sentiments improved a lot, bolstering the sell-through rate of Road King’s Southland project, which sold 74 units since scrapping all tightening measures of Hong Kong real estate market. From centaline’s transaction records, the average selling price of each unit was around HKD 12.9 million, meaning that the estimated total contracted sales could reach HKD 970 million, and equity contracted sales would amount to HKD 490 million based on Road King’s stake of 50% in that project. Taking into account that MTR Corporation will receive 35% of the profit from this project, we assume that Road King could be able to convert 70% of equity contracted sales into cash flow, which hit HKD 340 million.
All in all, despite the recent drop in the price of bond due in September this year, which are currently trading at around $65, reflecting the market's skepticism about the company's capability of repaying the bond. However, we believe that the incremental cash flow of nearly HKD 4.0 billion could almost fulfill the requirement for repaying USD bonds and the company will not face much challenge in repaying this bond as scheduled, particularly, when we consider the availability of funding the company has.
Table 4: Anticipated Cash Flow
|
Anticipated Cash Flow (Million HKD) |
Remark |
|
|
Sales of China's Toll Road Business |
3,180-3,570 |
After-tax cash flow of about HKD 4.9 billion, leaving a net proceeds of HKD 4.0 billion after deducting the project loan of HKD 830 million. Road King expects to apply 80% to 90% of the remainder to repay debt |
|
Sales of Hong Kong's Southland project |
Around 340 |
50% stake Road King owns in that project, , 74 units have been sold after scrapping all tightening measures for the real estate market |
|
Collection of Balance Payment of MORI Project |
Around 100 |
50% stake Road King owns in that project, , 45 units have been sold with total contracted sales of HKD 210 million |
|
Sources: Company’s reports and
Centaline Property Agency, iFAST compilations |
||
2. It is expected that the company will not redeem a perpetual bond in November. The ability to make regular interest payments is an important indicator in determining a company's liquidity.
Looking into perpetual bonds, there are three outstanding perpetual bonds issued by Road King, and all of them are currently trading at roughly $20. We see that, in the midst of the industry downturn, Road King is one of the few Chinese property developers that can make interest payments of perpetual bonds, reflecting its high willingness to repay debt. it is important to take note that suspending interest payments of perpetual bonds will not trigger a default event, but we are of the view that the ability to make regular interest payments is an important indicator in determining a company's liquidity. That said, if Road King stops making interest payments in the future, as happened with other defaulted Chinese property developers, it is likely to be an early sign of liquidity distress.
It is worth noting that ROADKG 7.950% Perpetual Corp (USD) and ROADKG 7.000% Perpetual Corp (USD) are not embedded with coupon set-up clauses. It means even though Road King does not redeem the bonds, the coupon rate will remain unchanged. In the current market environment, it is more likely that Road King would not redeem the perpetual bonds. ROADKG 7.750% Perpetual Corp (USD) is embedded with coupon set-up clauses, and the new coupon will be adjusted to the 5-year US Treasury yield +6.003%, which would be 10.2%, based on the current treasury yield. Under the current environment, 10.2% is not a very high financing cost and it is expected that the company will not redeem this perpetual bond either.
3. High uncertainty in payment of longer-tenor bonds
Apart from three perpetual bonds, Road King also has two USD bonds maturing in 2025 and 2026 respectively, with an aggregated amount of USD 1.5 billion (Table 5). If the market sentiments remain depressed, it is unlikely that the company could have ample liquidity to cover such a large amount of debt, regardless of the decent performance of the toll road sector. Therefore, we are convinced that the uncertainty of payment of long-term bonds is significant, and we do not rule out the possibility of a rollover of maturity or debt restructuring.
Table 5: USD Bonds
|
Bond |
Maturity Date |
Outstanding Amount (Million USD) |
Price |
|
ROADKG 5.900% 05Mar2025 Corp (USD) |
Mar-25 |
220 |
54 |
|
ROADKG 6.000% 04Sep2025 Corp (USD) |
Sep-25 |
300 |
42.8 |
|
ROADKG 5.200% 12Jan2026 Corp (USD) |
Jan-26 |
500 |
29.2 |
|
ROADKG 5.125% 26Jul2026 Corp (USD) |
Jul-26 |
500 |
26.3 |
|
Sources: Bloomberg, iFAST compilations Data as of 26 March 2024 |
|||
Conclusion
Road King's contracted sales slumped by over 34% in 2023, and underperformed the industry average. The continuous default cases of Chinese real estate led to a massive impairment loss on receivables and amounts due from joint ventures, and dropping house prices triggered an inventory write-down for the first time, resulting in a struggling performance.
Amid a depressed market sentiment, Road King’s credit metrics deteriorated significantly, with liquidity approaching distress.
In view of the fact that the "Estimated Material Date" of MORI, the property project Road King is developing, lies on or around 30 June 2024. It is expected that the balance payment of sold projects (assuming that 90% is received for the delivery of the property by using the " Stage Payment Plan"), together with the cash flow generated from sales of toll roads in China and sales of the Southland project, will be sufficient to repay the USD bond due in September this year.
The regular interest payment of perpetual bonds indicates a high willingness to repay the bonds, but it is believed that the company will not redeem a perpetual bond in November this year. The ability to make regular interest payments is an important indicator in determining a company's liquidity.
Regarding the longer-term bonds, if the sales performance remains sluggish, even under the optimistic financing environment, the likelihood of default on bonds is significant.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!










