


Note: This is an edited version of an article published earlier by our affiliates on 12 Mar 20.
Introduction
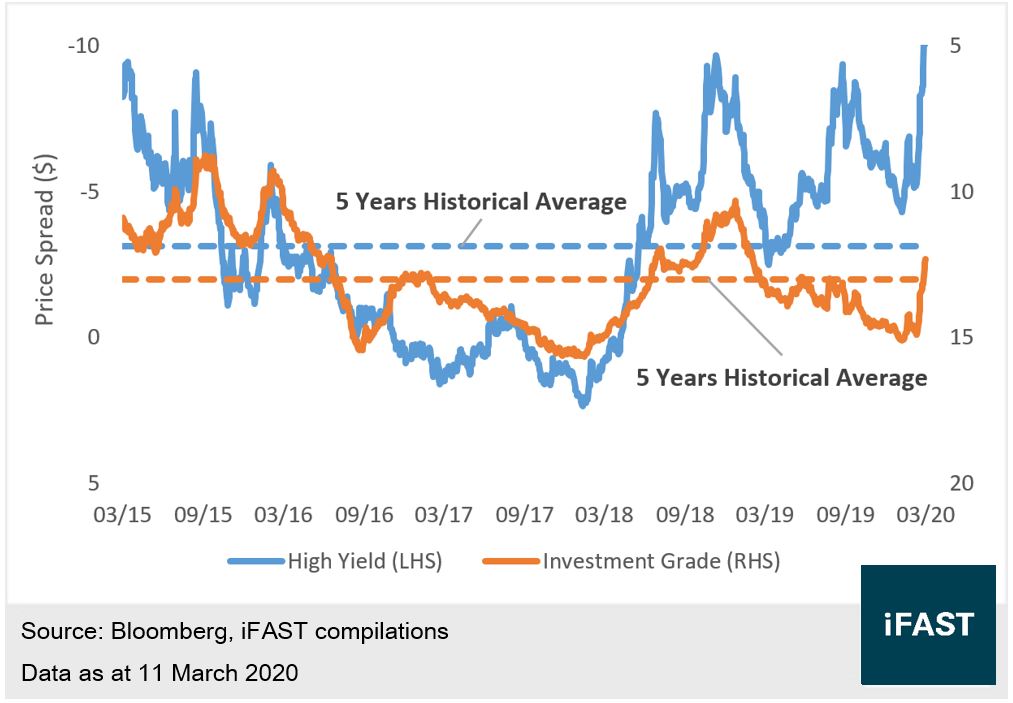
The recent situation has seen global stock markets fluctuating and the US Treasury yields plummeting, resulting in a significantly widened yield spread. Chinese real estate high yield bonds have also found themselves in the same situation (see Figure 1).
Figure 1: IBOXX Chinese Real Estate Bond Inverted Price Spread (vs. 3-5Y US Treasury)
Previously in “A Full Analysis: How Much Will the Coronavirus Affect Mainland Property Developers?”, we mentioned that investors who are fearful of the continued spread of the pandemic can consider BB grade issuers of which yields have increased. For these issuers, their short term repayment pressure is more manageable than that of B grade issuers (see Table 1).
Table 1: Cash to Short Term Debt Ratio of Mainstream Chinese Developers
BB Grade | B Grade | |
Average (times) | 1.83 | 1.08 |
Median (times) | 1.73 | 0.97 |
Source: Bloomberg, iFAST Compilations Data as at 30 June 2019 | ||
We have selected some BB grade issuers for investors to easily screen their preferred issuers and bonds.
(All sales figures are taken from CRIC, while the net gearing and cash to short term debt ratio are taken from interim reports.)
Highlighted BB Grade Issuers
1. KWG Group
Short Commentary on Issuer:
KWG is a second-tier developer in China with a YoY growth of 31.5% for total contracted sales in 2019. Given that the Group has a large land reserve with most of the property projects located in first and second-tier cities, it will have a comparative advantage during the outbreak.
The Group has a net gearing of 92% and a cash to short term debt ratio of 4.4x, which is a sound liquidity level. As all debts are from bank loans and bonds, the healthy funding structure suggests that there is considerable room for further refinancing.
Credit Rating: B+/ BB- (Issuer)
Related Article: “Idea of the Week: KWG – A bond that balances risk and return”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| KWGPRO 5.200% 21Sep2022 Corp (USD) | 13.389% |
| KWGPRO 7.400% 05Mar2024 Corp (USD) | 14.256% |
2. Ronshine China
Short Commentary on Issuer:
In 2019, the contracted sales of Ronshine was up 16.0% YoY, ranking 22nd in China. The deleveraging process executed by their management has reduced the net gearing to 78% and improved the cash to short term debt ratio to 1.6x, reflecting a better liquidity condition.
The Group has property projects concentrated in the golden areas of the first and second-tier cities such as Shanghai and Hangzhou, which are more resilient. With a focus on high-end residential buildings, Ronshine may face some significant price adjustments and further squeeze in its already-low margin. However, with the Group’s recent acquisition of land through low cost methods, and an already rich land bank, we foresee that Ronshine’s operations are sustainable over the long term.
Credit Rating: B+/ BB- (Issuer)
Related Article: “Investment strategy for Ronshine’s USD bonds”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| RONXIN 10.500% 01Mar2022 Corp (USD) | 16.473% |
| RONXIN 8.950% 22Jan2023 Corp (USD) | 13.743% |
3. CIFI Holdings
Short Commentary on Issuer:
AAs one of the first-tier developers in China, CIFI had an impressive contracted sales growth of 32.0% in 2019. It is worth noting that majority of CIFI’s construction projects are on a “crowd-funding” basis – where each project has multiple investors with CIFI taking on a smaller stake as the lead developer. Such arrangements enables the Group to commit less investment capital, which reduces the significant risk exposure to the individual projects, while also earning auxiliary fees for taking charge of the developments. The Group also possesses a healthy net gearing and cash to short term debt ratio at 70% and 3.3x respectively
Furthermore, CIFI’s property projects are mostly located in first and second-tier cities. While the company has a higher proportion of land bank in Hubei Province (about 7%), its weighted cost of financing is 5.9%, which is much lower than the industry average. We find that the debt structure is quite ideal and the credit risk is manageable.
Credit Rating: BB/ BB (Issuer)
Related Article: “Idea of the Week: How does CIFI Sustain Rapid Growth and a Decent Credit Profile at the Same Time?”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| CIFIHG 5.500% 23Jan2023 Corp (USD) | 10.722% |
| CIFIHG 6.450% 07Nov2024 Corp (USD) | 10.3% |
4. Sunac China
Short Commentary on Issuer:
As one of the leaders in the sector, Sunac’s total contracted sales in 2019 ranked fourth in the country, up 21% YoY. The growth was modest and Sunac successfully met their sales targets.
Despite the net gearing and cash to short term debt ratio being 206% and 0.8x respectively, its rich land bank enables the Group to adopt a price cut strategy to maintain cash flow. Given 83% of the land bank is located in first and second-tier cities, the Group is expected to have a relatively stable performance.
Credit Rating: BB-/ BB (Issuer)
Related Article: “Idea of the Week: Sunac China - The Madman’s Conservative Road to Development”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| SUNAC 7.350% 19Jul2021 Corp (USD) | 15.889% |
| SUNAC 7.950% 08Aug2022 Corp (USD) | 14.295% |
5. Road King Infrastructure
Short Commentary on Issuer:
RRoad King focuses on two businesses: property sales and toll road operation, which have a growth of 20.4% and 2.6% YoY respectively. The cash to short term debt ratio of 1.2x reflects its decent short term solvency. If adjustments are made for perpetual bonds, the 52.3% net gearing will worsen to a real net gearing of 87%. Nonetheless, since the perpetual bonds do not have a coupon step-up clause after the designated callable dates, the Group’s debt maturity profile is still flexible.
Looking into the land reserve as at June 2019, only 3% are located in Hubei province, while the other five toll roads are all outside Hubei. We believe the impact of the coronavirus will not be devastating for the Group.
Credit Rating: BB-/ N.R (Bonds)
Related Article: “Newly Issued Bond: Road King Infrastructure USD Bond (Chinese Only)”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| ROADKG 4.700% 06Sep2021 Corp (USD) | 10.452% |
| ROADKG 7.875% 01Feb2023 Corp (USD) | 7.854% |
6. Seazen Holdings
Short Commentary on Issuer:
Seazen is considered a first-tier developer in China, ranking eighth in terms of contracted sales in 2019 with a decent growth of 22.5% YoY. As the initial attention from the Wang Zhenhua scandal slowly wore off, most banks associated with Seazen gradually began offering funding again starting from October 2019. The Group’s refinancing ability has improved, especially after several successful bond issues recently.
Given that a significant portion of revenue is driven by Seazen’s commercial properties (Wuyue Plazas), it is likely that this segment of their revenue will be severely hit by the pandemic. Nonetheless, the Group still has a sufficient amount of cash to maintain its net gearing and cash to short term debt ratio at 80% and 1.8x respectively. Despite their conservative approach to acquisitions, the Group has managed to build up a rich land bank, which we believe to be sufficient in meeting the land usage in the coming three to four years.
Credit Rating: BB-/ BB (Bonds)
Related Article: “Bond Focus: Seazen—Starting Afresh after Scandal”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| FTLNHD 7.500% 16Dec2021 Corp (USD) | 11.476% |
| FTLNHD 6.800% 05Aug2023 Corp (USD) | 10.361% |
7. Yuzhou Property
Short Commentary on Issuer:
Yuzhou is a second-tier developer in China. Its contracted sales growth remained at a strong level of around 34% YoY in 2019. 70% of their sales and land banks are concentrated in Yangtze River Delta, especially in first and second-tier cities like Shanghai, Nanjing, Suzhou and Hangzhou. The Group’s land reserve is rich, whereas the cost of the acquired land is low.
The Group has a net gearing of 87%, which is slightly above the industry average. Their 2.6x cash to short term debt ratio is also partially attributed to their ability to issue longer term bonds to refinance debt. We think the company has the capability to hold up against the negative impacts of the coronavirus outbreak as it faces relatively lesser pressure (compared to their peers) on its short term debt repayment.
Credit Rating: BB-/ BB- (Issuer)
Related Article: “Idea of the Week: Yuzhou’s 100-billion Journey”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| YUZHOU 6.000% 25Jan2022 Corp (USD) | 9.388% |
| YUZHOU 6.000% 25Oct2023 Corp (USD) | 10.795% |
8. Logan Property
Short Commentary on Issuer:
The total contracted sales had an impressive increase of 33.7% YoY in 2019. Their net gearing of 65.4% also outranks many other developers of similar credit ratings.
In addition, the Group has a cash to short term debt ratio of 1.6x, reflecting its short term liquidity to cushion the negative impacts of the pandemic. Since the weighted cost of financing remains at a decent level of 6.1% and the key areas of development are all located in the Greater Bay Area, we think the Group’s credit profile is healthy.
Credit Rating: BB/ BB (Issuer)
Related Article: “New Issued Bond: Logan Property USD Bond (Chinese only)”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| LOGPH 7.500% 25Aug2022 Corp (USD) | 11.64% |
| LOGPH 6.500% 16Jul2023 Corp (USD) | 9.999% |
9. Agile Property
Short Commentary on Issuer:
The Group’s property sales grew steadily in 2019 with a YoY growth of 14.9%. The existing land reserve is adequate to support sales for the upcoming years. Given that most of the land banks are located in Southern China and the Greater Bay Area, the average sales price is expected to stay resilient during the coronavirus outbreak.
Although the cash to short term debt ratio only stands at 0.92x and the adjusted actual net gearing is as high as 145%, the Group’s strengths lie in their high profitability and refinancing ability, which can help lower its credit risk. The perpetual bonds also provide the group with flexibility to improve their debt repayment profile.
Credit Rating: BB/ N.R (Issuer)
Related Article: “Idea of the Week: Agile Property – A Traditional Developer with Major Presence in Southeast China”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| AGILE 8.500% 18Jul2021 Corp (USD) | 9.186% |
| AGILE 5.125% 14Aug2022 Corp (USD) | 10.994% |
Others
I. Shui On Land
Short Commentary on Issuer:
Shui On is a small-sized developer in comparison to its Chinese peers, and has a higher proportion of revenue generated from rental business. As at June 2019, the Group stated that an approximate 44% of their newly built commercial buildings are located in the Wuhan area. We can expect this part of their revenue to be significantly affected.
Nevertheless, Shui On has a net gearing of only 50% and a cash to short term debt ratio of 1.3x. Its overall credit profile surpasses some of the investment grade developers. The healthy positioning suggests that Shui On’s credit risk will remain manageable under the pandemic. The Group does not have a credit rating, but we believe their credit health is comparable to the BB grade level.
Credit Rating: N.R/ N.R
Related Article: “Idea of the Week: Shui On Land - Low-risk HK-Style Mainland Property Developer”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| SHUION 5.750% 12Nov2023 Corp (USD) | 6.12% |
| SHUION 5.500% 03Mar2025 Corp (USD) | 6.51% |
II. Central China
Short Commentary on Issuer:
Central China is a mid-sized developer with a high 39.8% YoY increase in 2019’s contracted sales. The net gearing also stands at a healthy level of 60.5%. However, a major concern is the Group’s over-concentration in the Hunan market, a neighbourhood of Hubei. Since all of their land reserves are located in Hunan province, the Group will be significantly affected by the coronavirus outbreak. This has resulted in their bonds having the highest yields among the BB grade peers.
However, the Group still possesses a cash to short term debt ratio of 3.4x. After a recent short term bond issuance, they should be able to effectively alleviate the short term liquidity pressure. Nonetheless, investors should still consider the further impact from the pandemic.
Credit Rating: B+/ BB- (Issuer)
Related Article: “Newly issued Bond: Central China USD bond (Chinese only)”
Related Bonds:
| Bond Name | Ask Net Yield to Maturity (as at 20 Mar 2020) |
| CENCHI 6.500% 05Mar2021 Corp (USD) | 21.702% |
| CENCHI 6.750% 08Nov2021 Corp (USD) | 15.108% |
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has principal positions in RONXIN 10.500% 01Mar2022 Corp (USD) and LOGPH 6.125% 16Apr2021 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.









