


- Company Overview: Yinson is a publicly listed global energy infrastructure company with a market capitalisation of RM5.8 billion as of 21 July 2026. As of 1Q27 (April 2026), approximately 95% of its revenue is generated from its Offshore Production and Marine segment, primarily driven by its Engineering, Procurement, Construction, Installation and Commissioning (EPCIC) activities and Floating Production Storage and Offloading (FPSO) leasing business.
- Strong Contract Backlog Supporting Cash Flow: As of 1Q27, Yinson has secured a robust USD19.3 billion contracted revenue backlog from long-term charter contracts with remaining tenures of 20–25 years, providing stable and recurring cash flows to support debt servicing and mitigate short-term liquidity risks.
- Transition to Operational Phase: In 1Q27, revenue declined 15% YoY to RM1.05 billion from RM1.23 billion, primarily due to the absence of EPCIC revenue following the completion of the Agogo FPSO and the commencement of its charter on 12 August 2025 (3QFY26). This was partially offset by earnings contribution from the Agogo FPSO's operations.
- Low Downtime Supports Earnings Stability: Yinson’s FPSO fleet maintains high operational reliability, with a 5-year average technical uptime of 99.6%, translating into minimal downtime and strong asset availability. This supports stable recurring leasing income under long-term charter contracts, while fleet commercial performance constantly above 100% initial target, reflects additional upside from performance-based incentives.
- Improving Operating Profitability: Despite lower revenue, operating profit increased 9% YoY to RM523 million, mainly driven by contributions from the Agogo FPSO's operations (which transitioned from EPCIC to higher-margin FPSO leasing), which provides more stable recurring earnings through long-term charter contracts.
- Highly Leveraged but moderately Improvement: Adjusted net gearing improved slightly to 203% in 1Q27 from 211% in FY26 (January 2026), mainly due to the repayment of RM370 million in loans and borrowings. Net debt-to-EBITDA remained elevated at 5.3 times. Nevertheless, this is supported by a strong order book, with an order book-to-net debt ratio of 5.2 times.
- Improving Cash Flow Supports Liquidity: While interest coverage remained relatively low at 1.4 times in 1QFY27, the cash-to-short-term debt ratio improved to 2.0 times from 1.7 times. This was supported by operating cash flow turning positive at RM689 million (1QFY26: negative RM113 million), reflecting the transition of Yinson’s FPSO projects from an EPC-led business model towards one increasingly supported by recurring charter income. As several FPSO projects, including FPSO Maria Quitéria, FPSO Atlanta and FPSO Agogo, progressed into the operational phase, construction-related cash outflows tapered off, improving overall cash flow generation.
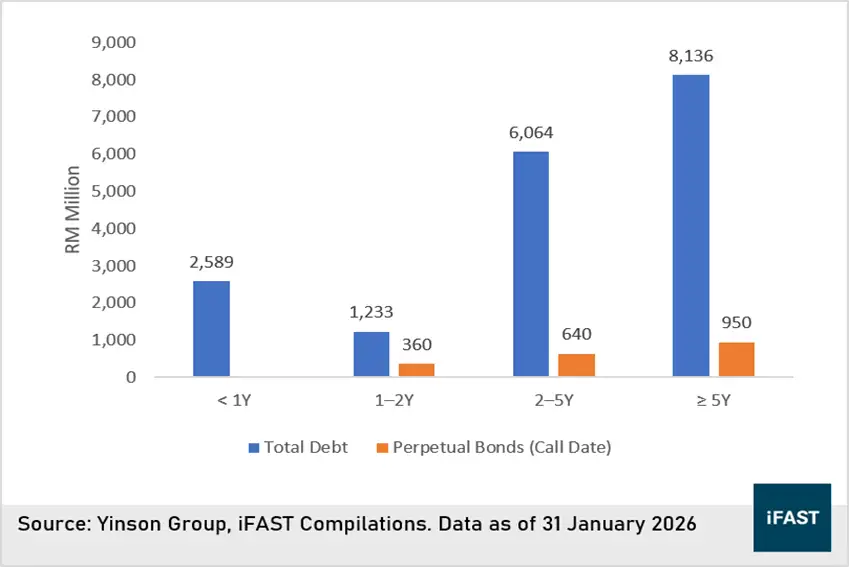
- Manageable Debt Maturity Profile: As of FY26, Yinson held RM5.4 billion in cash and undrawn credit facilities, which is sufficient to cover the RM4.2 billion (21% of total debt) maturing within the next two years. The remaining 79% matures thereafter, reflecting a well-staggered debt maturity profile. We believe the group is well positioned to refinance its upcoming maturities, supported by its USD19.3 billion contracted revenue backlog.
Chart 1: Yinson’s Debt Maturity Profile
- FPSO remain resilience: Despite oil price volatility, as projects are typically sanctioned only after substantial upfront capital has been committed. Once production begins, operators generally continue extracting oil to maximise returns on their investment, supporting stable demand for FPSOs under long-term contracts.
- Recommendation: Investors may consider holding Yinson's bonds, supported by its resilient contracted cash flows and adequate liquidity, despite its elevated leverage (Table 1).
- For further insight, please look at Yinson’s New Sukuk Issuance: 5-Year and/or 7-Year MYR Bonds with IPG of 4.80%–5.00% | Bondsupermart and Credit Update: Yinson Strong FPSO Growth with Capital Raise Amid Credit Strains | Bondsupermart.
Table 1: Yinson’s Bonds
|
Bond |
Years to next call/ Maturity |
Yield to next call/ Maturity |
Credit Rating (RAM) |
|
-/ 5M |
-/3.6% |
A1 |
|
|
1Y 4M/- |
4.7%/7.4% |
A3 |
|
|
1Y 5M/- |
4.7%/7.6% |
A3 |
|
|
2Y 8M/- |
5.1%/7.7% |
A3 |
|
|
-/4Y 5M |
-/4.6% |
A1 |
|
|
-/6Y 5M |
-/4.9% |
A1 |
|
|
Source: FSMONE, iFAST compilation. Data as of 27 July 2026 |
|||
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report holds a NIL position in the abovementioned securities.









