FWD Group Holdings Limited (“FWD”) is gearing up for its initial public offering (“IPO”) on the New York Stock Exchange. The company filed for the proposed IPO on 24 September 2021 to list its American Depository Shares (“ADS”) on the New York Stock Exchange (“NYSE”) under the ticker, “FWD”.
We remain positive on FWD due to its growth runway as a legacy light player in the insurance space. This article will take a dive into FWD and evaluate its business and credit profile prior to its IPO in the US.
1H21 Financial Results
For the first half financial results ending 30 June 2021 (“1H21”), FWD reported total revenues of USD 6,021m in 1H21, representing a 52.8% year-on-year (“YoY”) increase when compared to 1H20 results.
Strong growth in insurance business segment: Net premiums and fee income accounted for USD 4,849m of total revenue and grew 36.1% YoY. The growth in net premiums and fee income was due to organic growth in FWD’s insurance business and acquisitions. Net premiums and fee income in Hong Kong (and Macau) grew by 100.2% in 1H21 due to acquisitions of MetLife Limited and Metropolitan Life Insurance Company of Hong Kong Limited in 2020. In Thailand and Japan, net premiums and fee income increased by 7.4% and 2.8% respectively due to the growth in sales on insurance products. Emerging markets increased by 104.9% due to strong growth and sales through bancassuance partnerships with PT Bank Commonwealth in Indonesia and VCB in Vietnam.
Improvement in bottom line profits: Net profit for the company was USD 205m, representing a profitable half for the company as compared to other loss making fiscal years (“FY”) in FY19 (net loss of USD 332m) and FY20 (net loss of USD 252m). Total expenses for FWD was USD 5,813m in 1H21, representing a 36.4% increase YoY. The company showed successful cost saving measures by keeping general expenses flat at USD 564m in 1H21 as compared to USD 562m in 1H20. This partly resulted in an improvement in FWD’s bottom line, creating a profitable half for 1H21 as compared to a net loss of USD 318m a year ago.
Underwriting still remain unprofitable: Although FWD was profitable for 1H21, the combined ratio for FWD was 105.3%, representing an underwriting loss for FWD. For context, combined ratio is the combination of loss ratio and expense ratio. Loss ratio is calculated by the proportion of net insurance and investment contract benefits to net premiums and fee income. A combined ratio of below 100% represents an underwriting profit, where net premium income is more than net insurance claims.
Table 1: A breakdown of combined ratio for FWD Group
|
In USD millions |
1H21 |
FY20 |
1H20 |
FY19 |
|
Net premiums and fee income |
4,849 |
7,682 |
3,564 |
5,127 |
|
Net insurance and investment contract benefits |
4,482 |
7,295 |
3,159 |
4,885 |
|
Loss ratio (A) |
92.4% |
95.0% |
88.6% |
95.3% |
|
Expense ratio (B) |
12.9% |
14.7% |
13.9% |
17.8% |
|
Combined ratio (A+B) |
105.3% |
109.7% |
102.5% |
113.1% |
| Source: Company. | ||||
From Table 1, the combined ratio for FWD increased in 1H21 as compared to 1H20 from 102.5% to 105.3%. This was due to net insurance and investment contract benefits increasing by 41.9% YoY compared to an increase in net premiums and fee income by 36.1% YoY. As FWD is one of the youngest players in the insurance industry, it is expected that the company will suffer underwriting losses during the early stages of its business. It should also be noted that the combined ratio improved from FY20 to 1H21.
However, several key performance indicators for FWD such as Annualized Premium Equivalent (“APE”) and Value of New Business (“VNB”) show FWD has tons of value creation as it continues to grow its insurance business. APE measures operational performance and consist of the sum of 10% of single premiums and 100% of annualised first year premiums for all new policies. Although APE was flat for 1H21 at USD 751m, underlying APE (which measures the impacts of acquisitions and associated partnerships) grew by 11.7% from USD 614m in 1H20 to USD 686m in 1H21, reflecting growth in the underlying business through product innovation, channel optimisation and digitalisation.
VNB represents the value to shareholders from the new business issued and VNB grew 47.5% YoY to USD 346m. Although APE in Thailand and Japan declined, VNB in both these regions grew, reflecting a change towards more profitable products.
Liquidity and credit profile
As of 30 June 2021, FWD have cash and cash equivalents of USD 2,541m. Net cash used in operations was USD 132m in 1H21 compared to net cash provided from operations of USD 428m in 1H20. This was due to an increase in cash outflow on settlement to trade and other payables and obligations under repurchase and forward agreements.
Strong solvency ratios: Total available capital for FWD’s key operating segments are well above minimum local regulatory requirements. In 1H21, solvency ratio for Hong Kong was 291%, for Thailand was 310% and for Japan was 1,211%.
Potential IPO to boost capital position: An NYSE IPO will improve FWD’s capital position for more acquisitions and digitalisation of its insurance business. FWD is looking to raise between USD 2 to 3 billion in share sales through the IPO. In its F-1 fillings with the US Securities and Exchange Commission, FWD intends to use the some of its proceeds from the IPO to repay its debt obligations, further improving its balance sheet.
ESG consideration
Taking a look at FWD’s ESG considerations, the company adheres to the Global Reporting Initiative (“GRI”) and Sustainability Accounting Standards Board (“SASB”) disclosures which is in line with standard ESG reporting. The company identified 7 UN Sustainable Development Goals (“SDG”) to align their business with, the 7 SDGs being – 1) Good health and wellbeing, 2) Quality education, 3) Decent work and economic growth, 4) Industry, innovation and infrastructure, 5) Reduced inequalities, 6) Sustainable cities and communities and 7) Climate action. The company has set several goals to be achieved by 2024 and will report their progress annually.
In the environmental aspect,
FWD aims to integrate ESG criteria into their investment process and transition
towards a low-carbon economy to help achieve net zero emissions. Within the
social aspect, FWD aims to achieve 40-60% gender balance at executive and
senior management positions. FWD also has more than 50% of its board of
directors being independent.
Considering the good disclosure of its ESG metrics and having goals till 2024,
we are positive on FWD’s ESG profile.
Our recommendation
We remain positive on our views on FWD due to its growing insurance and digitalisation business and strong balance sheet. FWD released a consent solicitation exercise (“CSE”) to restructure and consolidate their debt under their parent, PCGI Intermediate Holding Limited (“PCGIIH”), also owned by Richard Li (see article – “FWD Group launches consent solicitation exercise to restructure debt”). Therefore, FWDGRP and FWDINS will be issued under a single parent, PCGIIH, which will be renamed to FWD Group Holdings Limited before the IPO.
Figure 1: Relative valuation among Fixed Insurance USD
Notes
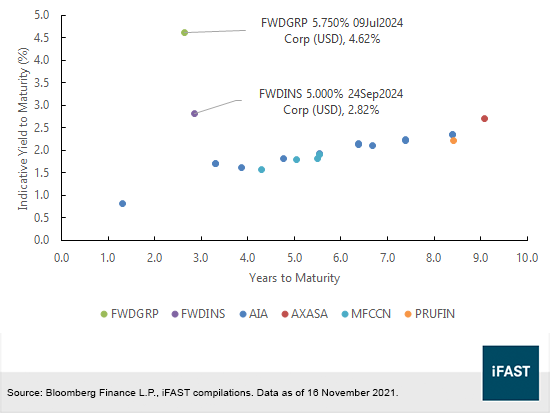
FWD is one of the higher yielding issuers in the insurance space and is due to its smaller asset size and being the younger player in the insurance business. From Figure 1, FWDGRP 5.750% 09Jul2024 Corp (USD) offers a yield to maturity (“YTM”) of 4.62% with about 2 years to maturity while FWDINS 5.000% 24Sep2024 Corp (USD) offers a YTM of 2.82% also with about 2 years to maturity. We remain positive on FWDGRP 5.750% 09Jul2024 Corp (USD) as we expect FWD to continue to grow its insurance business in Asia especially in emerging markets. Given its strong solvency ratios, FWD’s balance sheet remains strong despite low profitability in its insurance business.
Additionally, investors may also consider the FWDGRP 6.375% Perpetual Corp (USD) with an indicative yield to next call (“YTC”) of 6.01%. The perps are first callable on 13 September 2024 and will reset to the sum of the prevailing 5-year US Treasury yield plus the initial spread of 4.876% if not redeemed. But there is a high likelihood the perps will be redeemed due to its high initial spread of 4.876%. However, it is also noted that FWD will face a bottleneck of redemptions in 2024 with both FWDGRP 5.750% 09Jul2024 Corp (USD) and FWDINS 5.000% 24Sep2024 Corp (USD) expiring in 2024 as well.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in FWDGRP 5.750% 09Jul2024 Corp (USD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!