Monetary policy is set to tighten in 2022 and bond issuances may be lower compared to previous years.
However, most issuers maintain a strong credit profile and we have listed the list of 2022 bonds in Appendix 1.
Many of them are still investable, but we prefer the short-term, higher-yielding names.
2021 has come to a close and market observers, polled by Bloomberg, predicted that the US 10-year Treasury yield will end 2022 at around 1.85%, up from its current level of 1.54% on 30 December 2021.
Bloomberg poll participants also predicted that WTI crude will end 2022 at USD 74 per barrel (close to USD 72 per barrel at the time of the survey) while the S&P 500 Index is projected to rise slightly to 4,701 (time of survey: around 4636). In general, survey participants expressed less certainty about the stock index and oil price, but were nevertheless more confident about the direction of 10-year US Treasury yields in 2022.
In the same poll by Bloomberg, some 700 respondents cited inflation, coronavirus and geopolitical risks as the largest headwinds for 2022. On the geopolitical front, the main examples given were the tensions between China and Taiwan, as well as between Russia and Ukraine. News about a new Omicron variant recently surfaced that may result in further supply chain disruptions and cause consumer prices to remain at a heightened level.
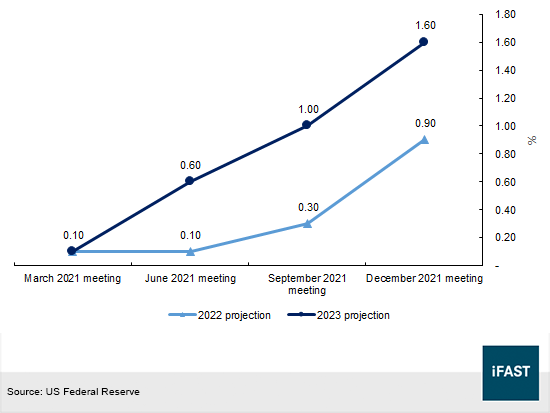
To address widespread inflationary concerns, the US Federal Reserve indicated that it may conduct three interest rate hikes in 2022. At the recent December 2021 FOMC meeting, the median Fed funds rate was projected to increase to 0.90% in 2022 and 1.60% in 2023, up from 0.30% and 1.00% respectively at the September 2021 meeting (see Figure 1).
Figure 1: Projections of median Fed funds rate in 2022 and 2023
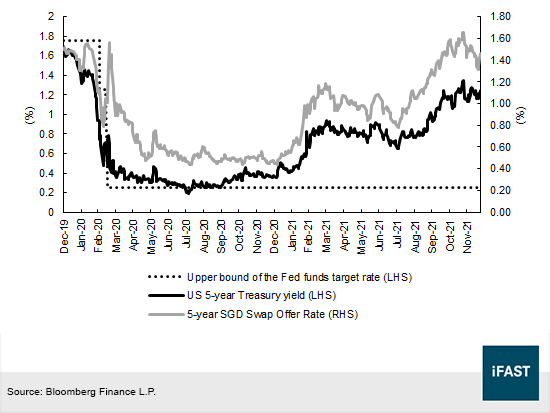
A higher Fed funds rate may imply higher 5-year US Treasury yields and elevated 5-year SGD Swap Offer Rates. The SGD Swap Offer Rate (“SOR”) is a function of short term USD rates (i.e. the Secured Overnight Financing Rate) and it has a strong historical correlation with US Treasury yields (Figure 2).
Figure 2: 5-year SGD Swap Offer Rate and 5-year US Treasury yields
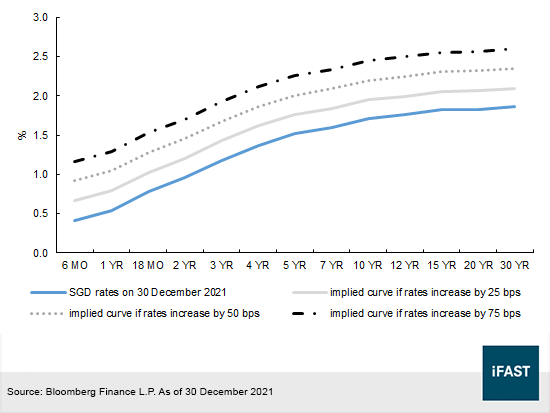
Using Bloomberg estimates, the 5-year SGD SOR may climb to 1.75% in a 25bps rate hike, or increase to as high as 2.25% if rates jump by 75 basis points (“bps”). (Figure 3).
Figure 3: Implied SGD rates in different rate hike scenarios
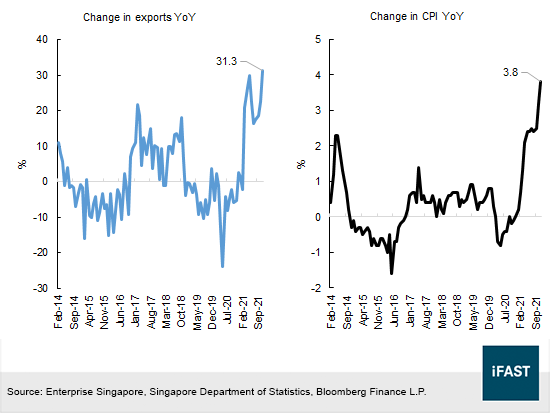
The Monetary Authority of Singapore (“MAS”) is also likely to tighten monetary policy in 2022. Recent economic data suggest that the economy is growing at a faster rate. Total exports in November increased 31.3% year-on-year (“YoY”) while consumer prices rose at a faster than expected pace of 3.8% YoY in the same month (Figure 4).
MAS expects consumer prices to increase by 1.5% to 2.5% in 2022. This means that inflation may fall from its current 3.8% YoY level as private transport inflation is projected to moderate next year due to a slower pace of increase in COE premiums and petrol costs. Some economists said that the inflation outlook depends on the spread of the Omicron variant as renewed lockdowns would dampen the demand for commodities and inflation.
Figure 4: Recent Singapore economic data
Moving on to bond issuances, Bloomberg estimated that SGD 25.2b of SGD bonds were issued in 2021 and this exceeded pre-pandemic levels. Most issuers rushed to refinance their borrowings at low interest rates. However, the number of bond IPOs reached a new multi-year low of 80 (Figure 5).
Figure 5: SGD bond issuances by year
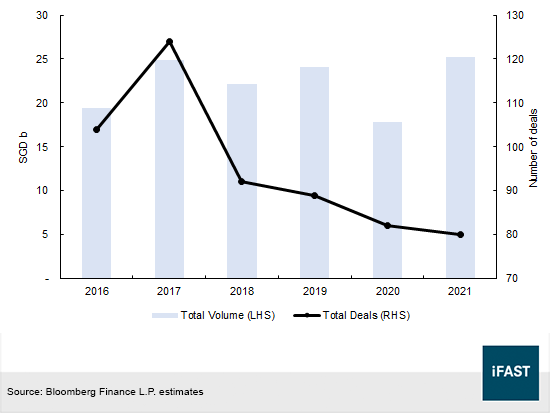
With monetary policy set to tighten in future and the possible start of a rate hike cycle, we may see more bond offerings in the first few months of 2022. Issuers would want to take the opportunity to refinance their debts at low interest rates. With interest rates set to rise in the later part of the year, the amount of issuances and number of deals may fall.
Figure 6: Number of issued SGD perpetual bonds by year
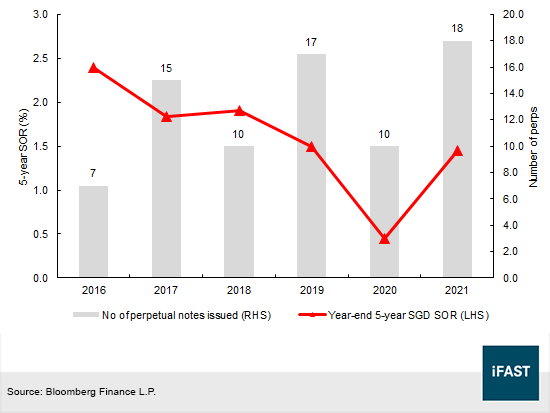
On a separate point, demand for perpetual bonds have been quite popular with SGD investors. In 2021, 18 SGD perpetual bonds were issued, and this represents the highest issuance over the last few years (Figure 6). The rise in perpetual bond issues coincided with a falling 5-year SGD Swap Offer Rate. However, perpetual issuances may fall in 2022 if swap rates increase. This is because issuers may not want to pay such high distributions to perpetual noteholders. For instance in 2016, we saw only 7 perp IPOs while the 5-year SOR was trading around 2.39%. In 2018, only 10 perps were issued when the 5-year SOR was around 1.91%.
Outlook on bonds maturing in 2022
Given the higher interest rate outlook and hawkish rhetoric from central banks, we are less optimistic about SGD bonds heading into 2022 than at the start of 2021. Longer duration bonds will be susceptible to higher interest rates and investors may see volatility in their bond portfolios. We think some issuers may not redeem their perpetual notes or pay down their bonds on their maturity dates.
In Appendix 1 below, we list down a financial snapshot of issuers whose bonds are maturing or callable in 2022. The cash flows, liquidity and short term financial obligations of each issuer is displayed in tables 1, 2 and 3. Generally speaking, issuers with cash flows and a large enough cash position should have sufficient liquidity to redeem their bonds.
Most issuers will redeem their bonds on their call dates or maturities. However, we are cautious on only a handful of bonds from issuers with high gearing and poor credit quality.
Issuers with low credit quality
Among them, we think the AUSGSP 7.000% 03Dec2022 Corp (SGD), GSHSP 5.200% 21Oct2022 Corp (SGD), MSFSSP 6.350% 22Jul2022 Corp (SGD) and ASPSP 6.000% 01Jul2022 Corp (SGD) have a low likelihood of being paid.
More specifically, these issuers are small companies that are not within our coverage or we have expressed a negative view in the past. In the article - “Aspial Corporation Ltd: here is our quick take on the proposed note exchange offer ”, we highlighted the issuer’s weak credit profile. Aspial Corporation is the parent entity of Maxi-Cash Financial Services and we believe that the MSFSSP 6.350% 22Jul2022 Corp (SGD) and ASPSP 6.000% 01Jul2022 Corp (SGD) have high refinancing risks.
To elaborate further, Maxi-Cash has a low level of cash relative to its SGD 230.21m of short-term debt as at 30 June 2021 (see Table 2 in Appendix 1). Its repayment ability hinges on senior creditors as the bulk of the group’s borrowings are secured by corporate guarantees by the company, as well as fixed and floating charges on all assets of all assets of certain subsidiaries.
We are also cautious on the GSHSP 5.200% 21Oct2022 Corp (SGD) issued by GSH Corporation Limited. The issuer had SGD 54.56m of cash at 30 June 2021, but we suspect a portion of this amount is pledged as security to obtain credit facilities. At the end of 2020, GSH disclosed that SGD 30.18m of the SGD 81.67m cash and cash equivalents were made up of pledged deposits. Of the SGD 72.05m of current borrowings in June 2021, SGD 16.60m are loans from a shareholder. GSH raised SGD 78.0 from a recent rights offering but had already utilised SGD 44.7m of the proceeds. Overall, we feel that GSH would have difficulty paying the October 2022 bonds.
Ausgroup defaulted on the AUSGSP 7.000% 03Dec2022 Corp (SGD) in 2016 and we believe that the firm may restructure the bonds ahead of its maturity given its present low level of liquidity.
Within the SGD perpetual space, we think that First REIT, and Lippo Malls Indonesia Retail Trust may not call back their perpetual notes on their call dates in 2022.
Lippo Malls Indonesia Retail Trust (“LMIRT”) is unlikely to redeem the LMRTSP 6.4751% Perpetual Corp (SGD) in March 2022 but may redeem either of the 2 perps during the second half of the year. The LMRTSP 6.4751% Perpetual Corp (SGD) was not called on its first call date on 27 September 2021, and the distribution rate subsequently declined from 7% to 6.4751%. Moving forward, LMIRT will pay SGD 9.07m of distributions to LMRTSP 6.4751% perpetual bondholders per year.
This amount is more than the SGD 7.92m of distribution expense stemming from the SGD 120m LMRTSP 6.600% Perpetual Corp (SGD). If there is only enough liquidity to redeem either of the 2 perps, LMIRT will likely redeem the LMRTSP 6.6% perpetual notes on 19 December 2022 as they have a lower distribution expense compared to the LMRTSP 6.4751% perps. However, if the 5-year SGD Swap Offer Rate (“SOR”) rises to 2.80%, the issuer will be indifferent towards either perp. Currently, the 5-year SOR is trading at 1.45% (29 December 2021), so we require a few rate hikes from the Federal Reserve in order for the 5-year SOR to reach 2.80%.
First REIT is due to pay down a SGD 100m secured bank loan maturing in May 2022. Its SGD 36.61m cash position is insufficient to cover short-term borrowings, and is not likely to call back the FIRTSP 4.9817% Perpetual Corp (SGD) in January or July 2022.
Issuers with good credit profiles
At the other end of the spectrum, we think that investors may consider investing in some of the higher yielding names. In our opinion, the ARTSP 3.070% Perpetual Corp (SGD), FPLSP 3.950% Perpetual Corp (SGD), WINGTA 4.080% Perpetual Corp (SGD) and ARASP 5.200% Perpetual Corp (SGD) have high call probabilities and are fairly priced.
Figure 7: Relative valuation of bonds maturing or callable in a year
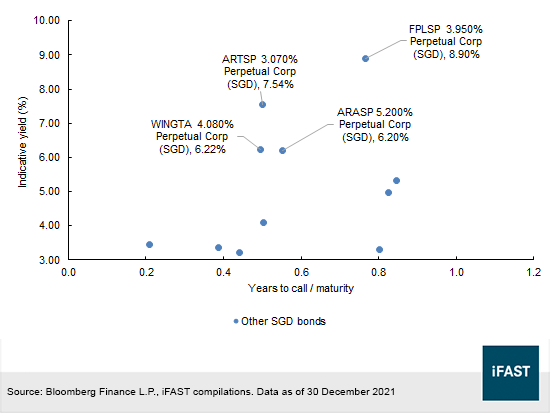
If Ascott Residence Trust does not redeem the ARTSP 3.07% notes on 30 June 2022, the bonds still have an attractive yield to next call of 5.35% and 4.60% at their call dates of 31 December 2022 and 30 June 2023 respectively. These valuations are quite appealing for a ‘BBB-’ (Fitch) rated entity.
Ascott Residence Trust has access to SGD 1.13b of available funds as at 30 September 2021, an amount that is more than enough to cover its SGD 774.0m of borrowings due in 2022. More countries have reopened their borders and we expect EBITDA to gradually improve moving forward.
WINGTA 4.08% Perpetual Corp (SGD), issued by Wing Tai Holdings Ltd has a decent valuation. The issuer may use its ~SGD 728.06m of liquidity to pay down its SGD 150.86m of short-term debt and SGD 150m perpetual note. Similarly, the FPLSP 3.950% Perpetual Corp (SGD) is likely to be redeemed as the issuer has access to SGD 3.00b of credit lines and SGD ~3.78b of cash. Lastly, with a cash position of USD 544.33m, ARA Asset Management has adequate capital to redeem the SGD 300m ARASP 5.200% Perpetual Corp (SGD).
Although, it may sound counterintuitive to recommend perpetual notes when interest rates are projected to rise. However, the aforementioned 4 issuers have a high credit ability to redeem their perpetual bonds in 2022. Secondly, referring to Table 1, the reset reference rates for the FPLSP 3.950% Perpetual Corp (SGD) and WINGTA 4.080% Perpetual Corp (SGD) are already trading close to their coupon rates. The reset reference rate may rise on higher interest rates and this provides an incentive for issuers to call back their perpetual notes. As for the ARTSP 3.07% and ARASP 5.2% perps, we think that the yields are still attractive at more than 5% even if the notes are not redeemed.
Table 1: SGD Perpetual bonds
|
Bonds |
Ask price |
Reset reference rate |
Reset date |
Next reset rate as of 30 December 2021 |
Indicative yield if called at next call date |
Indicative yield if called at subsequent call date |
|
ARTSP 3.070% Perpetual Corp (SGD) |
97.9 |
5-year SGD SOR + 2.5% |
30 June 2025 |
4.0375% |
7.54% |
5.35% |
|
FPLSP 3.950% Perpetual Corp (SGD) |
96.6 |
5-year SGD SOR + 2.245% + 100bps in October 2027 |
5 October 2022 |
3.7825% |
8.90% |
6.87% |
|
WINGTA 4.080% Perpetual Corp (SGD) |
99.0 |
5-year SGD SOR + 2.37% + 100bps in June 2027 |
28 June 2022 |
3.9075% |
6.22% |
5.11% |
|
ARASP 5.200% Perpetual Corp (SGD) |
99.5 |
7-year SGD SOR + 6.12% |
19 July 2024 |
7.7350% |
6.20% |
5.75% |
| Source: Bloomberg Finance L.P., iFAST compilations. As of 30 December 2021. | ||||||
Appendix 1
Table 2: Non-bank SGD securities callable or maturing in 2022
|
Issuer / Guarantor |
Outstanding bond |
Reporting period ended |
EST. 6m operating cash flow before working capital changes |
EST. 6m net operating cash flow |
Approximate cash / liquidity position |
Current borrowings |
Perpetual bonds callable in less than 2 years |
|
AIMS APAC REIT |
AAREIT 3.600% 22Mar2022 Corp (SGD) |
30 September 2021 |
SGD 43.23m |
SGD 40.05m |
SGD 108.32m |
SGD 106.74m |
N.A. |
|
Ascendas REIT |
AREIT 4.000% 03Feb2022 Corp (SGD) |
30 June 2021 |
SGD 406.97m |
SGD 389.75m |
SGD 309.27m |
SGD 1.24b |
N.A. |
|
Ascendas REIT |
AREIT 3.200% 03Jun2022 Corp (SGD) |
30 June 2021 |
SGD 406.97m |
SGD 389.75m |
SGD 309.27m |
SGD 1.24b |
N.A. |
|
Ascott Residence Trust |
ARTSP 4.205% 23Nov2022 Corp (SGD) |
30 June 2021 |
SGD 83.60m |
SGD 29.45m |
SGD 439.29m |
SGD 89.21m |
SGD 250.00m |
|
Ascott Residence Trust |
ASCHTS 3.325% 23Sep2022 Corp (SGD) |
30 June 2021 |
SGD 83.60m |
SGD 29.45m |
SGD 439.29m |
SGD 89.21m |
SGD 250.00m |
|
Ascott Residence Trust |
ARTSP 3.070% Perpetual Corp (SGD) |
30 June 2021 |
SGD 83.60m |
SGD 29.45m |
SGD 439.29m |
SGD 89.21m |
SGD 250.00m |
|
ARA Asset Management Ltd |
ARASP 5.200% Perpetual Corp (SGD) |
30 June 2021 |
USD 90.94m |
USD -44.09m |
USD 544.33m |
USD 35.40m |
USD 300.00m |
|
AusGroup Ltd |
AUSGSP 8.450% 03Dec2022 Corp (SGD) |
30 September 2021 |
SGD 4.24m |
SGD 1.89m |
SGD 7.45m |
SGD 1.07m |
N.A. |
|
CapitaLand China Trust |
CRCTSP 3.250% 04Jul2022 Corp (SGD) |
30 June 2021 |
SGD 117.63m |
SGD 80.09m |
SGD 236.44m |
SGD 72.37m |
N.A. |
|
CapitaLand Integrated Commercial Trust |
CCTSP 2.770% 04Jul2022 Corp (SGD) |
30 June 2021 |
SGD 445.23m |
SGD 417.14m |
SGD 350.24m |
SGD 697.88m |
N.A. |
|
CapitaLand Integrated Commercial Trust |
CMASP 3.700% 29Aug2022 Corp (SGD) |
30 June 2021 |
SGD 445.23m |
SGD 417.14m |
SGD 350.24m |
SGD 697.88m |
N.A. |
|
City Developments Ltd |
CITSP 3.750% 06Jul2022 Corp (SGD) |
30 June 2021 |
SGD 171.71m |
SGD 596.25m |
SGD 2.65b |
SGD 3.89b |
N.A. |
|
ESR Cayman Ltd |
ESRCAY 6.750% 01Feb2022 Corp (SGD) |
30 June 2021 |
USD 91.25m |
USD 8.07m |
USD 1.13b |
USD 1.39b |
N.A. |
|
ESR-REIT |
EREIT 4.600% Perpetual Corp (SGD) |
30 June 2021 |
SGD 82.72m |
SGD 77.14m |
SGD 13.98m |
SGD 124.74m |
SGD 150.00m |
|
First REIT |
FIRTSP 4.9817% Perpetual Corp (SGD) |
30 June 2021 |
SGD 33.86m |
SGD 25.51m |
SGD 36.61m |
SGD 98.59m |
SGD 60.85m |
|
GSH Corp Ltd |
GSHSP 5.200% 21Oct2022 Corp (SGD) |
30 June 2021 |
SGD -0.32m |
SGD -70.27m |
SGD 54.56m |
SGD 72.05m |
N.A. |
|
Hong Fok Corp Ltd |
HFCSP 4.200% 28Mar2022 Corp (SGD) |
30 June 2021 |
SGD 15.67m |
SGD 31.26m |
SGD 58.68m |
SGD 109.62m |
N.A. |
|
GuocoLand Ltd |
GUOLSP 4.000% 31Jan2022 Corp (SGD) |
30 June 2021 |
SGD 212.82m |
SGD 388.16m |
SGD 1.13b |
SGD 947.37m |
N.A. |
|
Hotel Properties Ltd |
HPLSP 4.650% Perpetual Corp (SGD) |
30 June 2021 |
SGD 31.84m |
SGD 11.66m |
SGD 78.93m |
SGD 60.91m |
SGD 150.00m |
|
Indian Oil Corp Ltd |
IOCLIN 4.100% 15Oct2022 Corp (SGD) |
30 September 2021 |
Rs 21,639.5 Crore |
Rs 24,219.3 Crore |
Rs 177.6 Crore |
Rs 32,699.1 Crore |
N.A. |
|
Keppel Corp Ltd |
KEPSP 3.145% 14Feb2022 Corp (SGD) |
30 June 2021 |
SGD 212.69m |
SGD -333.35m |
SGD 2.40b |
SGD 4.47b |
N.A. |
|
Keppel REIT MTN Pte Ltd |
KREITS 3.150% 11Feb2022 Corp (SGD) |
30 June 2021 |
SGD 74.49m |
SGD 74.26m |
SGD 127.01m |
SGD 152.24m |
N.A. |
|
Koh Brothers Group Ltd |
KOHSP 5.100% 27Oct2022 Corp (SGD) |
30 June 2021 |
SGD 7.30m |
SGD -22.59m |
SGD 102.37m |
SGD 72.92m |
N.A. |
|
Lippo Malls Indonesia Retail Trust |
LMRTSP 6.4751% Perpetual Corp (SGD) |
30 September 2021 |
SGD 16.55m |
SGD 9.32m |
SGD 133.23m |
SGD 7.03m |
SGD 259.14m |
|
Lippo Malls Indonesia Retail Trust |
LMRTSP 6.600% Perpetual Corp (SGD) |
30 September 2021 |
SGD 16.55m |
SGD 9.32m |
SGD 133.23m |
SGD 7.03m |
SGD 259.14m |
|
Mapletree Industrial Trust |
MINTSP 3.650% 07Sep2022 Corp (SGD) |
30 September 2021 |
SGD 195.25m |
SGD 238.83m |
SGD 172.75m |
SGD 612.57m |
N.A. |
|
Mapletree Investments Pte Ltd |
MAPLSP 3.950% Perpetual Corp (SGD) |
31 March 2021 |
SGD 1.58b |
SGD 712.13m |
SGD 1.92b |
SGD 1.91b |
SGD 1.325b |
|
Mapletree Investments Pte Ltd |
MAPLSP 4.500% Perpetual Corp (SGD) |
31 March 2021 |
SGD 1.58b |
SGD 712.13m |
SGD 1.92b |
SGD 1.91b |
SGD 1.325b |
|
Mapletree North Asia Commercial Trust |
MAGIC 3.430% 09Mar2022 Corp (SGD) |
30 September 2021 |
SGD 164.41m |
SGD 117.82m |
SGD 243.13m |
SGD 117.90m |
N.A. |
|
Mapletree North Asia Commercial Trust |
MAGIC 3.960% 09Nov2022 Corp (SGD) |
30 September 2021 |
SGD 164.41m |
SGD 117.82m |
SGD 243.13m |
SGD 117.90m |
N.A. |
|
Maxi-Cash Financial Services Corp Ltd |
MSFSSP 6.350% 22Jul2022 Corp (SGD) |
30 June 2021 |
SGD 21.86m |
SGD -18.63m |
SGD 14.09m |
SGD 230.21m |
N.A. |
|
Aspial Treasury Pte Ltd |
ASPSP 6.000% 01Jul2022 Corp (SGD) |
30 June 2021 |
SGD 35.79m |
SGD -24.09m |
SGD 36.60m |
SGD 604.84m |
N.A. |
|
Tuan Sing Holdings Ltd |
TSHSP 2.800% 18Oct2022 Corp (SGD) |
30 June 2021 |
SGD 24.42m |
SGD 41.10m |
SGD 329.94m |
SGD 836.47m |
N.A. |
|
Olam International Ltd |
OLAMSP 6.000% 25Oct2022 Corp (SGD) |
30 June 2021 |
SGD 926.84m |
SGD 995.01m |
SGD 3.54b |
SGD 6.62b |
SGD 350.00m |
|
Olam International Ltd |
OLAMSP 5.500% Perpetual Corp (SGD) |
30 June 2021 |
SGD 926.84m |
SGD 995.01m |
SGD 3.54b |
SGD 6.62b |
SGD 350.00m |
|
OUE Ltd |
OUESP 3.750% 17Apr2022 Corp (SGD) |
30 June 2021 |
SGD 69.36m |
SGD 15.93m |
SGD 330.69m |
SGD 461.23m |
N.A. |
|
Singapore Post Ltd |
SPOST 4.250% Perpetual Corp (SGD) |
30 September 2021 |
SGD 76.52m |
SGD 34.47m |
SGD 465.04m |
SGD 1.30m |
SGD 350.00m |
|
StarHub Ltd |
STHSP 3.080% 12Sep2022 Corp (SGD) |
30 June 2021 |
SGD 247.70m |
SGD 245.20m |
SGD 718.60m |
SGD 8.20m |
SGD 200.00m |
|
StarHub Ltd |
STHSP 3.950% Perpetual Corp (SGD) |
30 June 2021 |
SGD 247.70m |
SGD 245.20m |
SGD 718.60m |
SGD 8.20m |
SGD 200.00m |
|
Suntec REIT |
SUNSP 3.025% 16Mar2022 Corp (SGD) |
30 June 2021 |
SGD 109.59m |
SGD 77.39m |
SGD 393.03m |
SGD 935.63m |
N.A. |
|
Singtel Limited |
SGTOPT 3.240% 29Sep2022 Corp (SGD) |
30 September 2021 |
SGD 1.90b |
SGD 2.87b |
SGD 767.50m |
SGD 1559.20m |
N.A. |
|
Wing Tai Properties Ltd |
WINGTP 4.350% Perpetual Corp (SGD) |
30 June 2021 |
N.A. |
HKD 689.50m |
HKD 1338.80m |
HKD 1395.50m |
SGD 260.00m (~HKD 1.50b) |
|
Wing Tai Properties Ltd |
WINGTP 4.250% 29Nov2022 Corp (SGD) |
30 June 2021 |
N.A. |
HKD 689.50m |
HKD 1338.80m |
HKD 1395.50m |
SGD 260.00m (~HKD 1.50b) |
| Source: Company filings, iFAST estimates | |||||||
Table 3: Other non-bank SGD securities callable or maturing in 2022
|
Issuer / Guarantor |
Outstanding bond |
Reporting period ended |
EST. 12m operating cash flow before working capital changes |
EST. 12m net operating cash flow |
Approximate cash / liquidity position |
Current borrowings |
Perpetual bonds callable in less than 2 years |
|
Keppel Land Ltd |
KPLDSP 3.800% 08Jun2022 Corp (SGD) |
31 December 2020 |
SGD 368.65m |
SGD 469.15m |
SGD 998.81m |
SGD 1602.24m |
N.A. |
|
Oxley Holdings Ltd |
OHLSP 5.700% 31Jan2022 Corp (SGD) |
30 June 2021 |
SGD 280.40m |
SGD 623.57m |
SGD 85.56m |
SGD 784.09m |
N.A. |
|
Frasers Centrepoint Trust |
FCTSP 2.645% 06Jun2022 Corp (SGD) |
30 September 2021 |
SGD 214.90m |
SGD 198.45m |
SGD 42.23m |
SGD 204.83m |
N.A. |
|
Frasers Property Group |
FPLSP 3.650% 22May2022 Corp (SGD) - Retail |
30 September 2021 |
SGD 1.06b |
SGD 1.36b |
SGD 3.78b |
SGD 4.85b |
SGD 650.00m |
|
Frasers Property Group |
FPLSP 3.950% Perpetual Corp (SGD) |
30 September 2021 |
SGD 1.06b |
SGD 1.36b |
SGD 3.78b |
SGD 4.85b |
SGD 650.00m |
|
Fraser and Neave Ltd |
FNNSP 3.090% 23Mar2022 Corp (SGD) |
30 September 2021 |
SGD 246.33m |
SGD 247.40m |
SGD 471.80m |
SGD 427.57m |
N.A. |
|
Fraser and Neave Ltd |
FNNSP 2.800% 22Aug2022 Corp (SGD) |
30 September 2021 |
SGD 246.33m |
SGD 247.40m |
SGD 471.80m |
SGD 427.57m |
N.A. |
|
Frasers Hospitality REIT |
FHREIT 2.630% 06Jul2022 Corp (SGD) |
30 September 2021 |
SGD 48.97m |
SGD 38.70m |
SGD 73.72m |
SGD 202.51m |
N.A. |
|
Thomson Medical Group Ltd |
TMGSP 4.800% 18Jul2022 Corp (SGD) |
30 June 2021 |
SGD 67.46m |
SGD 61.25m |
SGD 122.68m |
SGD 0.32m |
N.A. |
|
Wing Tai Holdings Ltd |
WINGTA 4.080% Perpetual Corp (SGD) |
30 June 2021 |
SGD 75.87m |
SGD 149.50m |
SGD 728.06m |
SGD 150.86m |
SGD 150.00m |
|
Wing Tai Holdings Ltd |
WINGTA 4.500% 26Sep2022 Corp (SGD) |
30 June 2021 |
SGD 75.87m |
SGD 149.50m |
SGD 728.06m |
SGD 150.86m |
SGD 150.00m |
| Source: Company filings, iFAST estimates | |||||||
Table 4: Bank SGD perpetual notes callable in 2022
|
Issuer / Guarantor |
Outstanding bond |
Reporting period ended |
CET1 capital |
Cash and balances at central banks |
Total liabilities |
Total equity |
High-quality liquid assets |
|
HSBC Holdings PLC |
HSBC 4.700% Perpetual Corp (SGD) |
30 September 2021 |
USD 133.2b |
USD 409.92b |
USD 2762.1b |
USD 206.7b |
USD 664.0b |
|
Julius Baer Group Ltd |
BAERVX 5.750% Perpetual Corp (SGD) |
30 September 2021 |
CHF 3.58b |
CHF 16.60b |
CHF 106.85b |
CHF 6.73b |
CHF 23.54b |
| Source: Company filings, iFAST estimates | |||||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in AAREIT 5.375% Perpetual Corp (SGD), ARASP 5.200% Perpetual Corp (SGD),ARTSP 3.070% Perpetual Corp (SGD),CATHAY 3.375% 22Jan2023 Corp (SGD),CHIPEN 6.000% 15Mar2022 Corp (SGD),CMZB 4.875% 01Mar2027 Corp (SGD),CS 5.625% Perpetual Corp (SGD),ESRCAY 5.650% Perpetual Corp (SGD),ESRCAY 6.750% 01Feb2022 Corp (SGD),FIRTSP 4.9817% Perpetual Corp (SGD),FPLSP 4.980% Perpetual Corp (SGD),GUOLSP 3.290% 26Oct2026 Corp (SGD),HSBC 4.700% Perpetual Corp (SGD),KEPSP 2.900% Perpetual Corp (SGD),LMRTSP 6.600% Perpetual Corp (SGD),MLTSP 3.725% Perpetual Corp (SGD),OHLSP 6.900% 08Jul2024 Corp (SGD),OLAMSP 5.375% Perpetual Corp (SGD),OLAMSP 6.000% 25Oct2022 Corp (SGD),OUECT 3.950% 02Jun2026 Corp (SGD),OUESP 3.750% 17Apr2022 Corp (SGD),SINTEC 4.200% Perpetual Corp (SGD),SPHSP 4.500% Perpetual Corp (SGD),STRTR 3.750% 29Oct2025 Corp (SGD),STSP 3.300% Perpetual Corp (SGD),SUNSP 3.800% Perpetual Corp (SGD),TMGSP 4.800% 18Jul2022 Corp (SGD),TSHSP 6.900% 18Oct2024 Corp (SGD),UBS 5.875% Perpetual Corp (SGD),UOBSP 2.550% Perpetual Corp (SGD) and WINGTA 4.080% Perpetual Corp (SGD). The analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!